


EN
What Is Behind Seaboard (SEB) Shares Sliding Today?
Seaboard (SEB) just posted third quarter and nine month earnings, reporting revenue of US$2.8b for the quarter and US$8.1b year to date, while quarterly net income came in at US$28 million.
Seaboard’s share price has been under pressure, with the stock down 8.66% on the day of the earnings release and recording a 7 day share price return of negative 12.29%. The year to date share price return is down 22.90%, and the 1 year total shareholder return has declined a more moderate 5.25%, pointing to fading momentum after a tougher recent stretch.
Scan beyond Seaboard’s recent share price pressure and explore other potential rebound stories with our hand picked 35 high quality undervalued stocks.
Seaboard’s slide has opened up a discount to some fair value estimates, yet the latest quarter showed sharply lower quarterly earnings per share. Is this price weakness an overreaction, or a clear warning on valuation?
Preferred P/E of 5.2x: Is it justified?
On earnings terms, Seaboard looks inexpensive. The stock last closed at $3,410.25 while the P/E ratio sits at 5.2x, which is far below both the broader US market on 18x and the US Food industry on 17.4x. That large gap puts the current valuation in clear focus for anyone weighing the latest share price slide.
The P/E ratio compares what investors are paying for each dollar of profit. For a diversified business like Seaboard, which spans pork, commodity trading and milling, marine shipping, power and fuel, this metric helps you judge how the market is pricing its earnings against other food and agriculture related operators.
Recent numbers add more context. Earnings grew very strongly over the past year and net profit margins moved from 1.6% to 6.2%. Earnings growth over the last twelve months was also well ahead of the Food industry, which recorded a decline of 4.6%. Given that backdrop, the current 5.2x P/E suggests the market is putting a heavy discount on those profits compared with both industry peers on 17.4x and a broader peer group on 27.7x, even though the SWS DCF model currently indicates the share price is above its future cash flow value estimate of $254.52.
On balance, the earnings multiple screens as cheap relative to both sector and peer averages, while the DCF view is more cautious on long term cash generation at today’s share price. That split highlights how different valuation tools can point to very different conclusions and why you may want to test your own assumptions around Seaboard’s future profitability and reinvestment needs before leaning on a single figure.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 5.2x (UNDERVALUED)
Still, Seaboard’s complex mix of pork, commodity trading, shipping and power, along with an intrinsic value estimate below the current share price, could keep investors cautious.
Find out about the key risks to this Seaboard narrative.
Another View: What The SWS DCF Model Says About Seaboard
The SWS DCF model presents a very different picture for Seaboard. While the shares trade at $3,410.25, the future cash flow value estimate sits at $254.52. This implies the stock is trading well above that modelled level. That gap flags valuation risk rather than a clear bargain and raises a simple question for you: Which signal carries more weight, cheap earnings or cautious cash flow math?
Look into how the SWS DCF model arrives at its fair value.
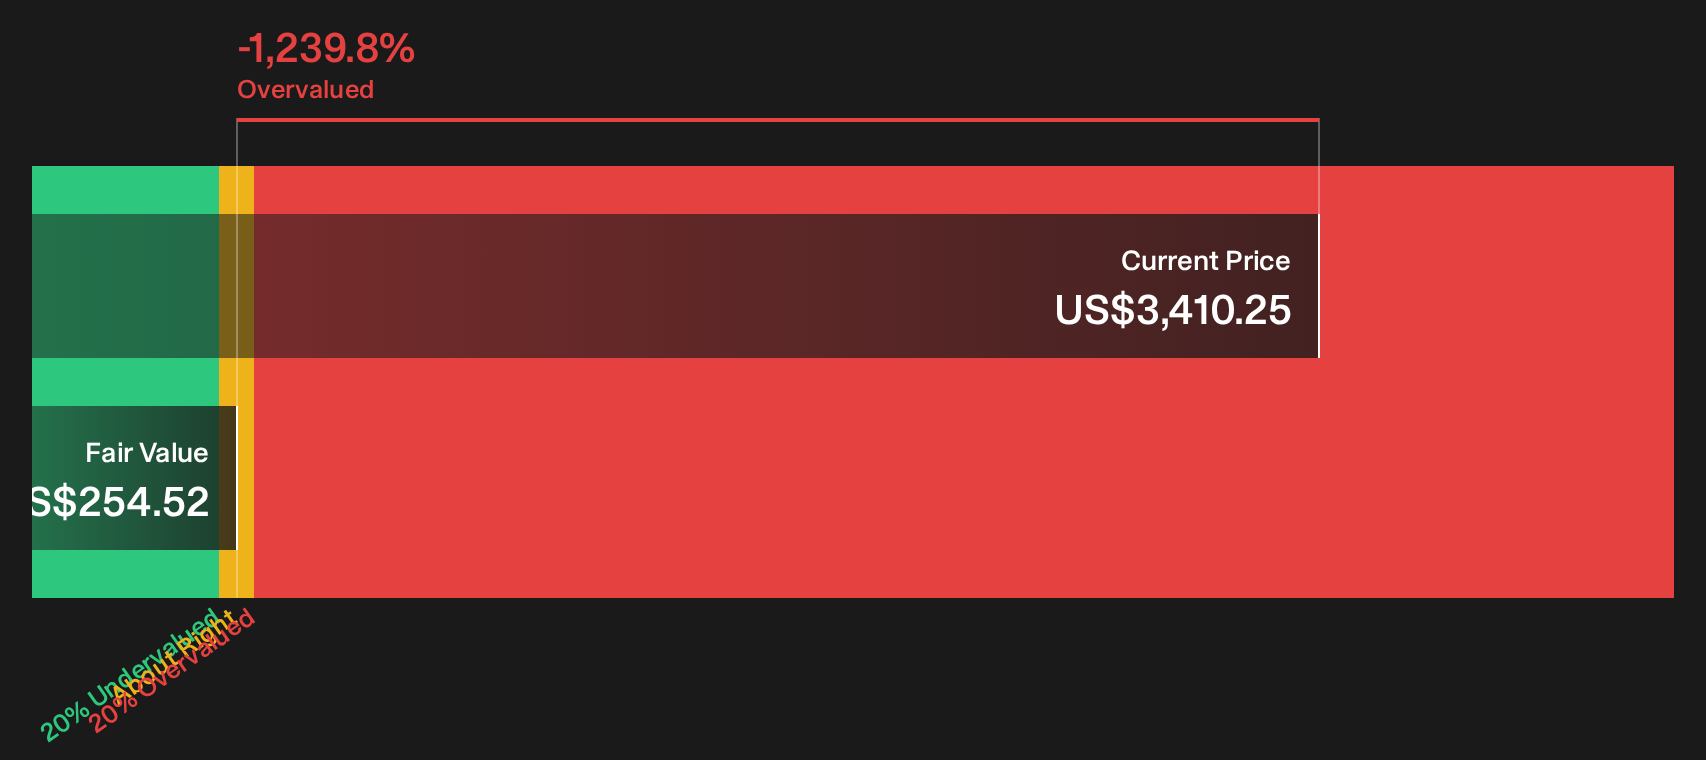
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Seaboard for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Seaboard’s mix of low earnings multiple, DCF caution and recent share price weakness sends a mixed message, so this is the moment to move fast and test the numbers yourself across both the downside risks and the potential upside rewards, then weigh how that balance fits your own risk tolerance through the 2 key rewards and 1 important warning sign
Looking for more Seaboard sized investment ideas?
If Seaboard’s mixed signals leave you wanting a wider watchlist, widen the lens and let data driven stock ideas point you to your next move.
- Target potential mispricings by scanning a curated 35 high quality undervalued stocks that line up strong fundamentals with compressed valuations.
- Prioritize financial resilience and stress test your downside risk with a focused list of solid balance sheet and fundamentals (23 results).
- Hunt for off the radar opportunities before they get crowded by reviewing a tight 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com