


EN
BioMarin Pharmaceutical (BMRN) Stock Dropped, What Is Behind Its Latest Update?
BioMarin Pharmaceutical (BMRN) just cleared the US$1b mark in Q3 2026 revenue yet trimmed its full year outlook as Voxzogo order timing and integration costs weighed on management’s updated guidance.
At a share price of US$55.66, BioMarin Pharmaceutical has seen short term sentiment soften, with a 1 day share price return down 3.10% and the 90 day share price return down 7.09%. At the same time, the 1 year total shareholder return is up 5.98% while the 3 and 5 year total shareholder returns remain deeply negative, indicating that recent earnings beats, fresh guidance and the Fabry licensing deal have not yet rebuilt longer term momentum.
Scan beyond BioMarin Pharmaceutical and compare this rare-disease story with a curated group of resilient peers using our 30 resilient stocks with low risk scores
BioMarin Pharmaceutical now trades at a steep discount to both analyst targets and some fair value estimates, after a guidance cut tied to Voxzogo timing and Fabry integration costs. Is that markdown reflecting caution, or does it highlight a potential opportunity in the current price?
Most Popular Narrative: 24% Undervalued
Framed against the last close at $55.66, the most followed valuation story on BioMarin Pharmaceutical points to a higher anchor fair value and leans on the rare-disease model as its core argument.
Business: focus on enzyme replacement therapies for ultra-rare genetic diseases, special medical knowledge, few patients/limited sales potential per drug globally (no blockbusters), established world wide distribution, complex production, orphan drugs patent protection
The Amicus Therapeutics end 2025 acquisition has understandable strategic fit and adds two US- and EU-approved rare-disease therapies, accretive after closing, commitment to deleveraging
See why 2 investors see BioMarin Pharmaceutical as 24% undervalued.
According to PKU, this rare-disease specialist screens at a fair value of $73.10 using a 9% discount rate, a 15% revenue growth assumption and a 15% profit margin, which leaves BioMarin Pharmaceutical trading at roughly a 24% discount to that narrative estimate.
The story leans on the idea that complex manufacturing, long duration treatment and orphan drug protections create meaningful barriers to entry. It also notes that the pending Amicus Therapeutics acquisition would add two approved therapies and broaden the rare-disease portfolio if it closes as planned at the end of 2025.
On that view, the valuation gap between $55.66 and $73.10 reflects a market that is pricing in execution and integration questions more heavily than this framework does, rather than assuming blockbuster-style upside that the narrative explicitly rules out.
Result: Fair Value of $73.10 (UNDERVALUED)
Still, BioMarin Pharmaceutical faces several clear pressure points, including its concentration in a narrow rare-disease portfolio and execution risk related to the planned Amicus Therapeutics integration.
Find out about the key risks to this BioMarin Pharmaceutical narrative.
Another View: BioMarin Pharmaceutical Through The P/E Lens
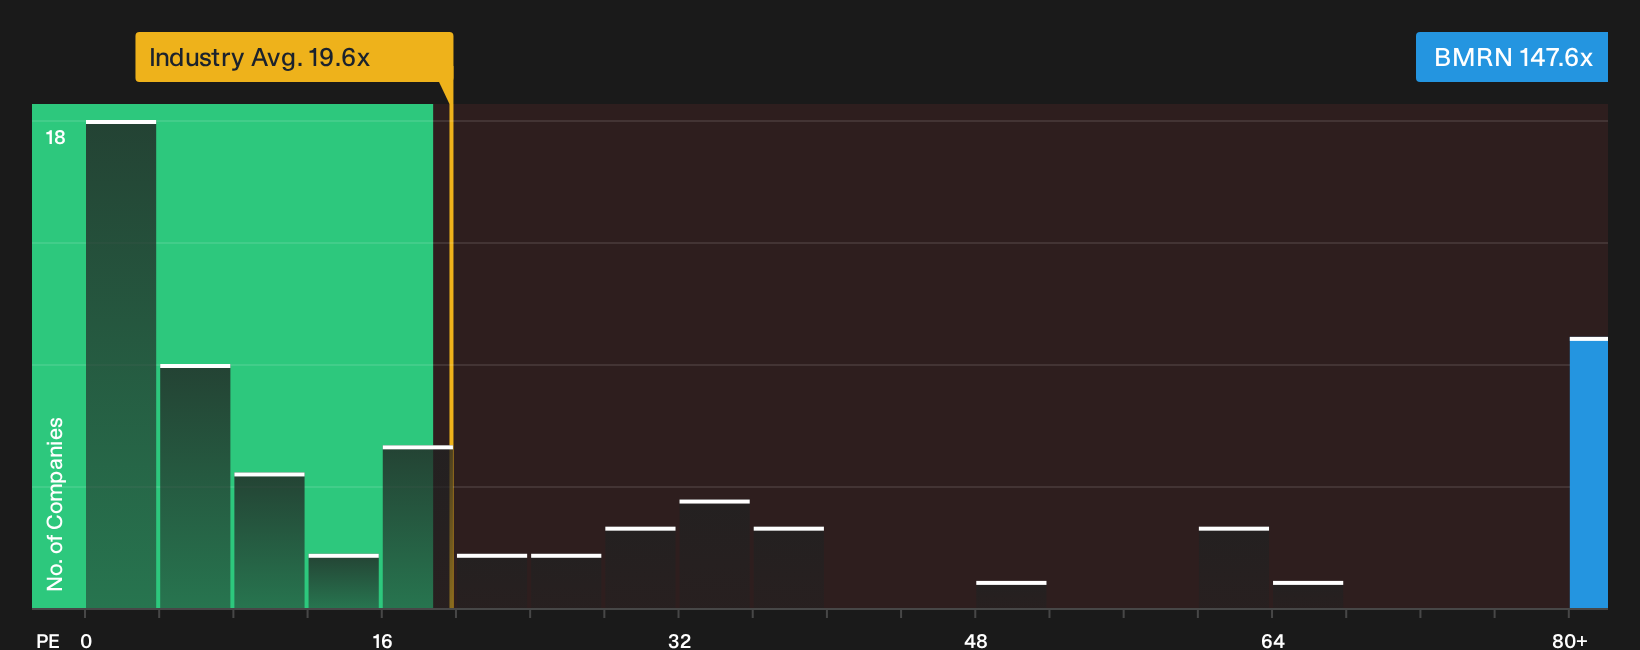
The story changes when you look at BioMarin Pharmaceutical through its P/E ratio. At 147.6x earnings, the stock trades at a very large premium to the US Biotechs average of 19.2x and to a fair ratio estimate of 38.6x, which points to meaningful valuation risk if sentiment cools.
The strong gap between current P/E, peers and the fair ratio frames a very different question for investors: Is the discount to some fair value estimates enough to offset the possibility that the market eventually gravitates closer to those lower multiples?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around BioMarin Pharmaceutical can either create hesitation or curiosity. Consider reviewing the key numbers yourself and weighing both the upside and the pressure points in the 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond BioMarin Pharmaceutical?
If BioMarin Pharmaceutical has you thinking more broadly about opportunities, do not stop here. Fresh ideas often show up where the market pays less attention.
- Hunt for quality at a discount by scanning companies that appear mispriced on fundamentals using the 35 high quality undervalued stocks.
- Target consistency in payouts and cash flow by reviewing income-focused candidates with the 4 dividend fortresses.
- Prioritize resilience and balance sheet strength by filtering for robust businesses through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com