


EN
Riley Exploration Permian (REPX) Draws Earnings Focus, Is The Pullback A Valuation Opportunity?
Investor attention around Riley Exploration Permian (REPX) is centering on its November 4 earnings report, with consensus forecasts pointing to quarterly EPS of $2.23 and revenue projected at $483.86 million.
Recent trading shows how expectations are feeding into Riley Exploration Permian’s valuation story. The share price has pulled back 10.46% over the past week and slipped 1.53% in the last session, yet it still carries a 30 day share price return of 11.23% and a 90 day gain of 42.21%. The 1 year total shareholder return of 94.63% signals strong momentum that shorter term volatility has not fully disrupted.
Scan how the market is pricing earnings momentum stories like Riley Exploration Permian by checking our curated list of 35 high quality undervalued stocks that combine cash generation with balance sheet strength.
Riley Exploration Permian now trades at a discount to analyst targets after a sharp pullback, even with a strong 1 year run behind it. Is that price gap a sign of caution, or does it represent an opportunity?
Most Popular Narrative: 2% Overvalued
The most followed narrative on Riley Exploration Permian puts fair value at $46 per share, just below the last close at $46.93. That small gap leaves the focus squarely on whether its midstream and power investments can keep earnings quality on track.
The shift in development activity toward New Mexico, combined with infrastructure projects such as expanded saltwater disposal and oil gathering systems, is expected to support higher oil volumes over several years and feed through to revenue. Completion of the high pressure gas trunk line and related midstream infrastructure in Texas and New Mexico is expected to relieve current constraints, allow more Riley Exploration Permian volumes to flow, and create potential third party throughput that could add to future earnings.
See why 20 investors see Riley Exploration Permian as 2% overvalued.
Result: Fair Value of $46 (OVERVALUED)
Still, the Riley Exploration Permian narrative can unravel if heavy midstream and power spending delays free cash flow or if hedge losses again erode reported earnings.
Find out about the key risks to this Riley Exploration Permian narrative.
Another View: Riley Exploration Permian Through The P/E Lens
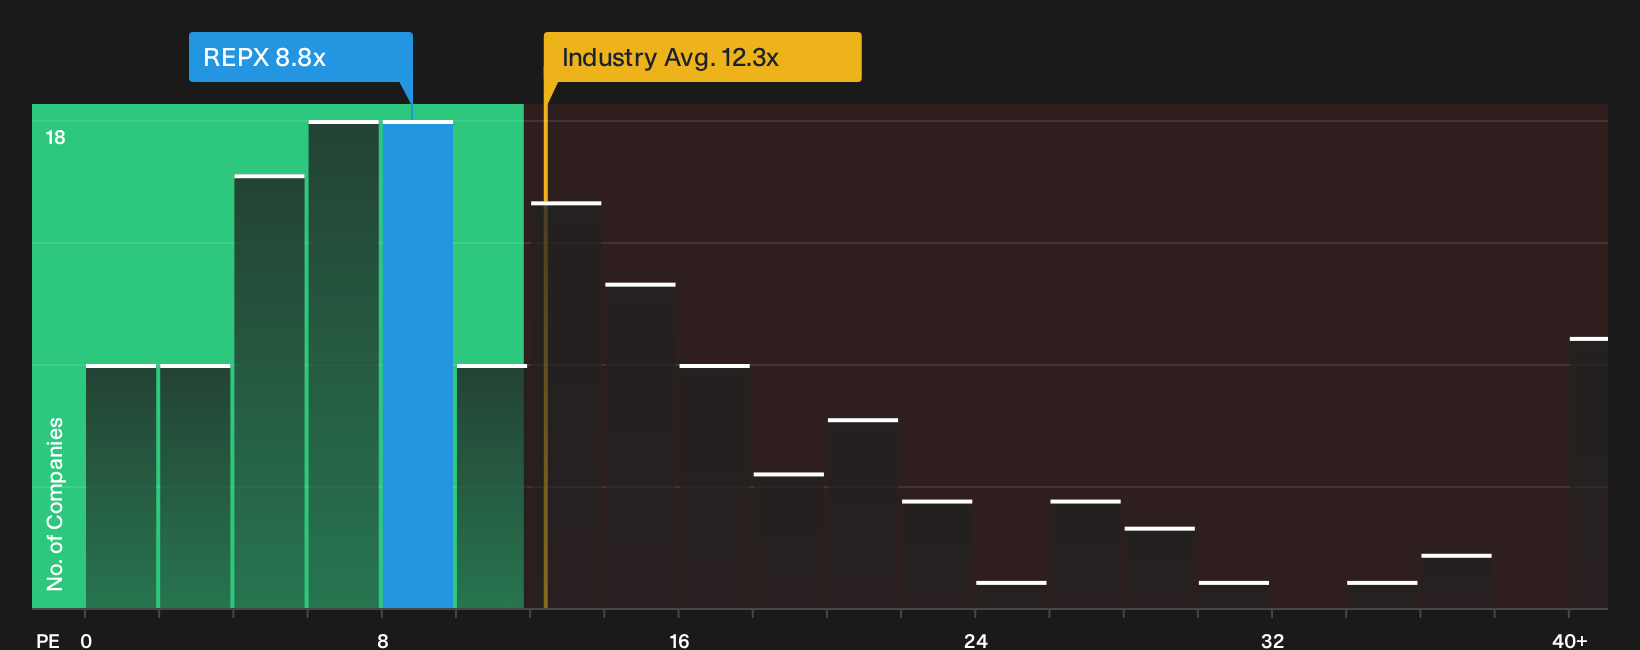
The first narrative pegs Riley Exploration Permian as about 2% overvalued at $46 per share. A different lens tells a softer story. On a P/E of 8.8x, the shares trade below US Oil and Gas at 12.6x and under the peer group at 9.4x. The P/E is also well under a fair ratio estimate of 14.7x, which points to a wide gap between what the current market is paying and where that multiple could move over time. Is the crowd correctly discounting earnings quality and commodity risk, or leaving mispriced cash flows on the table?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Riley Exploration Permian feels split, that is exactly the point. Check the full mix of concerns and bright spots for yourself with 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Riley Exploration Permian?
If Riley Exploration Permian has your attention, do not stop here. Broaden your watchlist with a few focused sets of ideas that line up with your own risk and income preferences.
- Target potential outliers at the smaller end of the market and scan 10 elite penny stocks with strong financials that already pair story potential with real financial substance.
- Prioritise resilience by working through a list of solid balance sheet and fundamentals (23 results) so you are not caught off guard by weak cash buffers or heavy leverage.
- Put dependable income on your radar by running through a set of 4 dividend fortresses that aim to combine higher yields with sturdier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com