


EN
Robert Half (RHI) Posts Stronger Guidance, Is The Stock Above Fair Value?
Robert Half (RHI) is back in focus after its latest quarterly update showed year-over-year gains in net income and earnings per share, along with fourth quarter guidance pointing to higher revenue and stronger profitability.
That backdrop has fed straight into the chart. Robert Half’s share price has climbed, with a 30 day share price return of 21.07% and a year-to-date share price gain of 59.95%. However, the 5 year total shareholder return is still down 54.56%, so recent momentum is building off a weak longer term base.
Scan Robert Half alongside a curated 35 high quality undervalued stocks that share improving earnings momentum and could be setting up for their own rerating on the next round of results.
After a 60% year to date surge and a sharply weaker 5 year record, Robert Half now sits at a crossroads for investors. Does the current valuation still stack up for fresh buyers?
Most Popular Narrative: 15% Overvalued
Against the last close at $43.73, the most followed narrative pegs Robert Half’s fair value at about $37.89, so the share price sits above that reference point even as earnings expectations improve.
Protiviti’s technology consulting business, now roughly one third of segment revenue and delivering record quarterly revenue, is benefiting from client demand for platform and technology modernization, data, cyber and IT infrastructure work. This can help offset weaker risk and compliance work and support segment revenue and operating margin improvement over time.
See why 19 investors see Robert Half as 15% overvalued.
Result: Fair Value of $37.89 (OVERVALUED)
Still, the bullish recovery story around Robert Half can break if Protiviti’s weaker margins persist or if contract staffing volumes keep sliding instead of stabilising.
Find out about the key risks to this Robert Half narrative.
Another View: Cash Flows Paint A Different Picture
Analyst targets put Robert Half at a fair value of $37.89, which screens as about 15% above that reference level at $43.73. The SWS DCF model points in the opposite direction, with an estimated future cash flow value near $76.22 that implies the shares trade at roughly a 43% discount. Which lens do you trust more when the signals clash this sharply?
Look into how the SWS DCF model arrives at its fair value.
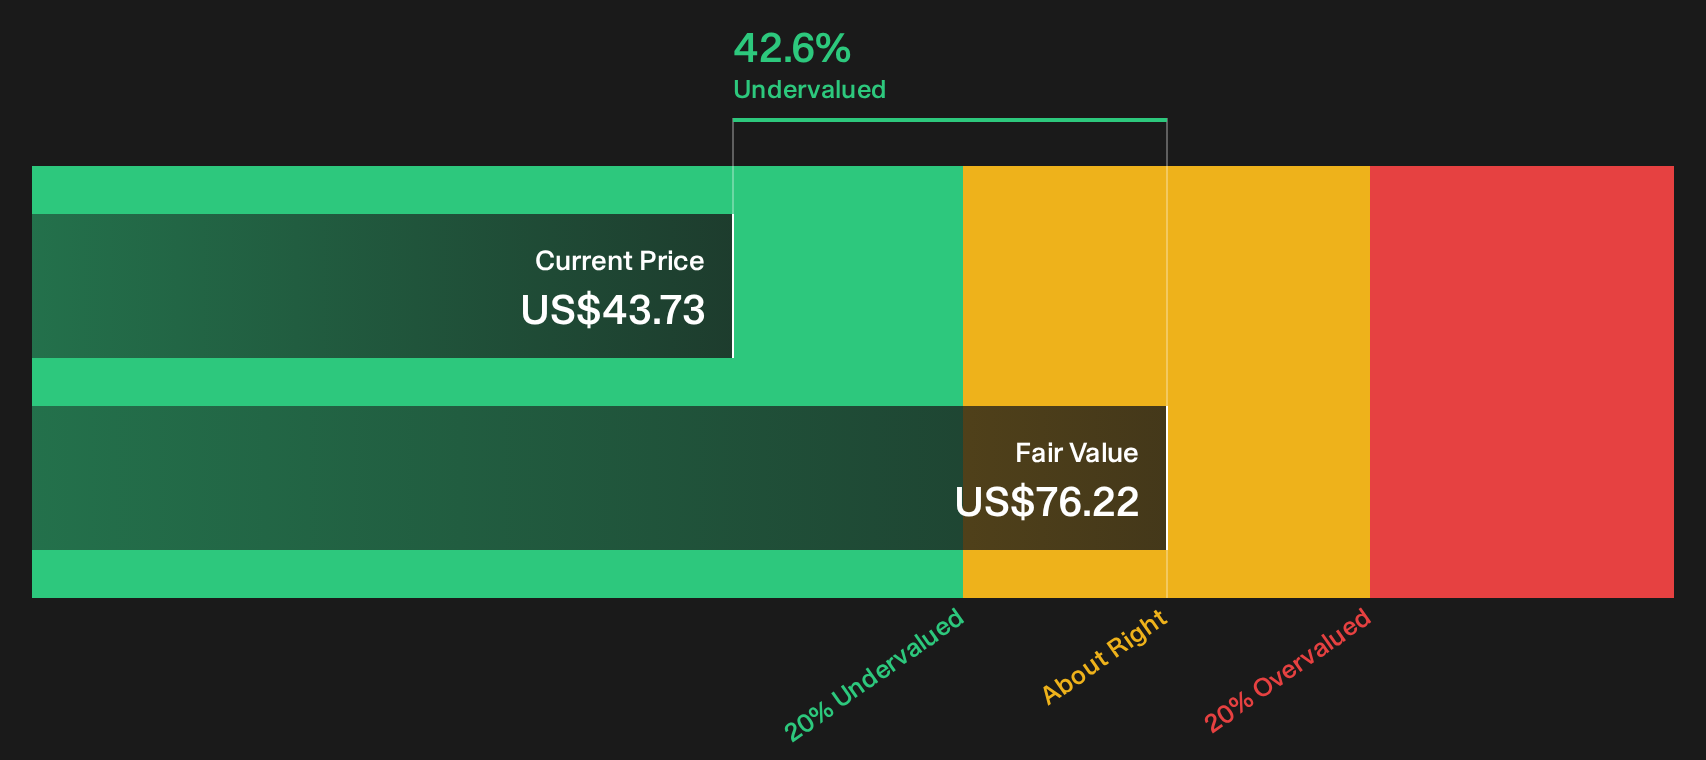
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Robert Half for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Robert Half’s value story today. Act while the data is fresh, and pressure test the upside and downside with 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Robert Half?
If Robert Half has sharpened your focus, do not stop there. Broaden your watchlist with other clear setups that fit your risk tolerance and return goals.
- Target reliable income and reduce guesswork by reviewing companies that qualify as 4 dividend fortresses for consistent cash returns.
- Hunt for quality at a sensible price by scanning through a list of solid balance sheet and fundamentals (23 results) that can better withstand tough conditions.
- Spot future leaders early by checking a 19 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com