


EN
Southwest Airlines (LUV) Stock May Still Be A Bargain As Profit Outlook Falls
Southwest Airlines has seen its stock climb sharply in recent years, and the latest profit reset alongside higher fuel costs puts a fresh spotlight on whether that share price still lines up with what the airline actually earns. With investors weighing record revenue against rising expenses, the question now is how well the current valuation reflects the company’s earnings power.
- Over the past 3 years the stock has returned 96.6%, which puts real weight on whether the current valuation is being driven by earnings strength or by optimism that may not be fully tied to profits.
- The cut to the 2026 profit outlook in response to higher jet fuel prices suggests that future margins and cash generation may be more sensitive to cost swings than the recent run in the share price might imply.
- The analysts covering Southwest Airlines have run their own numbers. See what analysts think Southwest Airlines's shares could be worth.
The issue now is whether Southwest Airlines' current price is justified by its earnings when set against the Fair Ratio benchmark.
To test whether Southwest Airlines' earnings-based valuation question also shows up elsewhere, you can run the same filter set across 35 high quality undervalued stocks
Is Southwest Airlines Still Cheap on Earnings?
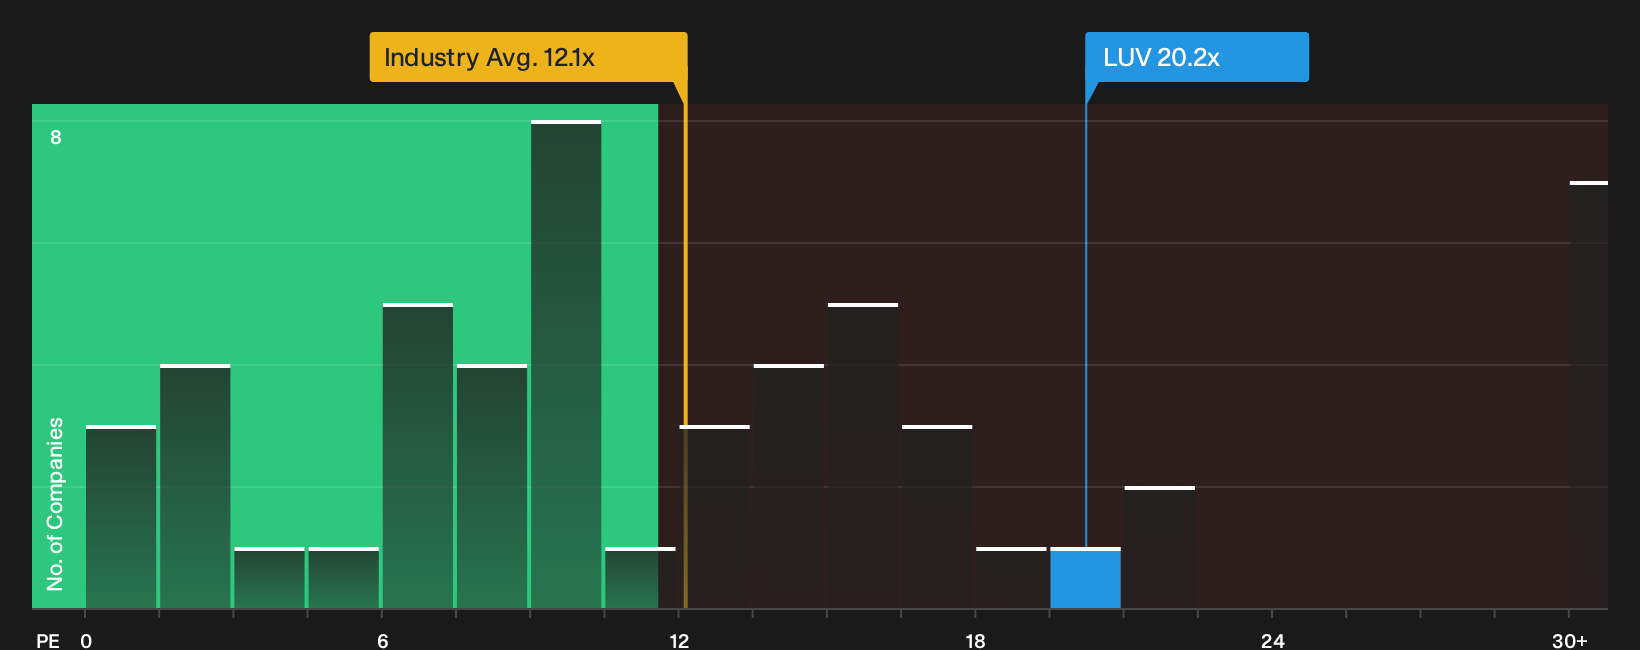
The P/E ratio works well for Southwest Airlines because management still guides investors using earnings per share targets. On this lens, the stock trades on roughly 20.2x earnings, which is above the airlines sector average of about 12.1x and also higher than the peer group on roughly 10.6x.
Because the Fair Ratio framework adjusts for Southwest Airlines' own growth profile, profitability and risk, it points to a higher P/E than the market currently assigns, so the shares screen as undervalued on this model. Despite the cut to the 2026 profit outlook in response to rising jet fuel costs, the current multiple still sits below what that tailored benchmark suggests might be justified by the business economics. Explore the numbers behind Southwest Airlines's P/E valuation.
The Southwest Airlines Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Southwest Airlines pick up where this valuation puzzle leaves off and spell out the earnings, margin and growth paths that would need to line up for the stock to look meaningfully higher or lower than today’s price, using community views on the company’s future. Rather than relying on a single P/E or model output, each narrative lays out the assumptions behind its estimate of fair value so you can compare them with reported results as they arrive.
Community views on Southwest Airlines are split between those who see more value in the loyalty and cost story and those who think fuel and execution risks already sit in the quote.
Bull case: 12% undervalued
"Rapid Rewards loyalty engagement, including nearly 100 million members, higher tier qualification activity, and stronger co branded card acquisitions with Chase, supports further growth in high margin loyalty and card economics that can add to revenue and EBIT over time…"
Discover why this Narrative puts Southwest Airlines at 12% undervalued.
Bear case: 28% overvalued
"Although new seating products and bag fees are expected to add more than US$2b of EBIT across 2026 and 2027, jet fuel at around 20 year highs and an almost US$900m year over year fuel expense increase risk absorbing much of that contribution and keeping net margins under pressure…"
Explore why this Narrative puts Southwest Airlines at 28% overvalued.
One key Southwest Airlines question still hangs over the current price
Today's P/E debate only goes so far without checking where professional forecasts think Southwest Airlines might be a few years from now, and how that profile lines up with the valuation you see today. Explore where analysts expect Southwest Airlines to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com