


EN
Hayward Holdings (HAYW) Earnings Beat And Raised Outlook Put Fair Value Back In Focus
Hayward Holdings (HAYW) just posted third quarter earnings that showed higher basic and diluted EPS from continuing operations versus last year, raised its 2026 net sales outlook, and attracted fresh institutional interest.
Despite a small 1 day share price decline, Hayward Holdings has rallied sharply in the past month, with a 7 day share price return of 26.63% and a 30 day gain of 33.06%. This suggests momentum has picked up around the earnings beat, the raised 2026 net sales guidance, and the new position taken by FPA Queens Road Small Cap Value Fund. That shorter term strength contrasts with a more modest year to date share price return of 4.63% and a 1 year total shareholder return of 1.91%. Longer term holders have seen a 3 year total shareholder return of 54.06%, but a 5 year total shareholder return that is down 33.97%. This frames the current US$16.50 share price against a history of both strong recovery periods and earlier weakness.
Scan how Hayward Holdings compares to other equipment makers showing renewed earnings momentum by running the curated 19 high quality undiscovered gems that share solid fundamentals and fresh investor interest.
Bulls see Hayward Holdings as an oligopoly player on 15x earnings after an earnings beat; bears see a cyclical pool supplier catching a hot streak. Which story do the current valuation markers really support?
Most Popular Narrative: 6% Undervalued
On the most followed narrative, Hayward Holdings screens as modestly undervalued, with a fair value of $17.50 against a last close of $16.50. This puts the recent rally in the context of expectations for steady execution rather than a spike of pure sentiment.
The numbers on growth guidance, record gross margins, and active share repurchases imply that the current share price treats Hayward Holdings as a cautious pool equipment stock rather than fully valuing a business that this narrative presents as undervalued and bullish.
See why 1 investors see Hayward Holdings as 6% undervalued.
Result: Fair Value of $17.50 (UNDERVALUED)
Still, the Hayward Holdings story can change quickly if housing related pool construction stays weak or if the recent securities settlement keeps valuation multiples under pressure.
Find out about the key risks to this Hayward Holdings narrative.
Another View: Hayward Holdings On Earnings Multiples
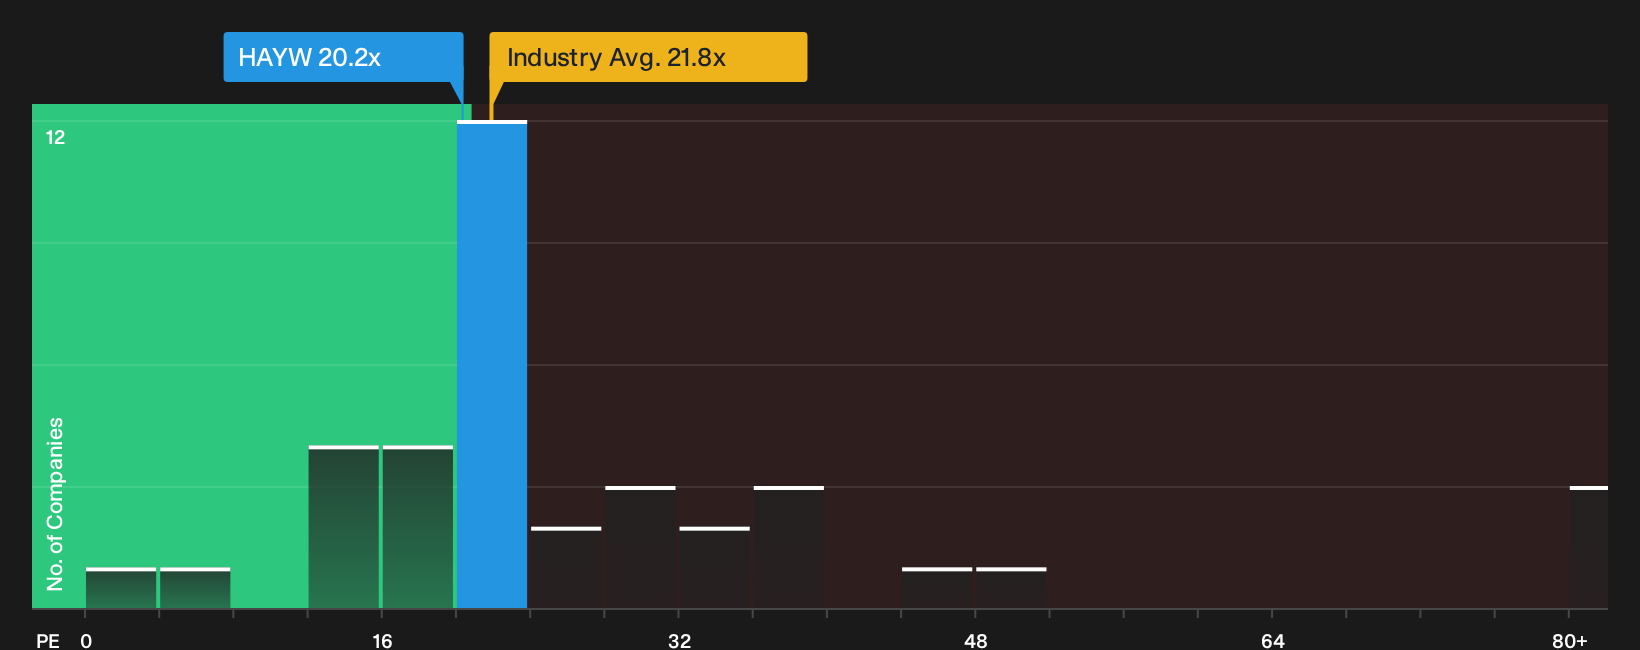
The most followed story casts Hayward Holdings as modestly undervalued, yet its current P/E of 20.2x sits slightly above a fair ratio of 19.7x. That gap points to a small valuation premium, even though the multiple is below peers at 24.2x and the wider US Building group at 21.3x. Is that premium a warning sign, or is it simply the price of a cleaner earnings profile?
To see how this pricing gap lines up with quality, growth and peer comparisons in more detail, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and caution around Hayward Holdings leaves you undecided, move quickly to review the numbers yourself and stress test the bullish points investors are focused on using 3 key rewards.
Looking For More Investment Ideas Beyond Hayward Holdings?
If Hayward Holdings has sharpened your focus, do not stop with a single opportunity. Broaden your watchlist and pressure test your thesis against other high quality ideas.
- Target resilient returns by scanning companies with robust finances and controlled risk profiles using the 30 resilient stocks with low risk scores.
- Focus on quality at a reasonable price by checking companies that appear attractively priced on fundamentals through the 35 high quality undervalued stocks.
- Strengthen your income playbook by lining up potential high yield payers and reviewing their durability with the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com