


EN
Ormat Technologies (ORA) Stock Looks Fully Priced For Its Current Earnings
Ormat Technologies has delivered a solid 48.8% share price gain over the past three years, even though the year to date picture has been weaker, which puts a spotlight on what investors are really paying for its earnings today. With the stock last closing at US$94.19, the key issue now is how that price lines up with the profits the business is currently generating.
- That 48.8% return over three years puts meaningful weight on the question of whether Ormat Technologies' earnings profile can underpin the current share price.
- The group relies on long term power contracts and capital intensive projects, so the timing and stability of earnings may play a big role in how justified today's valuation looks.
- The analysts covering Ormat Technologies have run their own numbers. See what analysts think Ormat Technologies's shares could be worth.
For investors, the debate is whether Ormat Technologies' current market price is appropriately supported by the earnings it is generating right now.
If you want a broader feel for how other companies are currently being priced on their fundamentals, a focused stock screen such as 35 high quality undervalued stocks can be a useful next step in your research.
Has Ormat Technologies Run Too Far on Earnings?
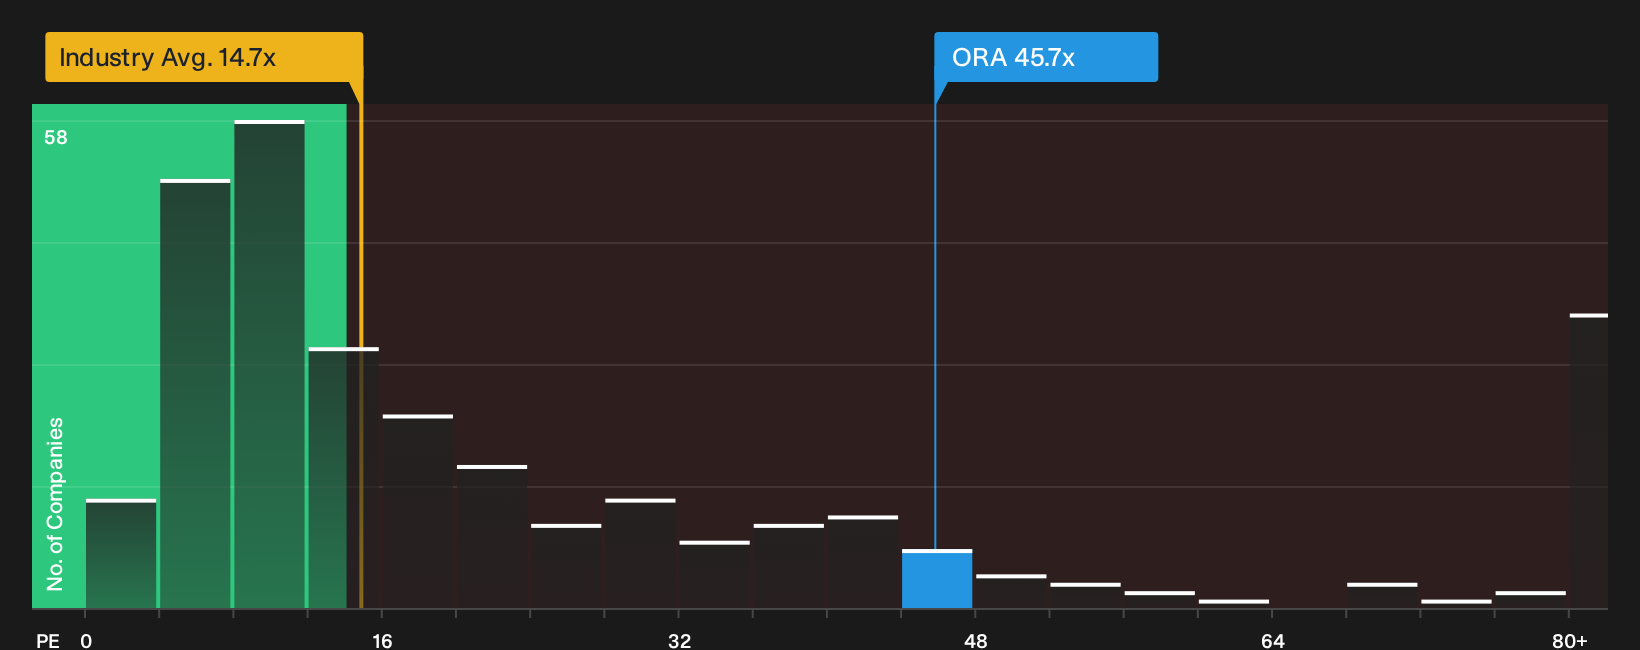
The P/E ratio is a useful lens for Ormat Technologies because the business reports positive earnings that investors can directly compare to its share price. At around 45.7x earnings, the stock trades well above the average for the wider Renewable Energy group, which sits near 14.7x, and also above a peer group closer to 29.2x. That gap suggests the market is placing a higher value on each dollar of Ormat Technologies' profit than it does for many similar utilities and power producers.
A tailored fair value model that weighs Ormat Technologies' growth profile, profitability, size and risk points to a lower P/E as more typical for this kind of earnings stream, so the current multiple screens as overvalued against that yardstick. For anyone researching the shares, the key question is whether the company's long term contracts, capital spending plans and earnings mix justify paying such a premium over both sector norms and this more customised benchmark. Explore the numbers behind Ormat Technologies's P/E valuation.
The Ormat Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E debate for Ormat Technologies leaves off by explaining which long term assumptions on growth, profitability and earnings would need to hold for the share price to sit meaningfully above or below where it trades today. Each one frames its estimate of fair value as a thesis about the business that you can watch over time rather than a one off snapshot, all housed on Simply Wall St's Community page.
One of the top community narratives on Ormat Technologies: 25% undervalued
Ormat Technologies’ shift from a pure play geothermal operator to a broader renewable and storage platform is reflected in energy storage and product segments that now contribute around 25% of revenue…
Discover why this Narrative puts Ormat Technologies at 25% undervalued.
One more Ormat Technologies check that belongs next to the valuation work
Price tags only tell part of the story, and Ormat Technologies also has a set of risk signals that research tools have already picked up, which some investors will want to weigh before going further. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com