


EN
Is Louisiana-Pacific (LPX) Stock Too Stretched To Look Reasonable?
Louisiana-Pacific has delivered a 30.8% gain over the past 3 years, yet the stock is still down year to date, which raises a straightforward question for investors. Is the current US$73.79 share price well supported by the earnings power of the business, or has the market moved ahead of what the company is actually generating?
- The 30.8% return over 3 years puts real weight on whether Louisiana-Pacific's current earnings can carry that performance or if expectations have stretched too far.
- The business leans heavily on earnings from building products tied to housing and construction cycles, so any shift in profitability or pricing power can quickly change how robust those profits look relative to the share price.
- The analysts covering Louisiana-Pacific have run their own numbers. See what analysts think Louisiana-Pacific's shares could be worth.
The issue now is whether Louisiana-Pacific's current earnings, and what investors reasonably expect from them, are enough to justify where the stock trades today.
For a broader watchlist alongside Louisiana-Pacific while you weigh whether today's earnings support the US$73.79 price, start with a focused screen of 35 high quality undervalued stocks.
Does Louisiana-Pacific Look Pricey on Earnings?
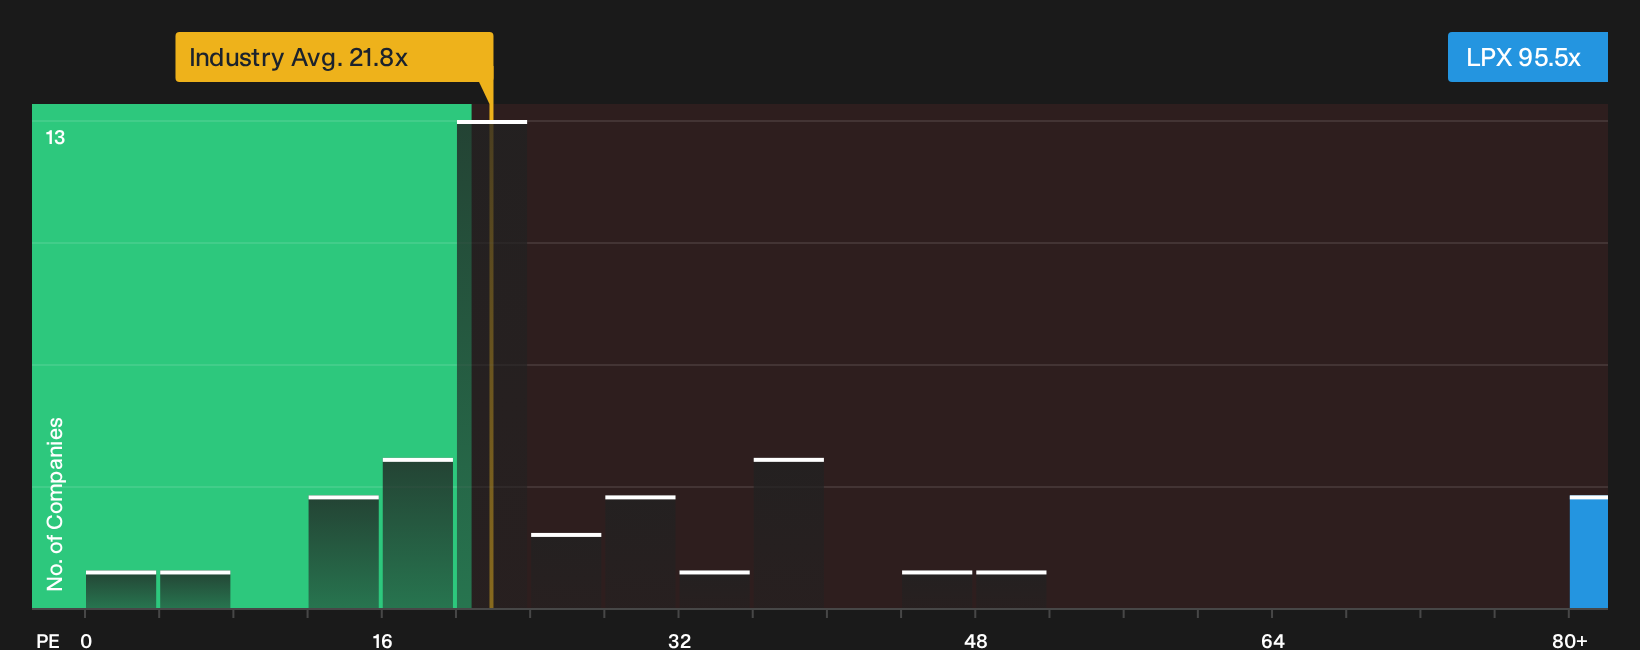
The P/E ratio suits Louisiana-Pacific because earnings remain a core lens for how investors judge a building products business that is closely tied to housing demand. On this measure, the stock trades on about 95.5x earnings, which is far above the broader building industry average of roughly 21.8x and above a peer group closer to 26.7x. That gap indicates that buyers are paying a steep price today for each dollar of reported profit.
The fair-value model that blends in Louisiana-Pacific's growth profile, profitability, size and risk points to a materially lower P/E as a more typical level for the business. As a result, the current multiple screens as overvalued against that tailored yardstick. For anyone considering the shares, the key question is whether Louisiana-Pacific's earnings quality and future profit potential justify paying such a premium multiple relative to both its sector and this fair-value guide. Explore the numbers behind Louisiana-Pacific's P/E valuation.
The Louisiana-Pacific Narrative: What Would Justify Today's Price?
Simply Wall St Narratives give you a way to turn Louisiana-Pacific's valuation puzzle into clear scenarios that spell out what would need to happen to growth, profitability and earnings for the current share price to look either conservative or stretched, all hosted on the stock's Community page. Each scenario links a valuation view to a specific path for Louisiana-Pacific's revenues, margins and key risks, which you can come back to as fresh results and filings arrive.
Community views on Louisiana-Pacific split around how much weight to put on SmartSide Siding’s potential versus the drag from OSB and cyclical housing exposure.
Bull case: 16% undervalued
"Accelerated adoption of LP's SmartSide and ExpertFinish trim and siding products, supported by SmartSide volume and revenue compound growth that has outpaced single family housing starts over the past 15 years..."
Discover why this Narrative puts Louisiana-Pacific at 16% undervalued.
Bear case: 6% overvalued
"The recent reduction of full-year 2026 Siding EBITDA guidance by about $50 million, largely due to weaker expected volumes, points to a risk that share gains do not fully offset softer end-market demand..."
Explore why this Narrative puts Louisiana-Pacific at 6% overvalued.
One more Louisiana-Pacific check that belongs beside the earnings and P/E story
Before you treat Louisiana-Pacific's valuation as the whole picture, it is worth looking at the specific risk indicators our research has picked up and weighing how they sit with your own thesis. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com