


EN
Is Casella Waste Systems (CWST) Cheap After Jana's Push And Earnings Optimism?
Activist investor Jana Partners has stepped into Casella Waste Systems (CWST), pressing for higher profitability, tighter capital use, and executive pay tied more closely to shareholder outcomes over the next few years.
Recent trading shows momentum picking up in Casella Waste Systems, with a 7 day share price return of 8.7% and a 30 day gain of 15.36%, even though the year to date share price return is slightly down 2.45%.
Compare Jana's push at Casella Waste Systems with other businesses where activist pressure, earnings revisions, or valuation gaps are already in play by scanning our hand picked list of 19 high quality undiscovered gems.
For Casella Waste Systems, that sharp rebound could signal confidence in the underlying operations rather than just a mood swing in the market. Does the current valuation still line up with those rising expectations?
Most Popular Narrative: 10% Undervalued
On the latest Simply Wall St narrative, Casella Waste Systems has a fair value estimate of $106.50 versus a last close of $96.23, which puts activist pressure on top of an already value focused debate.
Infrastructure investments in automation and technology, including the deployment of 40 automated trucks expected to deliver more than US$5 million of savings in 2026, AI enabled in cab safety systems and new billing platforms, are intended to reduce operating and G&A costs over the next several years. These initiatives can support EBITDA margin recovery and improved net income.
See why 3 investors see Casella Waste Systems as 10% undervalued.
Result: Fair Value of $106.50 (UNDERVALUED)
Still, Casella Waste Systems faces real pressure if acquisition integrations lag or if higher diesel and other operating costs continue to squeeze already thin net margins.
Find out about the key risks to this Casella Waste Systems narrative.
Another View: What Casella Waste Systems’ Price Tag Signals
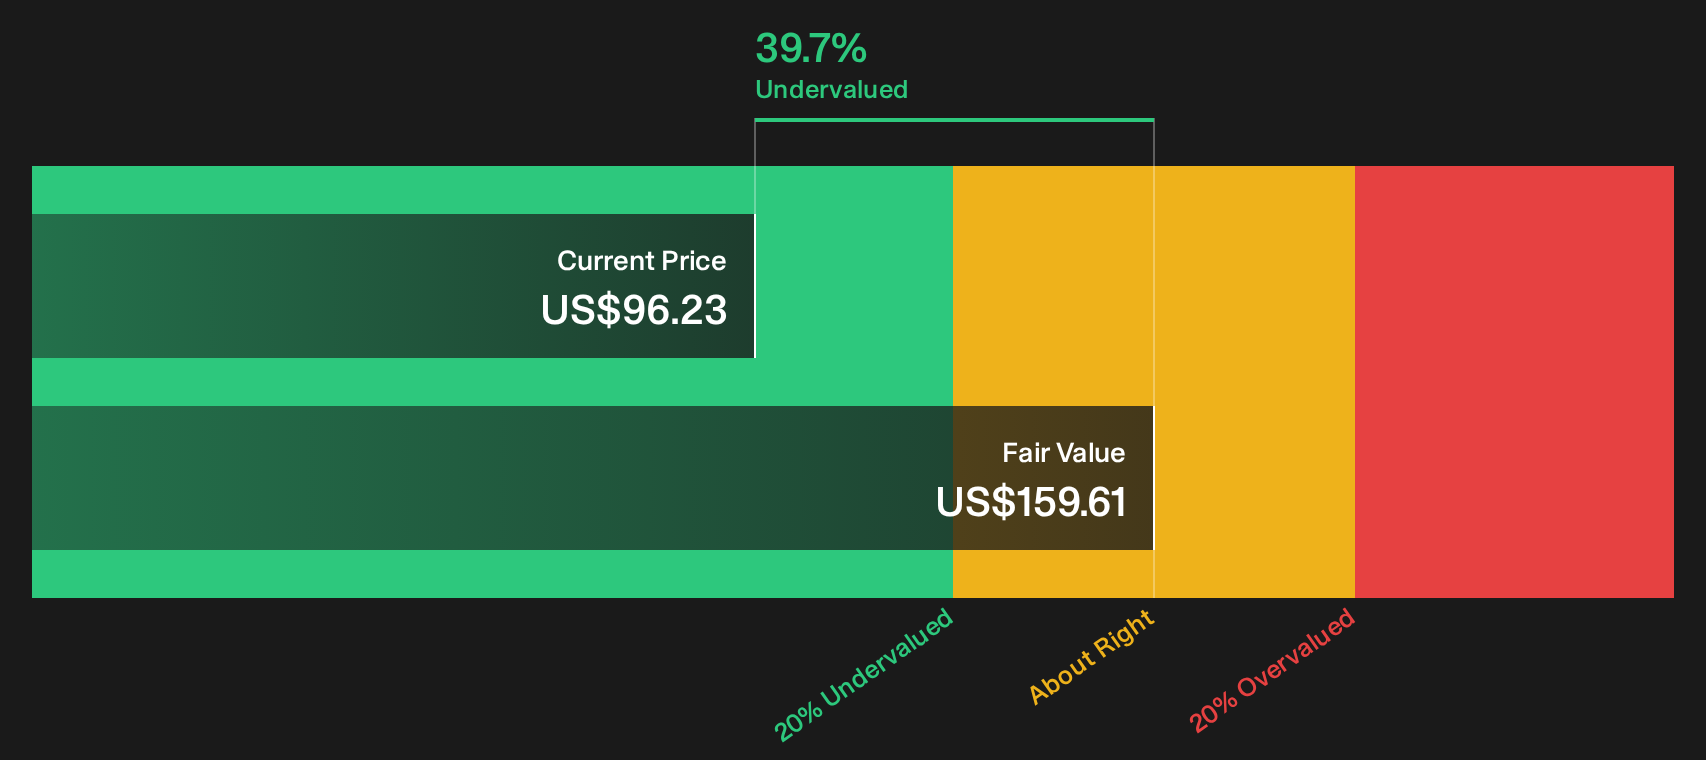
Casella Waste Systems screens as undervalued on future cash flows, with the SWS DCF model suggesting a fair value of $159.61 compared with the current $96.23 share price. That is a wide gap for a business with slim 0.3% net margins and low 0.4% Return on Equity. How comfortable are you with that spread?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Uneasy about how mixed the Casella Waste Systems picture feels after all this data and debate? Act promptly, review the key risks and potential upsides yourself, and ground your own thesis in the 2 key rewards and 4 important warning signs.
Looking for more Casella Waste Systems sized ideas?
If you stop at Casella Waste Systems, you risk missing other opportunities that fit your style. Put a few minutes into the screener and widen your field.
- Target dependable compounding potential by reviewing companies with strong income streams in the 4 dividend fortresses.
- Hunt for quality at a discount so you are not overpaying for fundamentals with the 35 high quality undervalued stocks.
- Prioritise resilience first and focus on stability in tougher markets by checking the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com