


EN
Intellia Therapeutics (NTLA) Could Be 49% Undervalued After New Phase 1 Data Plans
Intellia Therapeutics (NTLA) is back in focus after the company said it will share fresh Phase 1 data on its CRISPR-based candidate nexiguran ziclumeran at two medical meetings this month.
At a share price of US$11.86, Intellia Therapeutics has had a mixed run, with the 1 day share price return rising 1.72% and the 90 day share price return up 8.11%, while the 1 year total shareholder return declined 2.79% and the 3 year total shareholder return fell 59.78%. As a result, interest in the upcoming clinical data could be read as a test of whether this recent momentum can rebuild confidence after years of heavy losses for longer term holders.
Compare Intellia Therapeutics with other high potential gene editing and biotech plays using our hand picked 34 healthcare AI stocks for fresh ideas around the same medical breakthrough theme.
After a modest rebound and a long history of heavy drawdowns, the real puzzle around Intellia Therapeutics is simple. Has the market already priced in the CRISPR promise, or is most of the potential still ahead of the stock as the valuation stands today?
Most Popular Narrative: 49% Undervalued
On the most followed view, Intellia Therapeutics screens as materially cheaper than a fair value of $23.11 when set against the last close at $11.86. That gap rests on a very specific belief about how its one time CRISPR drugs could translate into future cash flows.
Real world and long term clinical data for lonvo z in HAE, including rapid and durable attack control from a one time infusion and patients out to 3 to 4 years without returning to long term prophylaxis, supports the argument for premium, durability based pricing that could improve gross margins once revenue starts to be recognized.
See why 89 investors see Intellia Therapeutics as 49% undervalued.
Result: Fair Value of $23.11 (UNDERVALUED)
Still, the Intellia Therapeutics story can change quickly if late stage safety findings dent confidence in lonvo z or nex z, or if payers push back hard on high upfront pricing.
Find out about the key risks to this Intellia Therapeutics narrative.
Another View On Intellia Therapeutics: Rich On Sales
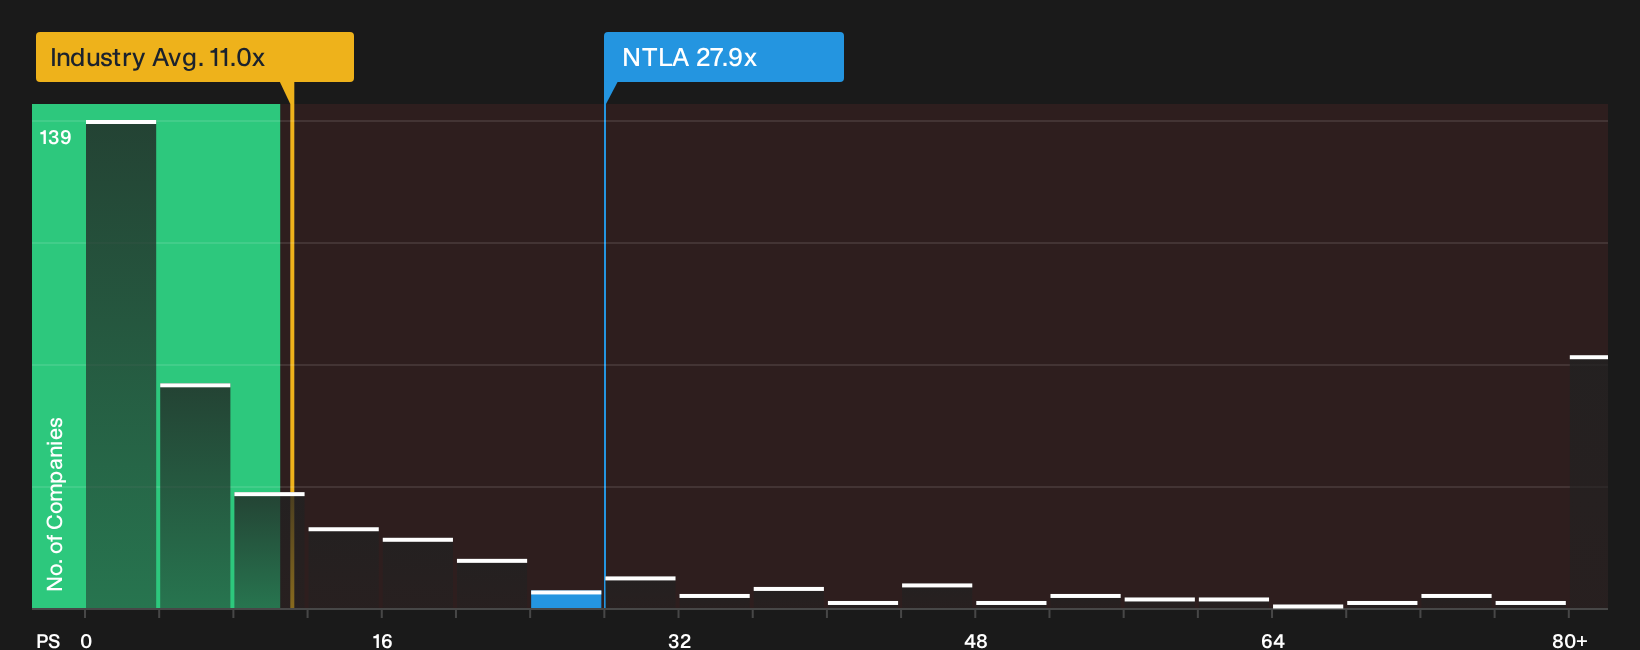
Step away from fair value models and look at what you actually pay for each dollar of Intellia Therapeutics revenue. On a P/S of 27.9x, the stock trades well above the US Biotechs industry at 11x and peers at 11.2x, and far above a fair ratio of 0.1x. That gap points to meaningful valuation risk if expectations around CRISPR pricing or uptake reset.
See what the numbers say about this price in our valuation breakdown, then judge whether that premium fits your own risk tolerance and time horizon. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Intellia Therapeutics leaves you on the fence, move quickly and inspect the full picture yourself. To weigh the upside against the weak spots side by side, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Intellia Therapeutics?
Do not stop your research at Intellia Therapeutics when there are focused lists built to surface very different kinds of opportunities in seconds.
- Target potential mispricing by scanning a curated pool of quality stocks that screen as attractively valued using the 35 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by filtering companies through the 30 resilient stocks with low risk scores.
- Hunt for future leaders early by working through the 19 high quality undiscovered gems before they land on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com