


EN
Raised Guidance Could Be A Big Test For UMH Properties Stock (UMH)
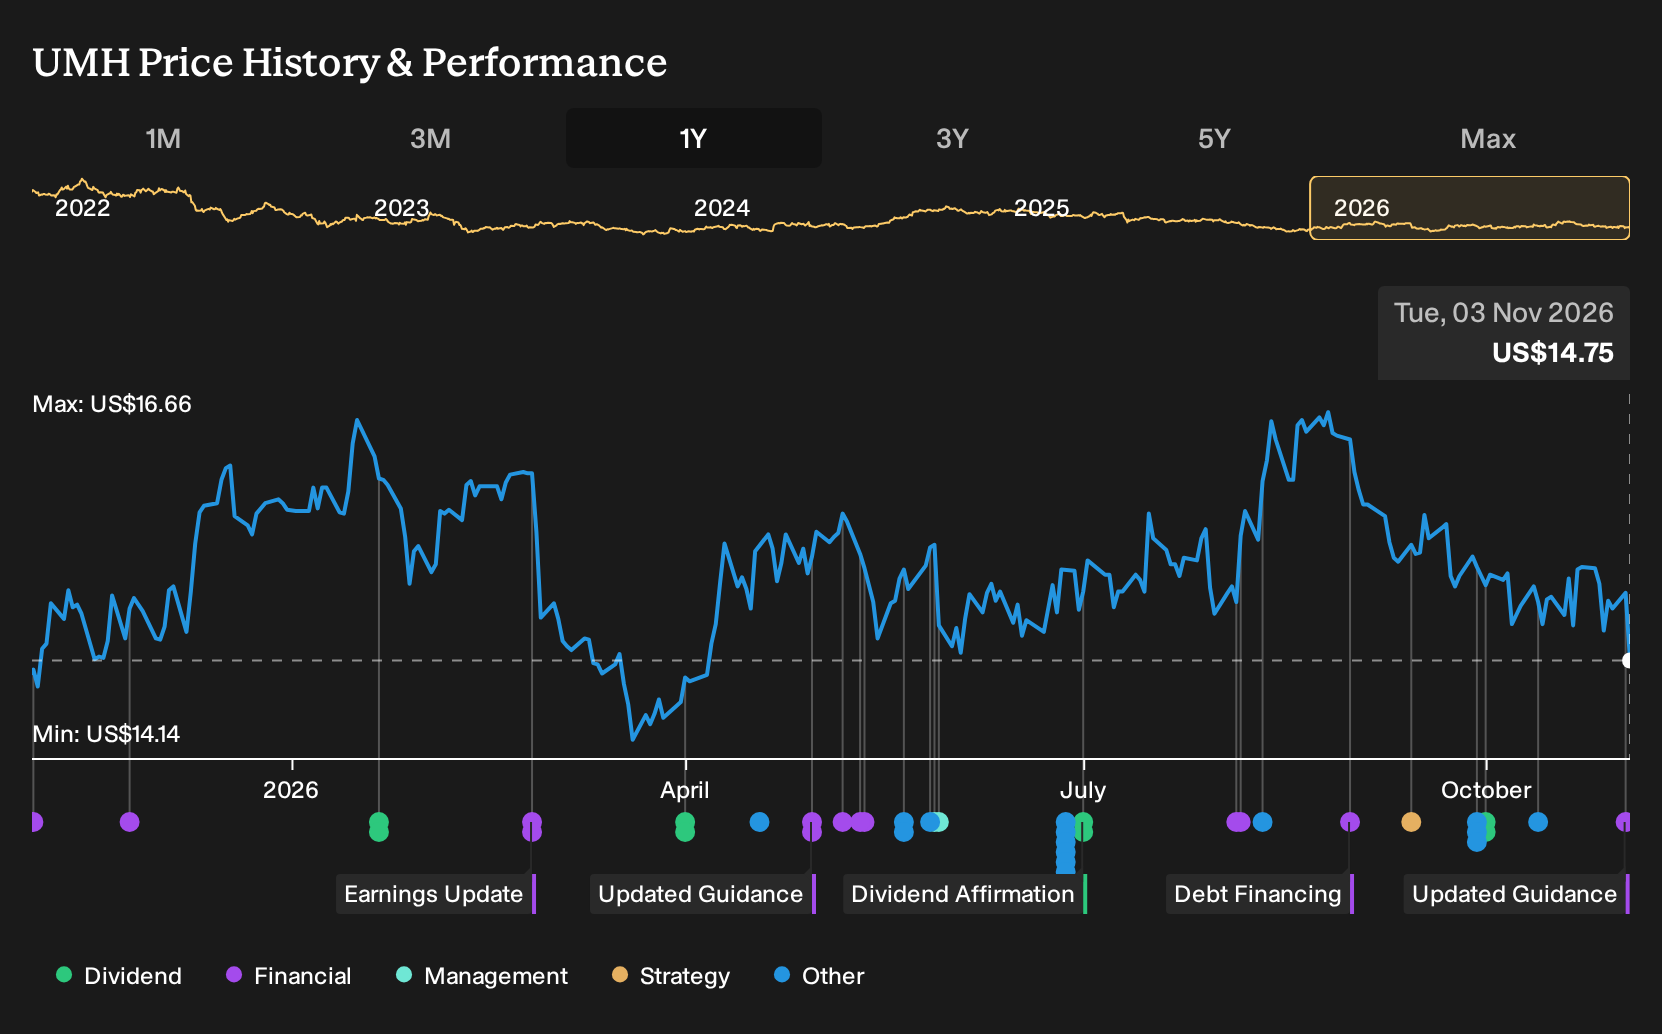
- UMH Properties reported third quarter 2026 results that included an 11% rise in total income, higher rental and related income, stronger manufactured home sales, and Normalized FFO of US$0.26 per share, with full year 2026 Normalized FFO guidance tightened to US$0.99 to US$1.03 per diluted share.
- The company paired these operating gains with capital moves, including issuing Series D preferred shares, which adds funding flexibility as it works to improve community occupancy and monetize vacant sites.
- We will now examine how UMH Properties' tighter full year guidance range could reshape the investment narrative around its manufactured housing platform.
UMH Properties Investment Narrative Recap
For a shareholder in UMH Properties, the core belief is that the REIT can keep filling its large pool of vacant and expansion sites while holding the line on operating costs. The tightened 2026 Normalized FFO guidance and new net income range of US$0.05 to US$0.09 per diluted share make the near term story more about execution than about potential upside surprises.
The key short term catalyst is still occupancy and home sales conversion, supported by the existing inventory of sites and rental homes. The main risk remains operating and interest expense pressure, which could squeeze already thin net profit margins if income growth slows or expense growth stays elevated.
The most relevant new data point is management’s 2026 guidance for net income attributable to common shareholders of US$0.05 to US$0.09 per diluted share. That sits alongside Normalized FFO guidance of US$0.99 to US$1.03 and helps frame how much of UMH Properties’ cash generation is absorbed by depreciation, interest costs and other non cash or non operating items.
For catalysts, the spread between FFO and GAAP earnings keeps attention on balance sheet structure, dividend coverage and interest expense, particularly in light of comments that interest payments are not well covered by earnings. Investors who are tracking UMH Properties closely are likely to focus on whether community level FFO growth, infill activity and any future capital raising can support both the dividend and community expansion without adding undue financial strain.
UMH Properties’ current analyst narrative points to revenues of US$342.0 million and earnings of US$13.7 million by 2029, based on assumed yearly revenue growth of 8.1% and an earnings increase of about US$3.0 million from US$10.7 million today.
Uncover why UMH Properties' fair value indicates a 28% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view around UMH Properties focuses less on expansion potential and more on interest costs creeping higher. The most pessimistic analysts were penciling in about US$347.0 million of revenue and only US$4.2 million of earnings by 2029. That is a far weaker profit story than consensus, and these fresh 2026 guidance numbers could eventually push those expectations in either direction. Readers can compare both sets of assumptions and decide which narrative feels closer to their own outlook.
Explore 2 other UMH Properties fair value estimates, including one that suggests it could be worth just $18.88!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your UMH Properties research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for UMH Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UMH Properties' overall financial health at a glance.
Looking for more investment ideas beyond UMH Properties?
If the latest UMH Properties update has sharpened your process, use that momentum to broaden your watchlist with other businesses that fit clear financial themes using the Simply Wall St Screener.
- For investors who prioritize financial resilience and clean balance sheets, review a curated list of solid balance sheet and fundamentals (23 results) that filters for companies with stronger fundamentals and lower leverage profiles.
- If you are hunting for quality at a reasonable price, scan a focused 35 high quality undervalued stocks built around businesses where cash flows and balance sheets look more robust than their current market pricing implies.
- Income focused readers who want potential cash returns front and center can assess a dedicated 4 dividend fortresses designed to spotlight higher yielding stocks with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com