


EN
Half Year Earnings Strength Could Be A Game Changer For NGK (TSE:5333)
- NGK Corporation reported half-year results for the period ended September 30, 2026, with sales of ¥371,306 million and net income of ¥60,800 million, alongside basic earnings per share from continuing operations of ¥214.66.
- The combination of higher sales and higher net income indicates improved profitability for NGK, which can sharpen the focus on how its core businesses are converting demand into earnings efficiency.
- The next step is to examine how NGK's stronger half-year profitability may influence the broader investment narrative that investors use to evaluate the company.
What Is NGK's Investment Narrative?
Owning NGK means believing this ceramics and power equipment specialist can keep turning a complex product mix into reliable earnings. The latest half year, with ¥371,306 million in sales and ¥60,800 million in net income, supports the view that operational execution across its Environment, Digital Society, and Energy & Industry segments is working. Stronger basic EPS from continuing operations at ¥214.66 also reinforces the idea that pricing, product mix, and cost control are aligning in shareholders’ favor, at least for now.
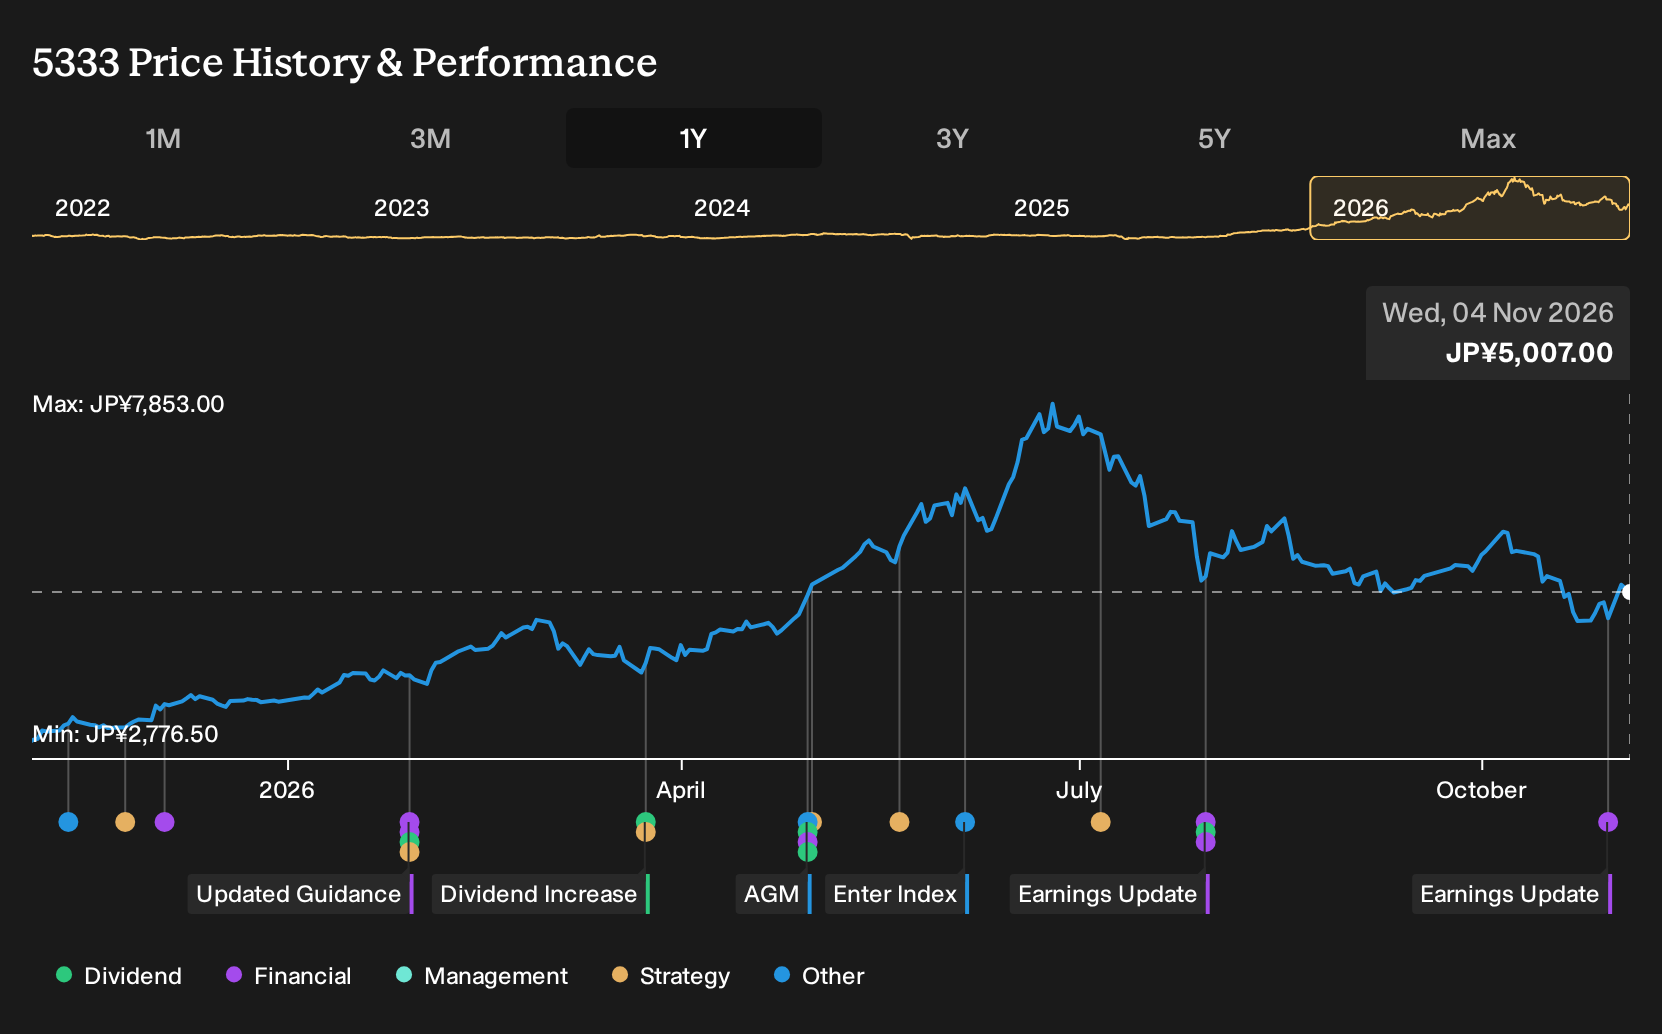
For shorter term catalysts, you are essentially assessing whether NGK can sustain this earnings quality while managing capital intensive projects and external borrowing as its main funding source. Analyst expectations for earnings and revenue growth, while positive, are not aggressive, which can keep attention on delivery rather than hype. Recent share price moves, with the stock down 14% over 30 days but still up strongly over 1 year, show how quickly sentiment can swing if demand for mobility, electronics, and infrastructure products softens or board level decisions unsettle investors. This half year result fits into that backdrop as a proof point on profitability, not a guarantee.
That said, one recurring weak spot in the NGK story still hangs over the otherwise solid earnings release. It starts with how the company...
There's only one way to know the right time to buy, sell or hold NGK. Head to Simply Wall St's company report for the latest analysis of NGK's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community bracket NGK between roughly ¥4,642 and ¥6,799 per share, which is a wide personal-forecast gap for just a pair of assessments. Those figures were set before the latest half year earnings release, so you are weighing fresh profitability data against older crowd assumptions.
Explore another NGK fair value estimate, including one that suggests as much as 7% downside from the current price.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NGK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NGK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NGK's overall financial health at a glance.
Looking For More Investment Ideas Beyond NGK?
If NGK's latest earnings have sharpened your focus on quality and risk, it can help to line it up against other candidates that share similar strengths or offer a different balance of income, balance sheet resilience, and potential upside. The Simply Wall St Screener gives you a way to scan for that mix quickly rather than trawling through individual reports one by one.
- If resilience matters most to you, you can filter for businesses that pair defensive characteristics with financial robustness by starting with a 22 resilient stocks with low risk scores.
- If income is a priority, you can focus on companies offering meaningful yield and distributable cash flows through a targeted search built around 29 dividend fortresses.
- If you want to cast a wider net for future candidates, you can broaden your watchlist with a curated 74 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com