


EN
First Merchants (FRME), Why Is It Getting Fresh Attention Now?
First Merchants earnings spark fresh focus on credit costs
First Merchants (FRME) just posted third quarter results that combined higher net interest income and quarterly net income with a sharp jump in net charge offs and a completed share buyback tranche.
Against that earnings backdrop, First Merchants’ share price sits at US$41.04, with the stock posting a 1-month share price return of 3.19% and a year to date share price gain of 9.44%, while the 1-year total shareholder return of 17.92% and 3-year total shareholder return of 58.50% suggest longer term holders have seen stronger compounding as the market reassesses both earnings power and credit risk in light of the jump in net charge offs and the recent buyback activity.
Scan how First Merchants compares on balance sheet strength and earnings quality by reviewing our hand picked list of solid balance sheet and fundamentals (23 results) alongside this latest jump in charge offs.
First Merchants now mixes stronger quarterly profitability, sharply higher net charge offs and a completed buyback at roughly US$41. The puzzle for investors is whether that blend still tilts the odds toward buyers on valuation grounds.
Most Popular Narrative: 13% Undervalued
Against the last close at $41.04, the most followed narrative puts First Merchants’ fair value at $47.00, which implies a discount that investors now have to weigh against higher credit costs and fresh buybacks.
Rapid migration and economic growth in core Midwest markets is fueling strong, broad-based loan demand, now reflected in nearly 6% annualized commercial and consumer loan growth in Q2 2026 within the three state footprint. This supports the view that First Merchants can continue to grow revenue as these regional trends play through.
See why 3 investors see First Merchants as 13% undervalued.
Result: Fair Value of $47.00 (UNDERVALUED)
Still, the narrative around First Merchants can quickly change if credit issues spread beyond the recent problem loans, or if higher cost subordinated debt keeps squeezing returns.
Find out about the key risks to this First Merchants narrative.
Another View: What First Merchants’ P/E Is Really Saying
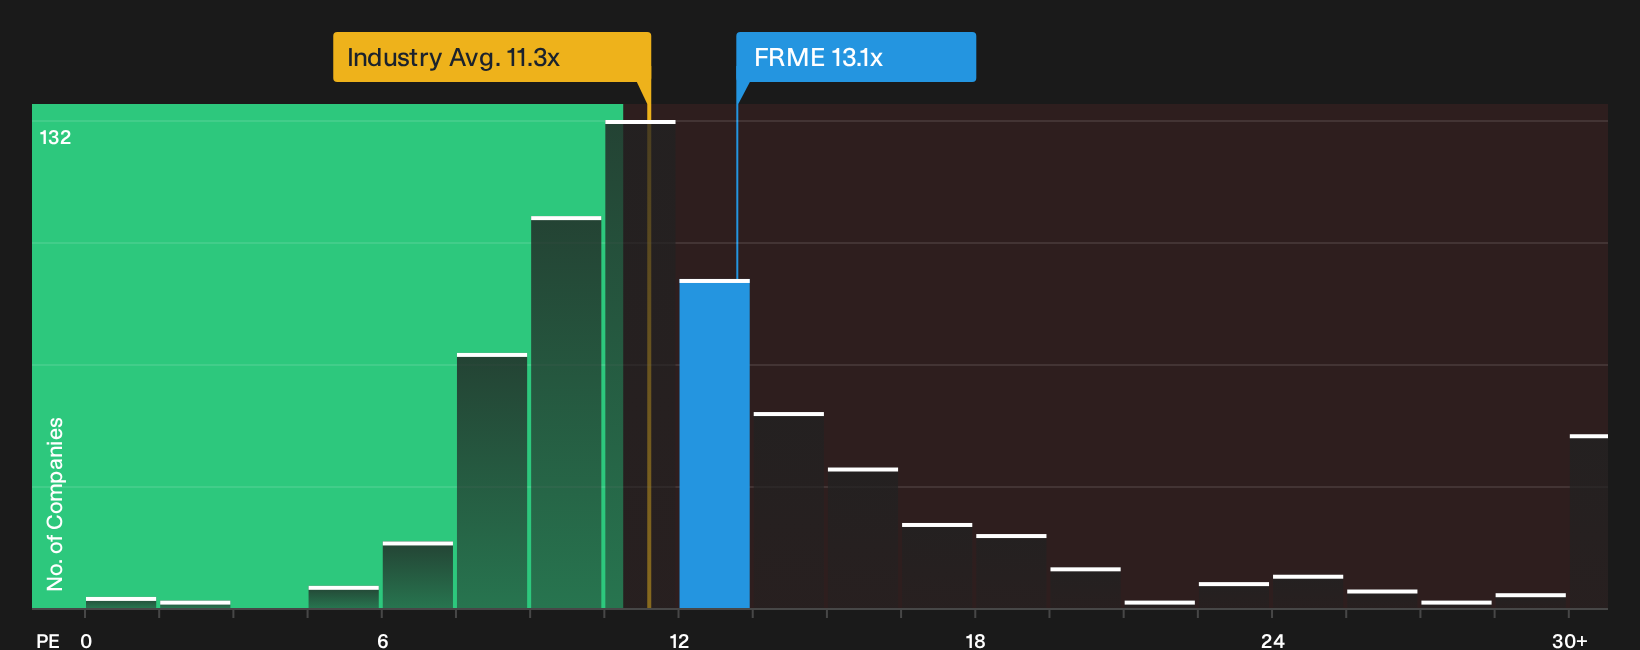
Look at First Merchants through its P/E and the story gets more complicated. The shares trade on 13.1x earnings, which is higher than both the US Banks industry on 11.3x and peers on 12.7x, even though the fair ratio sits at 14.2x.
That mix suggests the stock is not cheap on simple comparisons, yet still below the fair ratio the market could move toward. This leaves you weighing whether this is valuation risk if sentiment cools or an opening if earnings progress lines up with the premium. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment looks split, with credit worries on one side and valuation arguments on the other, so it helps to test the numbers yourself now. To see what the market currently views as the key positives, review the 3 key rewards
Looking for more investment ideas beyond First Merchants?
If you stop with First Merchants, you risk missing other opportunities that fit your style, return goals, and risk comfort across sectors and market caps.
- Spot early movers by scanning the 10 elite penny stocks with strong financials that pair tiny market caps with stronger financial underpinnings than you might expect.
- Zero in on quality at a discount by checking the 35 high quality undervalued stocks that blend solid cash flows with balance sheets the market may be underpricing.
- Build a steadier income stream by reviewing the 4 dividend fortresses that combine 5%+ yields with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com