


EN
Knight Swift Transportation Holdings (KNX) Could Be 26% Undervalued Following Strong Q3 Results
Knight-Swift Transportation Holdings (KNX) is back in focus after reporting third quarter results that showed higher sales, revenue and net income, along with rising interest from hedge funds and other institutional investors.
The earnings beat has landed against a mixed trading backdrop, with Knight-Swift Transportation Holdings’ 1-day share price return of 1.87% contrasting with a 30-day share price return that is down 5.92% and a 90-day share price return that is down 11.30%, even as the year-to-date share price return is up 20.26% and the 1-year total shareholder return sits at 41.96%.
Scan how Knight-Swift Transportation Holdings compares with other potential recovery plays by reviewing a curated set of 35 high quality undervalued stocks that pair strong fundamentals with compressed expectations.
Knight-Swift Transportation Holdings just posted much stronger earnings while the share price has pulled back over the past quarter. Strong operator, softer recent move. Is the stock simply catching its breath, or already fully valued?
Most Popular Narrative: 26% Undervalued
On the most widely followed view, Knight-Swift Transportation Holdings screens as undervalued, with a fair value of $85.10 against a last close of $62.81. That gap is tied directly to what the freight platform could earn if current plans work as modeled.
The continued expansion and integration of the LTL segment remains a key lever, with door count up roughly 10% by late 2025, new terminals opened in Phoenix, Olympia, Detroit and Toledo in 2026, and management indicating the current LTL infrastructure can support up to US$2b of annualized revenue. This leaves further room for revenue growth and operating ratio improvement as the network fills.
See why 2 investors see Knight-Swift Transportation Holdings as 26% undervalued.
Result: Fair Value of $85.10 (UNDERVALUED)
Still, Knight-Swift Transportation Holdings faces clear pressure points, including softer freight volumes and rising insurance and logistics carrier costs that could weaken the undervaluation case.
Find out about the key risks to this Knight-Swift Transportation Holdings narrative.
Another Angle On Knight-Swift Transportation Holdings’ Valuation
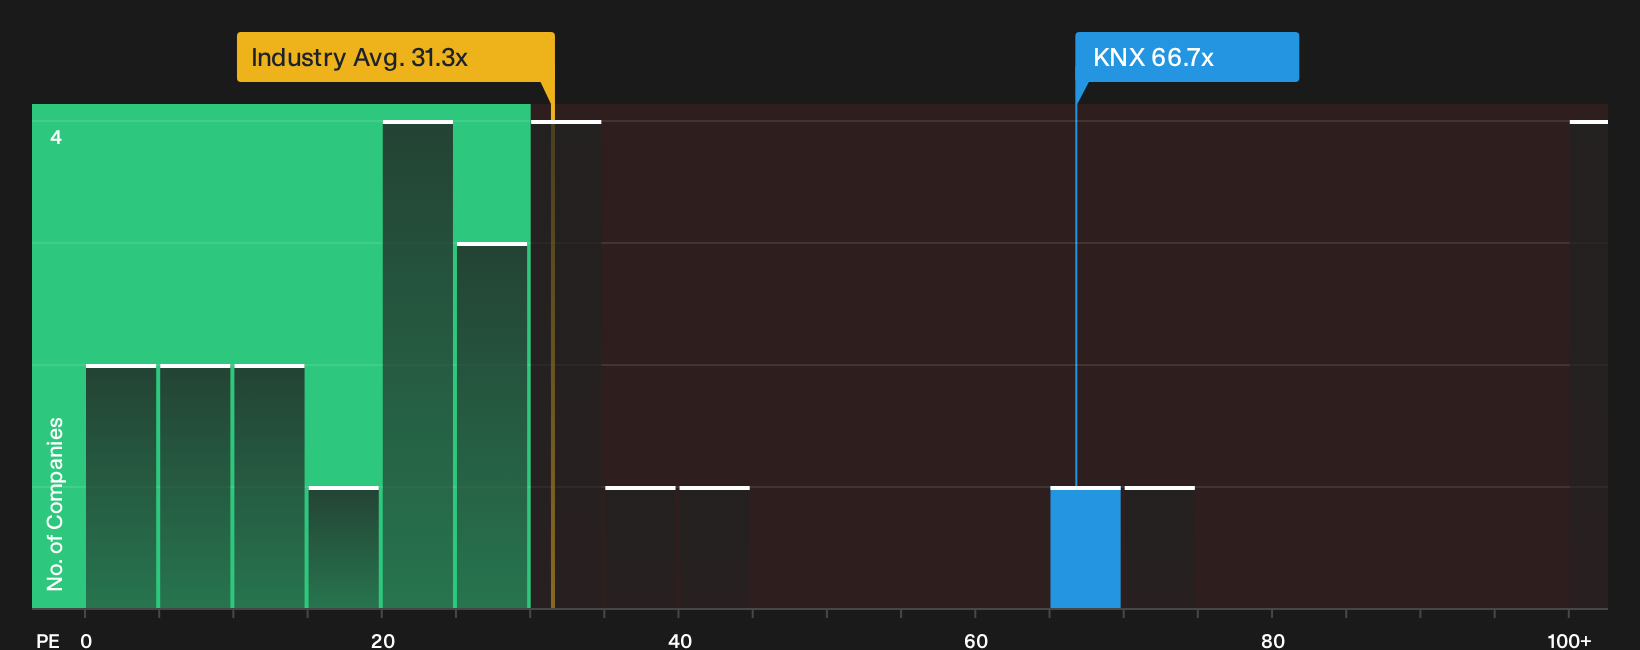
The story looks different when the focus shifts from fair value models to what the market is actually paying today. Knight-Swift Transportation Holdings trades on a P/E of 66.7x, compared with 30.2x for the wider US Transportation group and a peer average of 62.2x.
The SWS fair ratio sits at 26.2x. That is far below the current multiple, which suggests a lot of optimism is already built into the price and leaves less room for error if earnings progress falls short. Does that premium reflect durable strength, or is it stretching what the balance of risks supports?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The valuation debate around Knight-Swift Transportation Holdings is clearly split, which is exactly why it pays to run the numbers yourself instead of inheriting someone else’s conviction. If you want a quick shortcut to what the market is currently optimistic about, start with the 3 key rewards.
Looking for more Knight-Swift Transportation Holdings ideas and beyond?
Do not stop with Knight-Swift Transportation Holdings. Put a few minutes into fresh ideas now, or risk watching other investors move first.
- Target potential bargains early by scanning a curated 35 high quality undervalued stocks that pairs sturdy fundamentals with compressed expectations.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle tougher operating conditions.
- Spot under-the-radar potential by tracking a 19 high quality undiscovered gems before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com