


EN
What Is Driving Attention To Alamar Biosciences (ALMR) Today?
Alamar Biosciences (ALMR) just released its latest third quarter numbers, reporting revenue of US$33.55 million and a net loss of US$13.34 million, which is drawing close attention from investors.
Alamar Biosciences’ latest earnings update lands after a busy stretch, with the 1-day share price return of 4.42% taking the stock to US$30.22, even though the 30-day share price return is down 12.05% and the year to date share price return is up 37.36%. Recent Q3 results, stronger consumables demand, higher full year revenue guidance and new collaborations with UK Biobank and GSK have kept attention on the ticker. The mix of a softer 7 day share price return of 5.36% and a positive 90 day share price return of 6.60% suggests momentum is still positive but bumpier in the short term.
Seize this moment around Alamar Biosciences’ latest earnings and collaborations to compare it with a curated set of 34 healthcare AI stocks leading similar breakthroughs in data-driven medicine.After a sharp one day bounce and a mixed month on the chart, Alamar Biosciences now forces a choice. Is the current price fair compensation for its losses and collaborations, or is patience for a cheaper entry the better call?
Most Popular Narrative: 15% Undervalued
Alamar Biosciences closed at $30.22 against a widely followed fair value view of $35.40, so the current debate centers on whether that gap reflects execution risk or underappreciated progress in its proteomics platform.
Alamar Biosciences is tying a significant part of its future opportunity to regulatory and clinical adoption, including FDA marketing authorization for the ARGO HT/DX platform and wider use in late stage trials and diagnostics, and any delay or setback in this path could slow new revenue streams and limit the improvement of net margins and overall earnings.
See why 1 investors see Alamar Biosciences as 15% undervalued.
The prevailing narrative anchors that $35.40 fair value on a discounted cash flow style approach that applies an 8.09% discount rate to long term assumptions for revenue growth, profitability and capital needs. That required return sets the bar for how future cash generation would need to stack up for the current price and the fair value estimate to converge over time.
Analysts feeding into this storyline are assuming high top line expansion, with revenue growth forecasts of 37.4% annually in the detailed narrative and 27.3% per year in the broader forecast set, alongside a move from current losses to a 16.0% net margin consistent with the US Life Sciences industry by 2029. That path would imply earnings of $41.7 million on revenues of $260.6 million, with the stock trading on a P/E of 91.1x those future profits to support the $35.40 outcome, a multiple well above the 42.2x industry level referenced in the same framework.
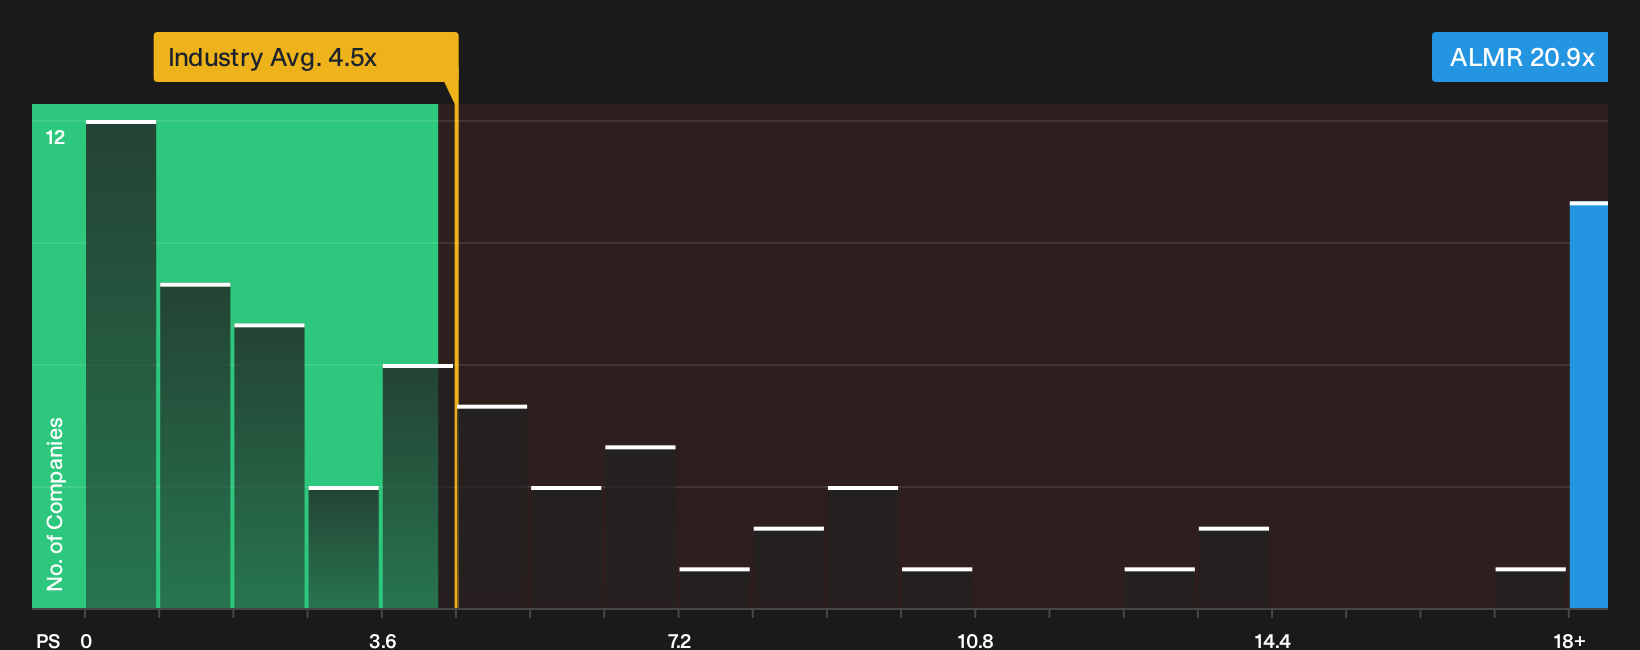
It is a demanding setup. Alamar Biosciences is still loss making today with an annual net loss of $49.661 million, carries a value score of 0 in the Simply Wall St model and is judged expensive on several present day checks including a P/S ratio of 20.9x versus an estimated fair P/S of 7x, a sector average of 4.7x and a peer average of 8.2x. On top of that, the stock is trading above the $8.70 future cash flow value output from the SWS DCF model, which indicates that the narrative based fair value is leaning more on optimistic margin and growth normalisation than on conservative cash flow assumptions.
Result: Fair Value of $35.40 (UNDERVALUED)
Still, the story around Alamar Biosciences can shift quickly if regulatory milestones for ARGO HT/DX slip or large cohort projects pause, which would challenge the fair value case.
Find out about the key risks to this Alamar Biosciences narrative.
Another View: What Multiples Say About Alamar Biosciences
There is a very different message coming from simple market ratios. Alamar Biosciences trades on a P/S of 20.9x, while the US Life Sciences group sits around 4.7x, peers average 8.2x and the fair ratio is 7x. That is a steep premium. If sentiment cools, are you comfortable owning a stock that may need the ratio to fall back toward that fair ratio?
For a closer look at how that premium compares with sector norms and how the fair ratio frames potential market moves over time, take a moment to review See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Alamar Biosciences can feel unsettling. Act while the details are fresh and test the story against your own thresholds with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Alamar Biosciences?
If Alamar Biosciences has your attention, do not stop here. Fresh opportunities often emerge where pricing, balance sheet strength and income potential quietly intersect.
- Target potential mispricing by scanning a curated set of 35 high quality undervalued stocks that combine quality fundamentals with more modest expectations baked into their valuations.
- Fortify your income stream by reviewing a hand picked group of 4 dividend fortresses that focus on higher yields with an emphasis on stability and resilience.
- Protect the downside first by assessing a 30 resilient stocks with low risk scores that filters for resilient balance sheets and lower overall risk scores before you commit new capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com