


EN
InterDigital (IDCC), Why Is Its Latest Update Drawing Attention?
Third quarter earnings and guidance shift put InterDigital in focus
InterDigital (IDCC) moved onto investor radar after its third quarter update combined higher quarterly sales and net income with a fresh lift to full year guidance for revenue, profit, and diluted EPS.
The earnings beat and guidance lift have arrived against a softer tape for InterDigital, with the share price down 7.3% over the past month and the 1 year total shareholder return lower by 18%, even after a very large 5 year total shareholder return of about 3.8x.
Compare InterDigital’s post earnings setup with other AI focused infrastructure plays by scanning our hand picked list of 53 AI infrastructure stocks for potential next moves in this theme.
InterDigital just paired a quarterly beat and higher full year guidance with a share price that has drifted lower. Does that make today’s valuation appealing, or is patience on a pullback the stronger call?
Most Popular Narrative: 32% Undervalued
InterDigital’s most followed narrative anchors fair value at $462.67 per share compared with the last close of $313.60. This frames the latest earnings beat and guidance lift as part of a larger undervaluation story built around recurring licensing cash flows.
The shift in InterDigital’s licensing mix toward streaming and cloud video services, supported by the Amazon agreement that currently recognizes revenue on a conservative estimate during arbitration, leaves scope for higher recurring revenue and earnings if the final award comes in above the booked level.
The continued build out of streaming and cloud video licensing, backed by recent injunction wins related to HEVC patents against large media groups, points to further fixed fee contracts that could broaden ARR and support EBITDA margins if more major video platforms sign on similar terms.
See why 19 investors see InterDigital as 32% undervalued.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, the InterDigital story leans heavily on the Amazon license outcome and on enforcement spending staying manageable. Either shift could quickly reshape this undervaluation narrative.
Find out about the key risks to this InterDigital narrative.
Another View: InterDigital Through A Cash Flow Lens
The bullish narrative around InterDigital’s $462.67 fair value leans heavily on recurring licensing and analyst targets. Our DCF model points in a different direction and suggests a future cash flow value closer to $206.42 per share, below the current $313.60 price. That gap raises a simple question for you: are earnings quality and analyst confidence enough to justify paying well above a cash flow based estimate?
Look into how the SWS DCF model arrives at its fair value.
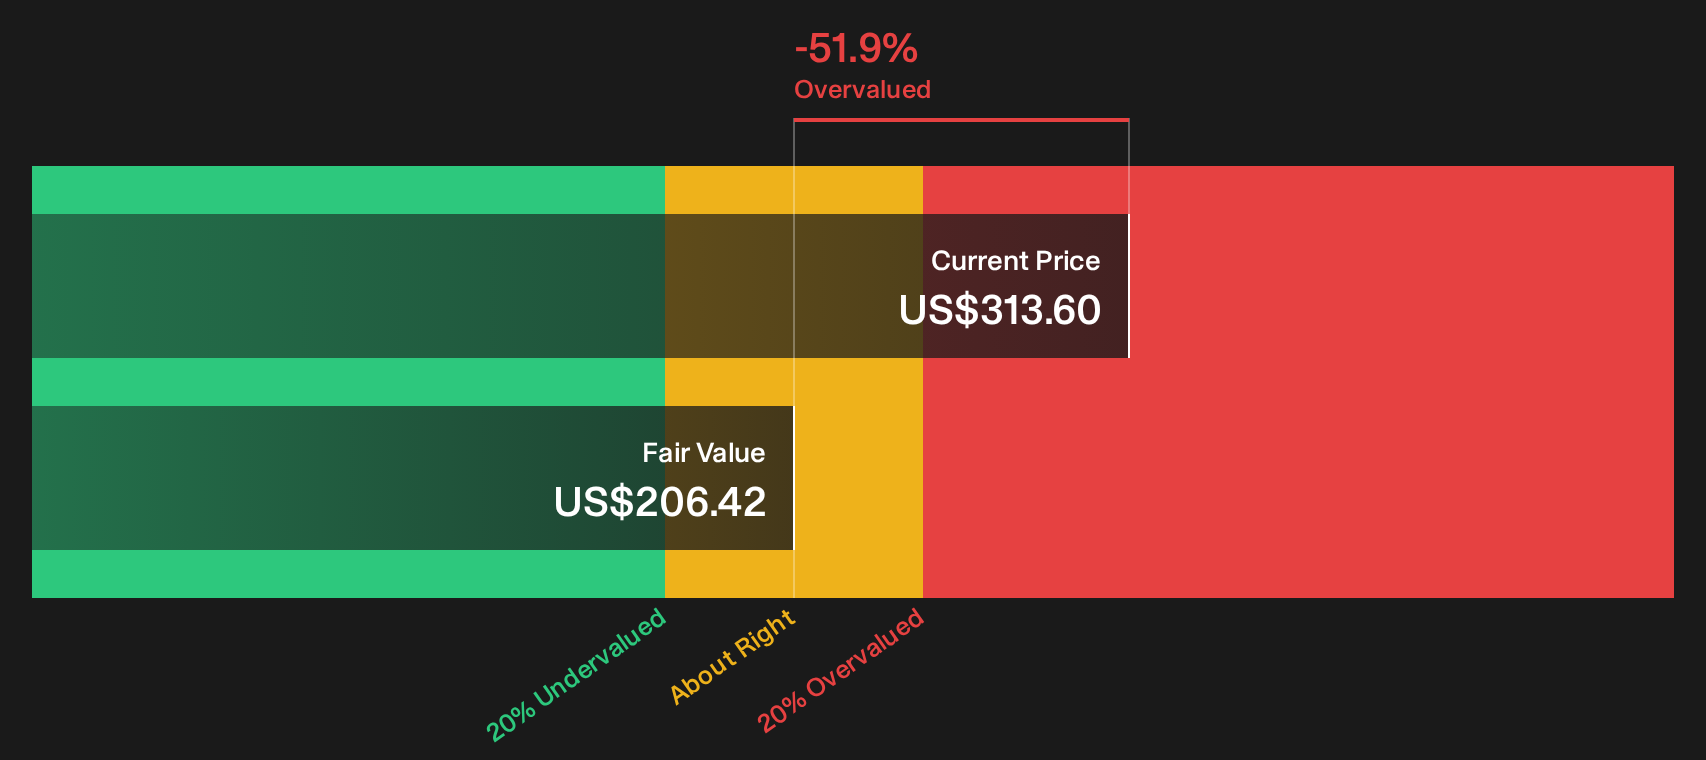
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out InterDigital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around InterDigital leaves you on the fence, move quickly to dig into the underlying data, weigh the upside against the concerns, and pressure test the story against your own risk tolerance using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond InterDigital?
InterDigital might be front of mind today, but your next strong idea could sit somewhere completely different. Give yourself options by scanning a broader opportunity set using the Simply Wall Street Screener.
- Target potential mispricing and focus your attention on companies that combine quality with attractive valuations through the 35 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with healthier finances and sturdier balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Hunt for lesser known opportunities and surface under followed companies with strong fundamentals by running the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com