


EN
Varonis Systems (VRNS) Could Be 3% Undervalued Following Q3 Results And The Proofpoint Deal
Varonis Systems (VRNS) is back in focus after reporting third quarter results on 3 November 2026, with revenue of US$189.46 million and a wider net loss of US$41.65 million.
Varonis Systems’ Q3 beat and the pending US$6.3b Proofpoint takeover sit alongside a strong run in the shares, with a roughly 52.8% year-to-date share price return and a 39.9% total shareholder return over 12 months suggesting momentum has been building rather than fading.
Spot fast-moving peers to Varonis Systems in data security and AI by scanning our curated list of 41 AI small caps that echo this earnings and acquisition momentum.After a near 53% year to date surge and a pending US$6.3b buyout, Varonis Systems now trades only slightly below analyst targets, but at a far steeper discount to some fair value models. Which reference point really anchors price here?
Most Popular Narrative: 3% Undervalued
Varonis Systems closed at $48.96 against a narrative fair value of $50.72, leaving a small implied discount that still leans in favor of buyers in that framework while keeping expectations anchored to a fairly tight valuation band.
The shift toward a fully SaaS delivery model, with the on prem subscription platform expected to reach end of life at year end 2026 and SaaS ARR metrics now in focus, can reshape Varonis Systems' recurring revenue visibility and provide a clearer path for future earnings quality once transition costs fade.
Expansion into adjacent products such as Atlas for AI security, Interceptor for email, database activity monitoring, and Data Lifecycle Management is increasing the breadth of the Varonis Systems platform. This can lift deal sizes, support cross sell, and influence future ARR growth.
What is behind 9 investors see Varonis Systems as 3% undervalued.
Result: Fair Value of $50.72 (UNDERVALUED)
Still, the SaaS transition is pressuring profitability and federal channel softness, so any setback on margins or government demand could quickly challenge this fair value story.
Find out about the key risks to this Varonis Systems narrative.
Another View: Varonis Systems Through The P/S Lens
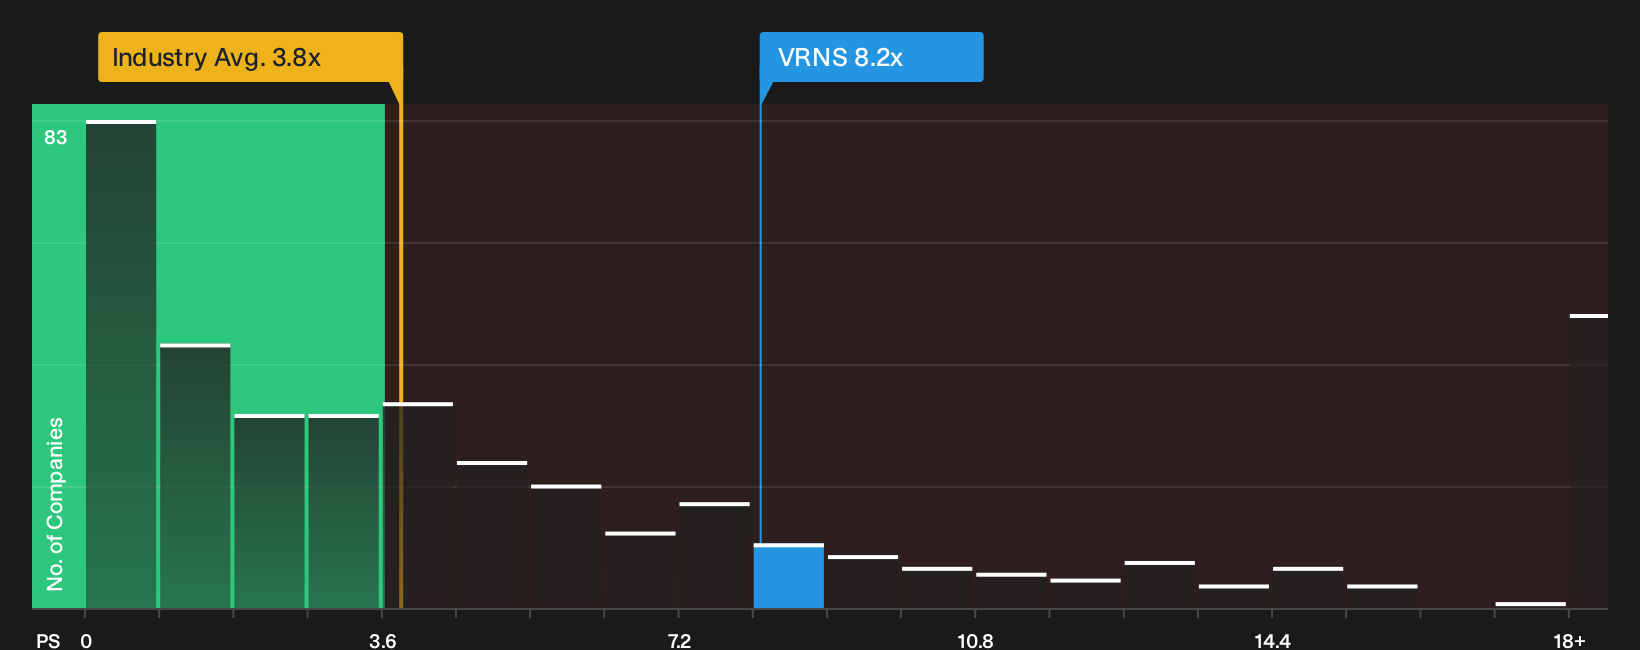
The DCF narrative on Varonis Systems leans toward undervaluation, with the stock trading at $48.96 against an estimated future cash flow value of $71.95. Yet the market is paying a P/S of 8.2x, compared with a fair ratio of 5.4x, the US Software industry at 3.8x, and peers at 4.6x. Does that premium signal conviction or leave less room if the story wobbles?
Investors who want to weigh this richer P/S profile against the cash flow case can go deeper into the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Varonis Systems story, with both pressure points and bright spots in play, make this a moment to move quickly and test the numbers yourself. To weigh those cross currents in full, start with our breakdown of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Varonis Systems?
Do not stop with one ticker. Use the same disciplined lens that you just applied to Varonis Systems and apply it across fresh opportunities that fit your style.
- Target potential bargains by scanning a curated pool of companies that screen as mispriced quality through the 35 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with stronger financial footing.
- Hunt for future standouts by checking a hand picked set of 19 high quality undiscovered gems before the crowd pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com