


EN
Third Quarter Earnings Could Be A Game Changer For Cousins Properties Stock (CUZ)
- Cousins Properties reported third quarter 2026 revenue of US$259.42 million and net income of US$17 million, with basic and diluted EPS from continuing operations at US$0.10. For the first nine months, revenue reached US$791.05 million and net income was US$18.3 million.
- The contrast between stronger third quarter earnings and lower nine month net income and EPS highlights how the timing of expenses, asset sales or other non operational items can shape the earnings profile investors see for Cousins Properties across a full year.
- We will now look at how Cousins Properties’ investment narrative could be affected by the third quarter uptick in quarterly earnings.
Scan how Cousins Properties’ latest earnings compare with those of its peers and identify other real estate stocks with similar profiles using our hand picked list of solid balance sheet and fundamentals (23 results).
Cousins Properties Investment Narrative Recap
Cousins Properties asks shareholders to believe in high quality Sun Belt offices, steady leasing pipelines and the ability to recycle capital into trophy assets. The third quarter step up in net income and EPS supports that story in the very near term. The main short term catalyst still sits in leasing execution and rent roll ups on expiring space, and this update does not radically change that.
The big risk has not moved either. Exposure to office demand in markets like Austin, Atlanta and Phoenix, combined with chunky lease expirations and hybrid work, still leaves earnings sensitive to occupancy and incentive levels. Mixed nine month profit figures, influenced by one off items, keep attention firmly on cash NOI, interest coverage and how quickly vacant space can be released on acceptable terms.
The most relevant reference point for this quarter remains the earlier refinancing of Cousins Properties' US$1.2b credit facility and term loans, alongside the US$500m unsecured bond and ongoing share repurchases. The latest earnings arrive against that backdrop of a company that has already locked in liquidity and some funding visibility. They now sit alongside a quarter with higher profit but thinner year to date net income.
For you as a holder or potential holder, that pairing of financial flexibility and uneven earnings matters. Interest payments are not well covered by current earnings and profit margins sit well below last year. Execution on leasing, capital recycling into newer assets such as 300 South Tryon and disciplined use of the repurchase authorization are central to whether this balance sheet structure feels comfortable or tight over time.
Cousins Properties' narrative projects US$1.1b revenue and US$98.7 million earnings by 2029. This implies 3.5% yearly revenue growth and an earnings increase of about US$92.3 million from US$6.4 million today.
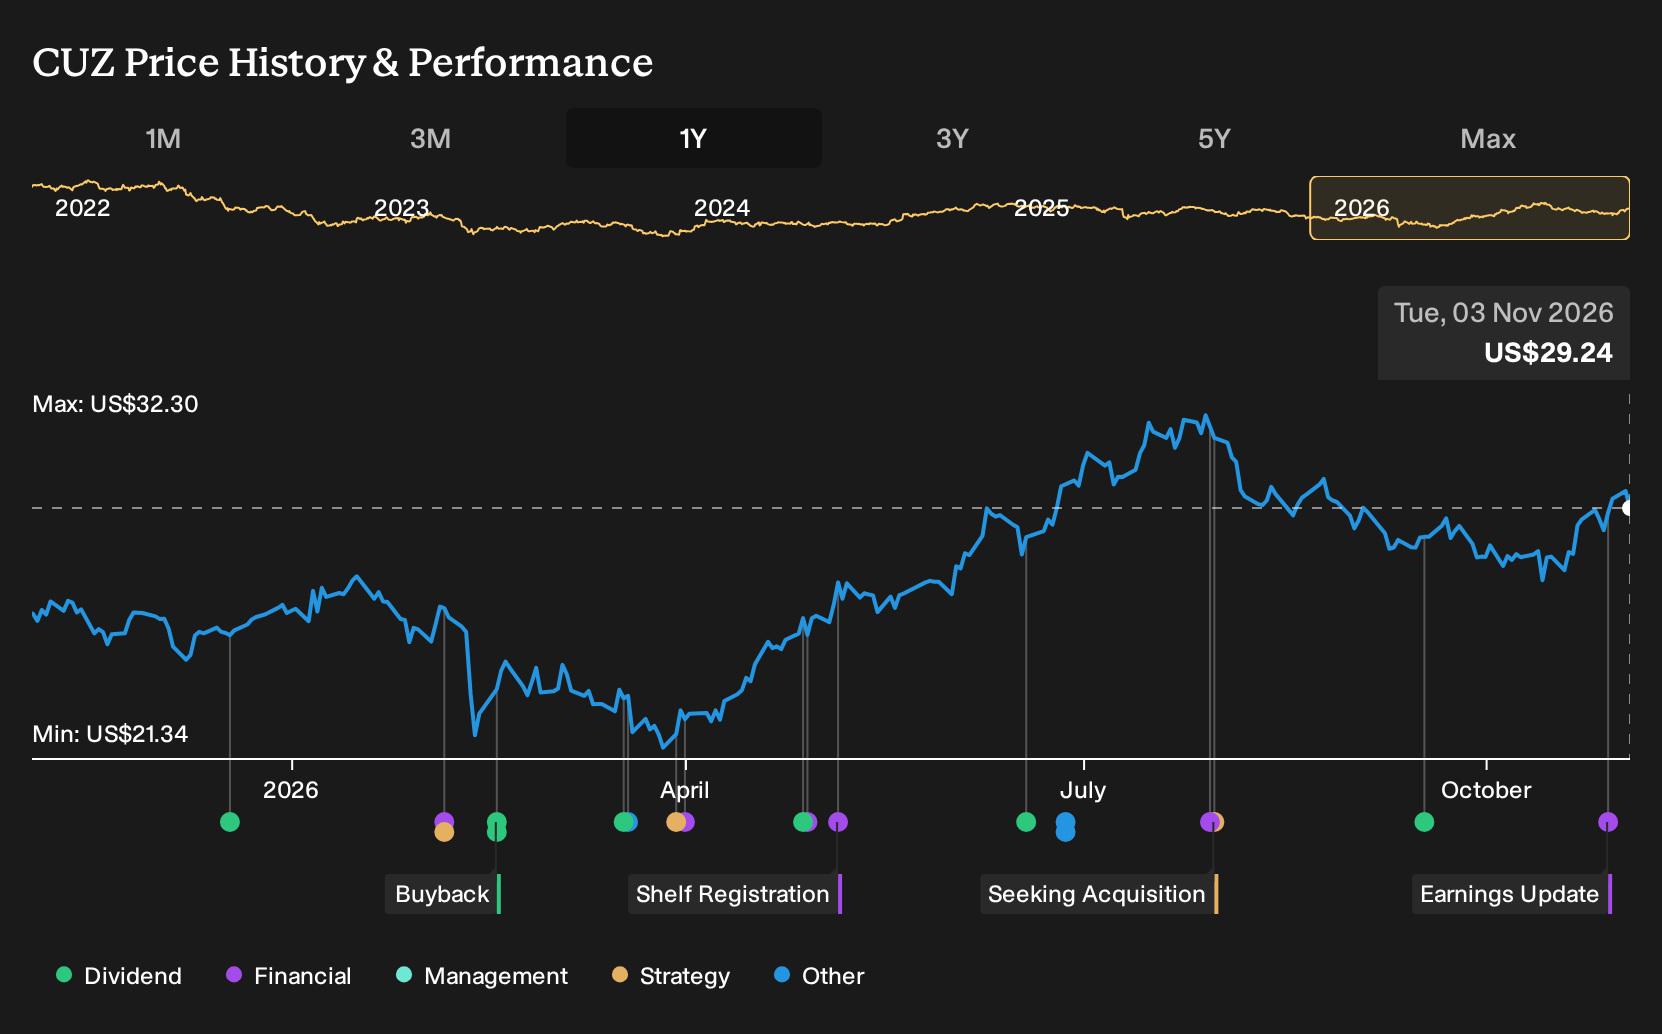
Uncover why Cousins Properties' fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view around Cousins Properties focuses on interest costs rather than leasing. The most cautious analysts worried that refinancing roughly US$465 million of 2026 debt could squeeze FFO even if offices stayed busy. Before this quarter, some of them modeled about US$1.1b revenue and US$131.2 million earnings by 2029. That is a much more optimistic profit path than the consensus baseline yet tied to a lower US$30.00 price target, which shows how differently you and other investors can interpret the same numbers. These forecasts were set before the third quarter report, so use this earnings update as a reason to compare several viewpoints rather than rely on a single story.
Explore 2 other Cousins Properties fair value estimates, including one that suggests it could be worth just $33.27.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cousins Properties research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cousins Properties. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cousins Properties' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cousins Properties?
Cousins Properties might be on your radar, but your portfolio does not need to hinge on one story. Use the Simply Wall St Screener to line up other candidates with balance sheets, income streams and risk profiles that match what you are really looking for.
- For investors who want potential mispricing backed by fundamentals, review our hand picked 35 high quality undervalued stocks that already clear a quality and financial strength bar.
- If income reliability matters most to you, filter for companies that prioritize steady cash returns to shareholders through our focused set of 4 dividend fortresses.
- When capital protection and resilience take priority over headline growth, start with a curated 30 resilient stocks with low risk scores that screen well on our risk scoring framework.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com