


EN
Is Standard Motor Products (SMP) Undervalued As Stronger Earnings And Reaffirmed Guidance Lift Sentiment?
Standard Motor Products (SMP) just paired a stronger third quarter and year to date earnings profile with reaffirmed 2026 guidance, a combination that set the tone for the latest move in the stock.
Despite a small 1 day share price decline of 1.73%, Standard Motor Products has seen a 7 day share price return of 19.37% and a 30 day gain of 19.56%. Its 1 year total shareholder return of 23.14% and 3 year total shareholder return of 39.61% point to momentum that recent earnings, reaffirmed 2026 guidance and the maintained dividend appear to have reinforced rather than reversed.
Capture this earnings momentum theme in a broader way by scanning a curated 35 high quality undervalued stocks that pairs solid fundamentals with what our model views as attractive pricing.The question now is whether that surge in Standard Motor Products reflects a reassessment of the underlying earnings power or a short burst of enthusiasm around headlines, which is where valuation metrics start to matter.
Preferred Price-to-Earnings of 10.9x: Is it justified?
Standard Motor Products now trades on a P/E of 10.9x, a level that sits below both its own fair ratio estimate and the broader Auto Components group. This points to the market assigning a more conservative tag to its earnings than those reference points imply.
The P/E ratio compares the current share price with earnings per share and gives you a quick shorthand for how much investors are paying for each dollar of profit. For a business like Standard Motor Products, which reports $91.9m in net income on $1.85b of revenue, the earnings line is central to how investors frame value.
That 10.9x multiple is well below the estimated fair P/E of 12.3x. This indicates the current pricing is meaningfully cheaper than the level our fair value model suggests the market could move toward. Against peers, the gap is even wider, with the P/E sitting under both the US Auto Components industry average of 15x and the peer average of 59.1x. This spread signals that investors are not paying up for this earnings profile in the same way they are for others in the group.
Explore the SWS fair ratio for Standard Motor Products.
Result: Price-to-Earnings of 10.9x (UNDERVALUED)
Still, the narrative around Standard Motor Products can shift quickly if auto part demand softens or if pricing pressure tightens margins in key segments.
Find out about the key risks to this Standard Motor Products narrative.
Another View: SWS DCF Signals Deeper Undervaluation
The P/E picture suggests Standard Motor Products looks inexpensive, but the SWS DCF model goes much further. It places fair value at $235.93 per share versus the current $44.86 price, which frames the stock as very deeply undervalued on a cash flow basis. That kind of gap raises a simple question for you: Is the model too optimistic, or is the market too cautious?
Look into how the SWS DCF model arrives at its fair value.
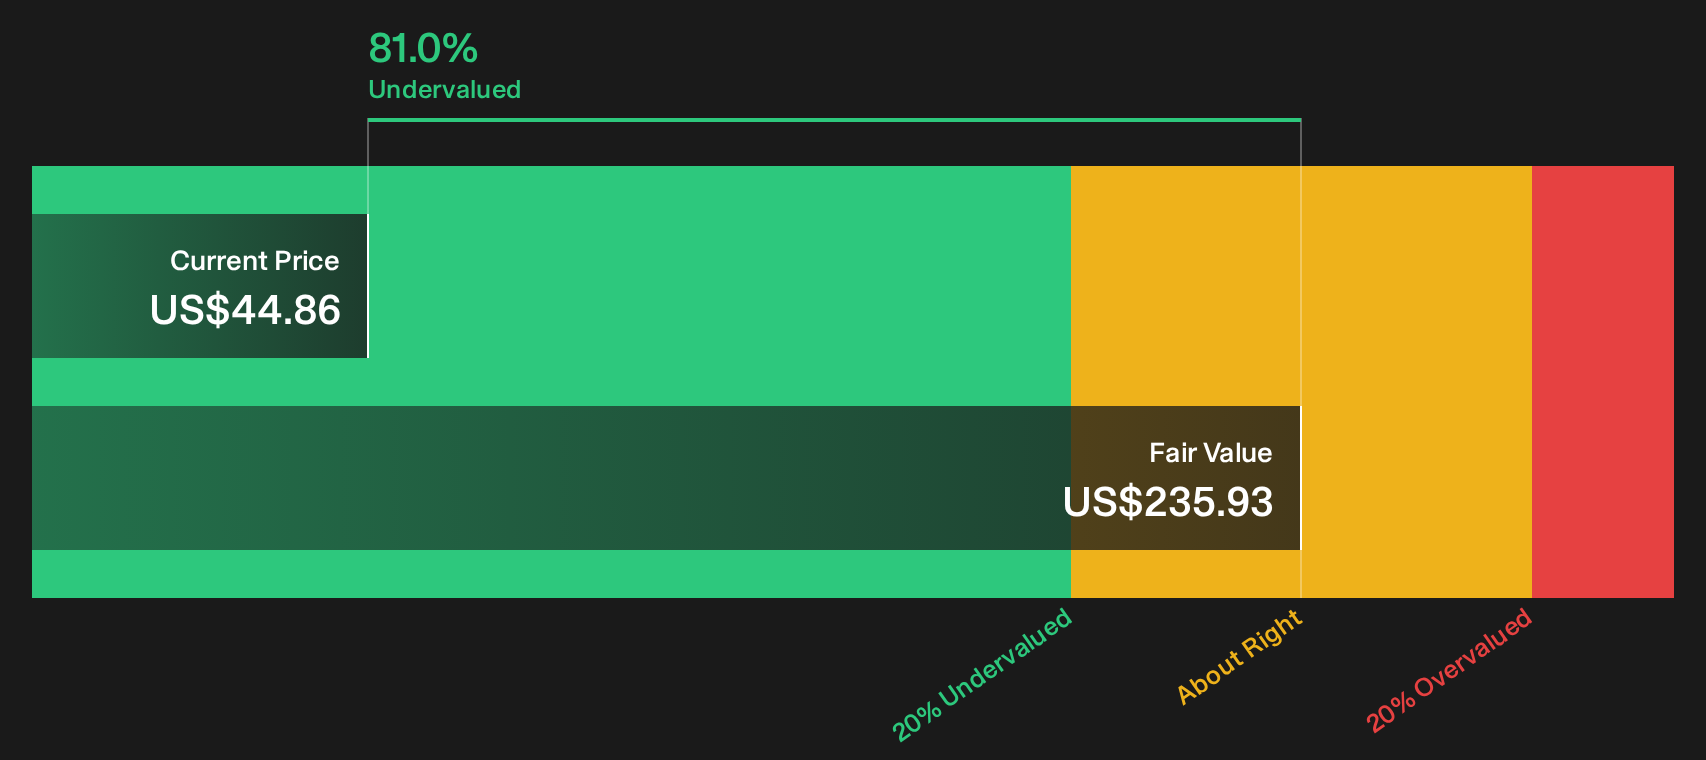
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Standard Motor Products for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling the mix of optimism and caution around Standard Motor Products in this update. Step in quickly, review the key data points, and weigh the 4 key rewards and 3 important warning signs for yourself.
Looking for more investment ideas beyond Standard Motor Products?
If Standard Motor Products has sharpened your focus on value and quality, do not stop here. Broader opportunity sits with carefully filtered ideas just a click away.
- Target resilient balance sheets and consistent fundamentals by working through a focused list of solid balance sheet and fundamentals (23 results) that keeps financial strength front and center.
- Hunt for quality at a discount by using a curated 19 high quality undiscovered gems that highlights companies the wider market may be overlooking.
- Prioritize stability and capital preservation by scanning a 30 resilient stocks with low risk scores designed to surface businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com