


EN
Agoda Deal Could Be A Big Growth Test For H World Group Stock
- H World Group's subsidiary H World APAC previously signed a five year cooperation agreement with Agoda to support expansion of roughly 70 hotels across Asia Pacific, using Agoda's market intelligence, investor introductions, and distribution reach to back the rollout.
- The arrangement connects H World APAC's hotel pipeline directly to Agoda's demand, data, and revenue programs, with the aim of both faster network build out and more commercially efficient openings.
- We will look at how H World Group's investment narrative is influenced by this Agoda backed Asia Pacific expansion plan.
Scan other travel and lodging plays that could ride similar cross border demand by reviewing the hand picked 19 high quality undiscovered gems alongside H World Group's latest Agoda partnership news.
H World Group Investment Narrative Recap
To own H World Group, you need to believe the hotel operator can keep scaling its manachise and franchise network while protecting returns in a softer demand backdrop. The Agoda tie up lines up with that story by plugging new Asia Pacific openings into a ready demand and pricing engine. However, it does not change the fact that flat to slightly higher RevPAR remains the near term swing factor.
The biggest short term catalyst is still how quickly recently opened and pipeline hotels in China and abroad season into higher margin fee income. The key risk stays the same. Supply has ramped, and same hotel RevPAR already slipped 2.3% in early 2026. Aggressive expansion into lower tier cities could extend underutilization and pressure earnings if spending stays weak.
The Agoda agreement sits alongside H World Group's wider international push through Legacy DH, which generated around RMB 500 million of adjusted EBITDA in 2025. Both moves point to management leaning into fee based growth outside mainland China, using partners and established brands to build a broader earnings base.
For you as a shareholder, the operational question is whether these overseas plays plus the upper mid scale portfolio in China can carry more of the growth load if domestic RevPAR stays muted. Execution on franchised and manachised openings, integration of Agoda's tools into day to day revenue management, and disciplined capital use all feed directly into that catalyst and the risk that expansion outpaces demand.
H World Group's narrative projects CN¥31.5b revenue and CN¥7.5b earnings by 2029. This assumes 5.8% yearly revenue growth and an earnings increase of CN¥2.5b from current earnings of CN¥5.0b.
Discover why H World Group's fair value points to a 26% potential upside from its current price, a gap that could close quickly.
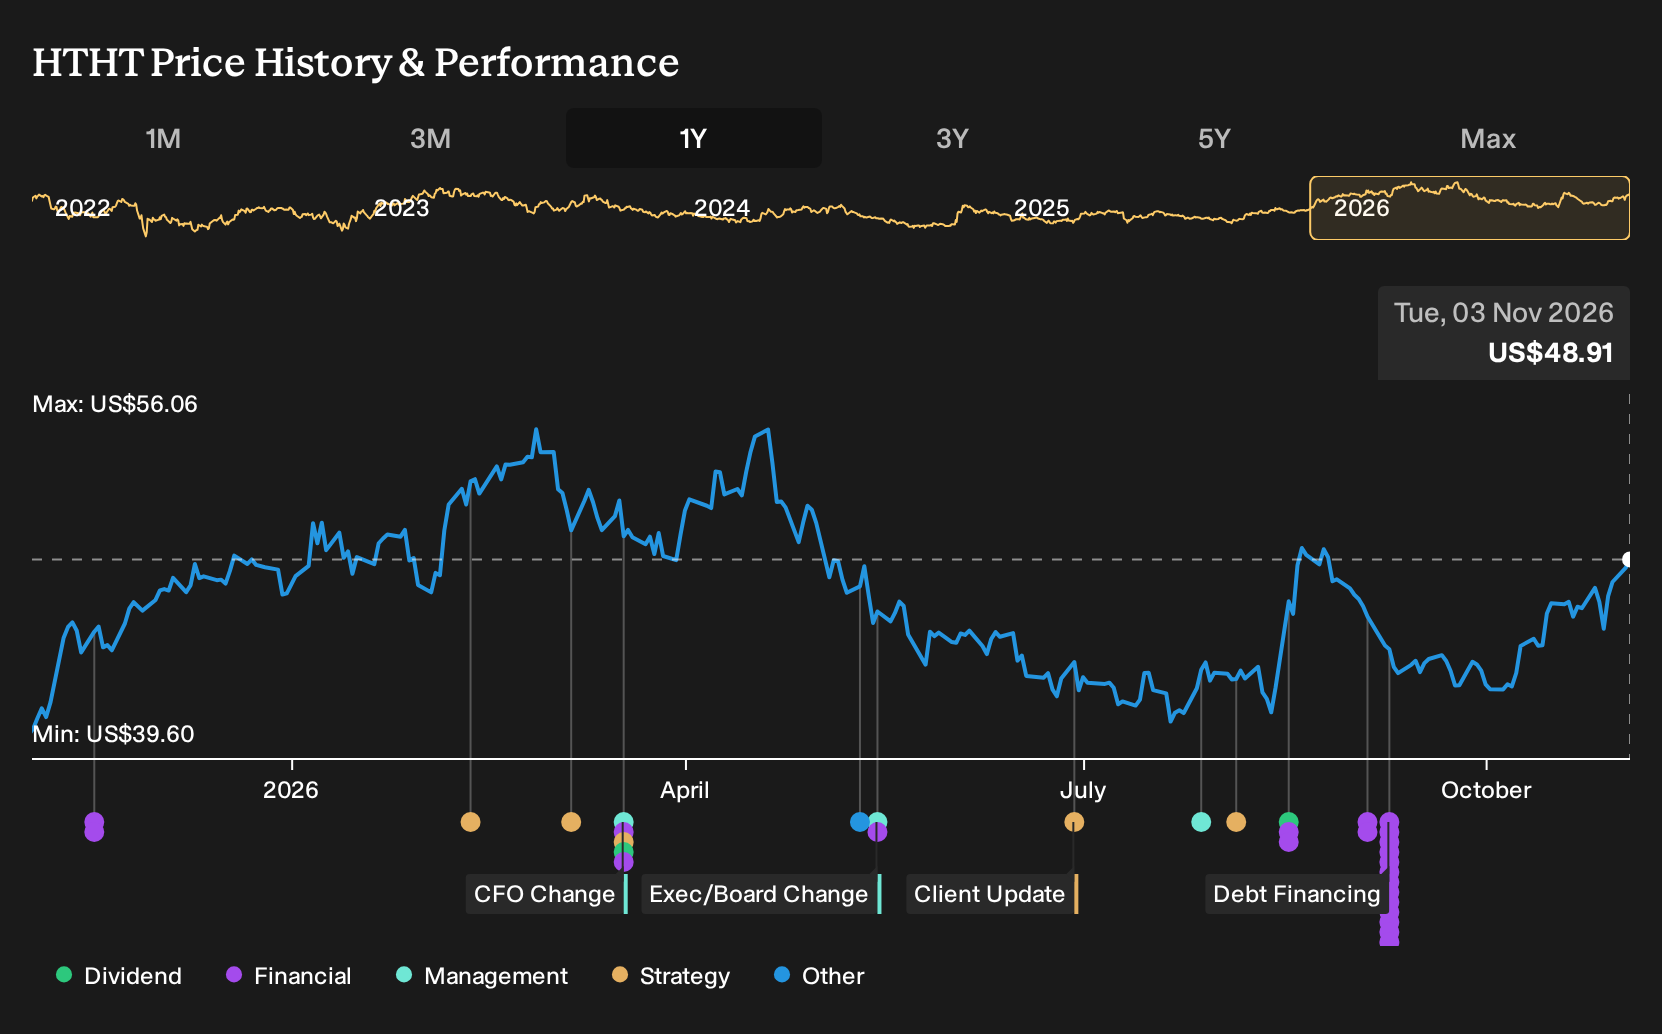
Exploring Other Perspectives
One alternate angle on H World Group focuses on the risk that adding more than 20,000 hotels in 2,000 cities could saturate weaker demand pockets, especially outside core hubs. The most cautious analysts were only penciling in about 4.7% yearly revenue growth to roughly CN¥30.5b and CN¥7.3b earnings by 2029. Their view is meaningfully more conservative than the baseline forecasts you saw earlier, and it was formed before this Agoda partnership. Use that gap as a prompt to compare several narratives and decide which assumptions feel closer to how you think this expansion could play out.
Explore 2 other H World Group fair value estimates, including one that suggests it could be worth just $59.02!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H World Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H World Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H World Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond H World Group?
If the Agoda partnership has you thinking more broadly about travel, lodging, and steady compounders, it can be worth lining H World Group up against other opportunities that share similar quality markers or risk profiles. A focused screener helps you compare like with like, rather than scrolling through tickers blindly.
- If capital preservation is near the top of your list, start with a basket of resilient businesses through the 30 resilient stocks with low risk scores to see which ones pair lower risk scores with more predictable fundamentals.
- Income focused readers who care about consistency over fireworks can scan the 4 dividend fortresses and filter for payout strength, yield level, and balance sheet support in one place.
- Those hunting for under the radar opportunities with solid financial footing can review the 19 high quality undiscovered gems and compare their metrics side by side with H World Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com