


EN
Panasonic Stock In Focus After Earnings Outlook And Dividend Hike
- Panasonic Holdings reported half year sales of ¥4,092,520m and net income of ¥276,953m, with basic EPS from continuing operations at ¥118.62, and issued full year guidance that includes expected net sales of ¥8,400,000m and basic EPS of ¥231.26 for the year ending March 31, 2027.
- The group linked a revised dividend policy to its earnings outlook, affirming a ¥27.00 interim payout and lifting the year end dividend forecast to ¥43.00 per share. This would take the full year dividend to ¥70.00 per share under a stated target payout ratio of about 30% of consolidated net profit.
- Next, the focus shifts to how Panasonic Holdings' upgraded earnings outlook and higher dividend guidance could reshape the existing investment narrative.
Scan how Panasonic Holdings fits within the broader income theme by comparing it to a curated group of stocks in the 28 dividend fortresses.
Panasonic Holdings Investment Narrative Recap
To stay invested in Panasonic Holdings, you need to believe the business can turn its broad electronics footprint and energy know how into more consistent earnings, backed by tighter cost control and a shift toward higher value solutions. The latest half year results, with ¥4,092,520m in sales and ¥276,953m in net income, point to solid execution despite past one off items. For the near term, the key swing factor remains how effectively Panasonic Holdings manages restructuring and fixed cost reductions across its portfolio.
The biggest operational risk still sits in execution issues around the Energy segment and EV related demand, where weaker markets, tariffs and ramp up challenges in Kansas have already created bumps. The upgraded full year guidance, including expected net sales of ¥8,400,000m and basic EPS of ¥231.26 for the year ending March 31, 2027, does not remove those pressures but signals management confidence that cost actions and mix shifts, including toward AI and data center related products, can offset some of that strain.
The clearest announcement tying this story together is the lift in full year dividend guidance. Panasonic Holdings is pointing to a year end dividend forecast of ¥43.00 per share and an expected annual payout of ¥70.00 per share under a target payout ratio of about 30% of consolidated net profit. That sits alongside an interim dividend of ¥27.00 per share already affirmed for the fiscal year ending March 31, 2027.
For you as an income focused holder, that updated dividend path makes the earnings guidance more tangible because it links cash distributions directly to the forecast profit trajectory. At the same time, there is still a flagged risk around dividend coverage from free cash flow and around earnings quality given earlier one off losses. The catalyst to watch is whether Panasonic Holdings can convert its cost reduction plans, AI and data center exposure, and Energy segment repositioning into cash generation that supports both that ¥70.00 per share payout and future flexibility.
Panasonic Holdings' current consensus narrative points to revenues of ¥9,165.1b and earnings of ¥735.4b by 2029, based on analysts assuming revenue grows about 3.9% per year and earnings rise from ¥253.2b today to that ¥735.4b level, which is roughly 2.9x higher than current earnings.
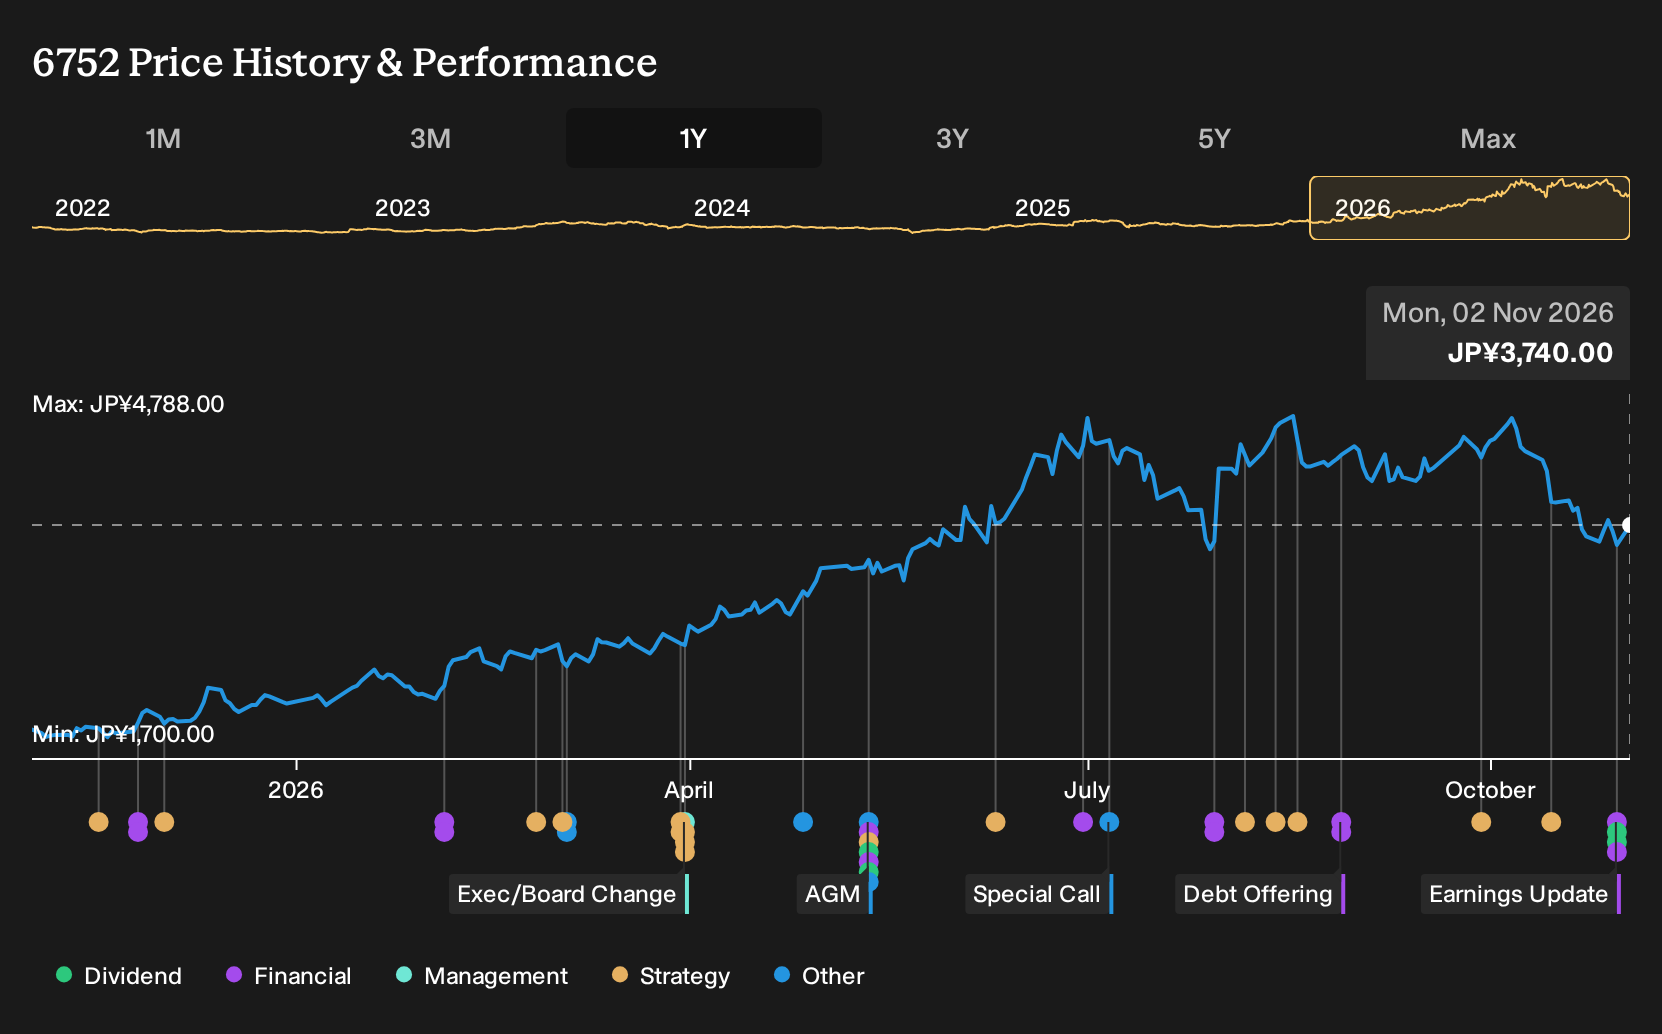
Discover how Panasonic Holdings' fair value signals a 33% potential upside to its current price before other investors notice the gap.
Exploring Other Perspectives
One bullish twist you may want to explore is how some analysts view Panasonic Holdings’ AI and data center push. Before this earnings release, the most optimistic forecasts were already pencilling in revenue of ¥10,050.0b and earnings of ¥1,012.8b by 2029. That is a far more upbeat story than the consensus view, and this new guidance could eventually lead analysts to revisit those scenarios.
Explore 3 other Panasonic Holdings fair value estimates, including one that suggests potential upside of up to 68% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Panasonic Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Panasonic Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Panasonic Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Panasonic Holdings?
If you want to stress test your view on Panasonic Holdings and build a broader watchlist around it, the Simply Wall St Screener can help you compare like for like opportunities in minutes rather than hours.
- For investors who care about balance sheet resilience as much as earnings power, the list of solid balance sheet and fundamentals (22 results) can highlight companies with financial foundations that may better support long term dividends and reinvestment.
- If value is your focus and you want candidates that pair quality fundamentals with what may be undemanding pricing, the 17 high quality undervalued stocks can surface a focused set of ideas to research next.
- Those seeking ideas that are less crowded by mainstream coverage can scan the 74 high quality undiscovered gems to find businesses with strong fundamentals that the wider market may not be paying close attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com