


EN
Beam Therapeutics (BEAM) Earnings Miss Puts Its Valuation Narrative To The Test
Beam Therapeutics (BEAM) is back in focus after third quarter 2026 results showed a wider net loss and revenue below expectations, putting fresh attention on its cash burn and clinical pipeline.
Beam Therapeutics shares have slid 8.5% over the past week and are down about 3% year to date on a share price basis, even though the 1-year total shareholder return of 14.1% and 3-year total shareholder return of 15.0% point to uneven but still positive longer term momentum compared with the much steeper 5-year total shareholder return decline of 71.1% as investors weigh the wider loss, weaker revenue and recent BEAM-301 data against future pipeline and financing risk.
Spot potential rebounds and avoid persistent cash burners by comparing Beam Therapeutics with a hand-picked group of 34 healthcare AI stocks.The latest drop in Beam Therapeutics looks tightly linked to the earnings miss and cash burn questions rather than a clear verdict on its gene editing pipeline. So how does that tension show up in the current valuation?
Most Popular Narrative: 47% Undervalued
Beam Therapeutics closed at $26.33, while the most followed narrative pegs fair value at $49.38. The gap between story and price is wide and anchored in specific program milestones rather than vague optimism.
The accelerated approval design for BEAM-302 in alpha-1 antitrypsin deficiency, built around an approximately 50-patient pivotal Part C cohort at 60 mg with 12-month biomarker endpoints and a planned functional-outcome confirmatory trial, positions a second potential product that could add to revenue and earnings if approval is achieved.
Emerging clinical proof of concept for BEAM-301 in glycogen storage disease type Ia, including single-dose base editing associated with extended fasting tolerance and reduced cornstarch use in the higher-dose cohort, supports a broader liver disease franchise that could widen future revenue sources if larger trials are successful.
See why 62 investors see Beam Therapeutics as 47% undervalued.
Result: Fair Value of $49.38 (UNDERVALUED)
Still, the story can break the other way if safety setbacks in risto-cel conditioning or weaker BEAM-302 data push approvals and revenue further out.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: Beam Therapeutics Looks Expensive On Sales
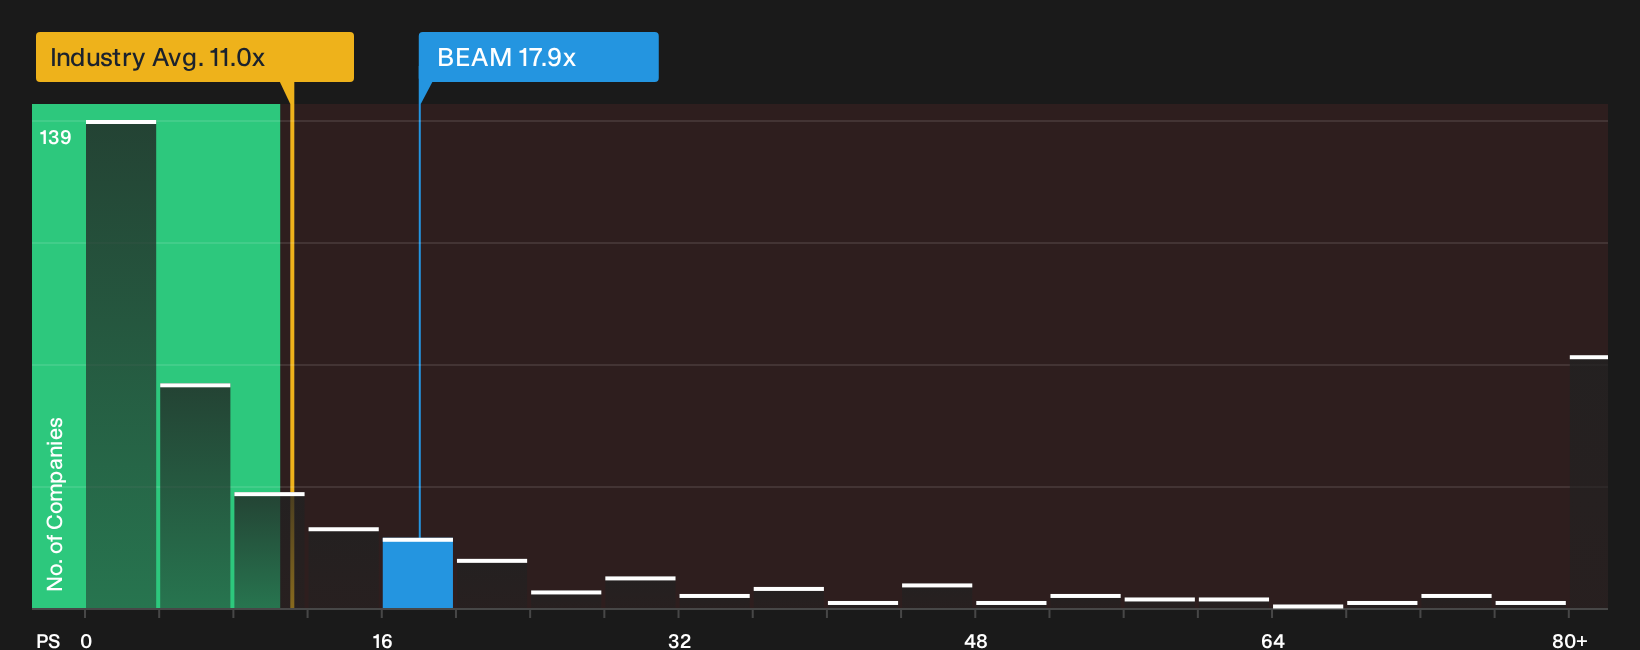
There is a clear clash here. While the narrative points to Beam Therapeutics being 47% undervalued on a fair value of $49.38, the current P/S ratio of 17.9x looks rich next to the US Biotechs sector on 11x and a fair ratio of just 0.9x that the market could eventually lean toward.
If revenue or sentiment disappoints, that gap leaves far less room for error than the story-driven fair value suggests. The question is which signal to rely on more: the story or the sales multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Beam Therapeutics can make the story feel messy, so move quickly and stress test the thesis yourself by weighing the 2 key rewards and 2 important warning signs.
Looking for more Beam Therapeutics sized ideas?
Do not stop with Beam Therapeutics. Broaden your watchlist with fresh opportunities that match your risk, income, and quality preferences before the next move leaves you behind.
- Target potential mispricings by scanning a curated set of 34 high quality undervalued stocks that pair stronger financial profiles with more modest expectations.
- Lock in steadier income streams by focusing on dependable payers from our hand picked pool of 4 dividend fortresses.
- Dial back risk without stepping away from the market by filtering for a 30 resilient stocks with low risk scores that still keeps your capital working.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com