


EN
Does Earnings Beat Change The Bull Case For Trustmark Stock (TRMK)?
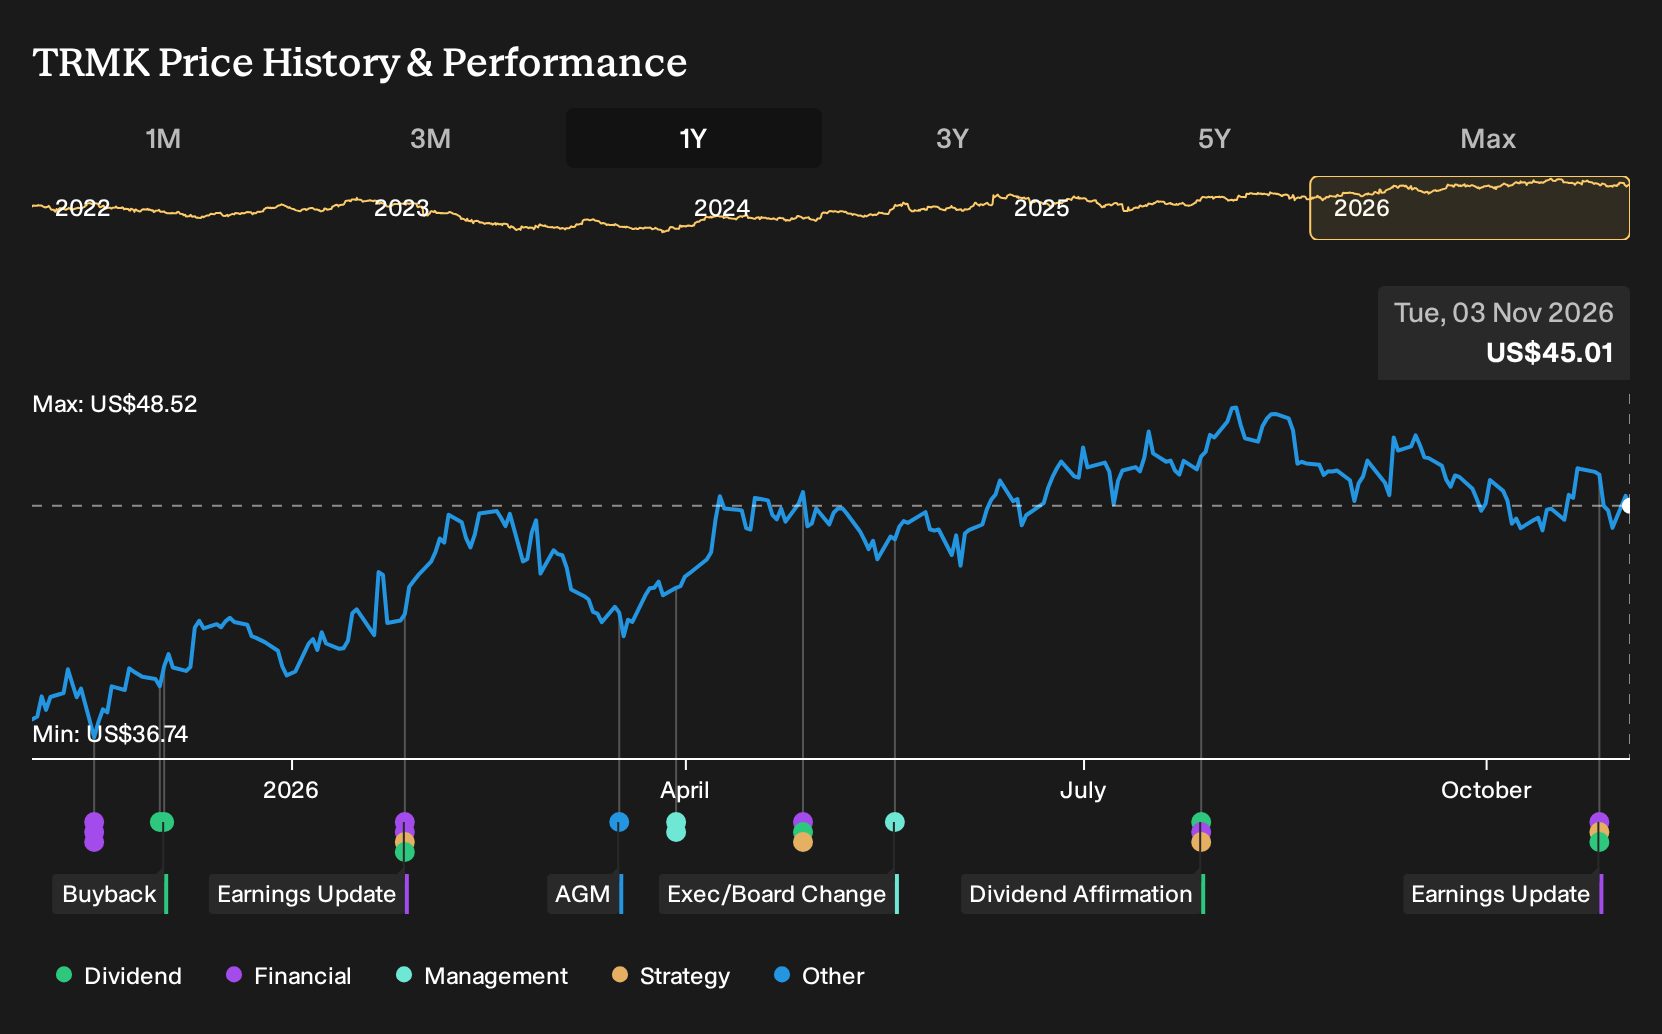
- Trustmark Corporation reported third quarter 2026 results, with net interest income of US$170.57 million, net income of US$58.07 million, lower net charge-offs of US$1.03 million, continued buybacks, and a US$0.25 quarterly dividend declared for payment in December 2026.
- Beyond the headline earnings beat, Trustmark combined disciplined credit costs, a completed share repurchase tranche, and a branch sale-leaseback gain to reinforce its capital return and balance sheet repositioning efforts.
- Investors can now assess how Trustmark's investment narrative is affected by the earnings beat and the sharp reduction in net charge-offs.
Scan beyond Trustmark's latest quarter and compare this bank's risk and return profile with a hand picked 30 resilient stocks with low risk scores that prioritise resilient balance sheets.
Trustmark Investment Narrative Recap
To own Trustmark, you need to be comfortable with a regional bank that leans heavily on its Gulf South footprint, steady net interest income and tight expense control. The latest quarter supports that story, with net interest income of US$170.57 million and net income of US$58.07 million pointing to an operating model that is holding up in the near term.
The key near term swing factor is whether loan demand and fee lines can offset any pressure from securities repositioning and deposit pricing. The biggest risk still sits in concentration, both in geography and in expectations that margin resilience and efficiency gains from the FIS conversion continue without slipping.
The clearest tie between this earnings release and the current thesis is the sharp reduction in net charge offs to US$1.03 million from US$4.39 million a year ago. That drop fits the idea that recalibrated CECL models and lower realized losses can keep provision expense relatively contained and make earnings less volatile.
For you as a shareholder, the question is whether this cleaner credit picture persists while Trustmark keeps leaning into balance sheet moves such as the branch sale leaseback and securities restructuring. If credit trends were to reverse, that would cut against one of the main catalysts backing the efficiency story and could quickly turn a modest tailwind into a drag.
Trustmark's narrative projects US$1.0b revenue and US$252.1 million earnings by 2029. This assumes 7.4% yearly revenue growth and an earnings increase of about US$17.8 million from US$234.3 million today.
Discover why Trustmark's fair value indicates a 12% potential upside to its current price that may not last much longer.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Trustmark research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trustmark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trustmark's overall financial health at a glance.
Looking for more investment ideas beyond Trustmark?
Once you have a view on Trustmark, it often helps to widen the lens and compare it with other businesses that share similar qualities or offer a different mix of risk and return. The Simply Wall St Screener gives you a way to do that quickly, using filters that focus on the characteristics you care about most.
- If you are hunting for resilient balance sheets and lower volatility, start with a 30 resilient stocks with low risk scores that targets businesses with stronger risk scores and more defensive profiles.
- For investors who care about quality at a reasonable price, scan a 34 high quality undervalued stocks that blends solid fundamentals with potential valuation gaps.
- If reliable payouts matter to you, look through a 4 dividend fortresses that highlights companies offering higher income potential with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com