


EN
Revenue Growth Might Change The Case For Investing In Trip.com Group (TCOM)
- Trip.com Group reported 5.5% year over year revenue growth in its latest quarter, with a 36.9% net margin and net cash exceeding debt by CNY 47.1b.
- The combination of high profitability and a sizeable net cash position gives Trip.com Group added flexibility to fund product development, marketing and international expansion without relying heavily on borrowing.
- We will examine how Trip.com Group's investment narrative is shaped by this 36.9% net margin and sizeable net cash cushion.
Scan other highly cash-secure businesses moving on strong balance sheets with the curated 30 resilient stocks with low risk scores that echo Trip.com Group's mix of profitability and financial resilience.
Trip.com Group Investment Narrative Recap
To own Trip.com Group, you need to be comfortable with a travel platform that leans heavily on scale, mobile engagement and international exposure, while working through regulatory and cost headwinds at home. The latest quarter, with 5.5% revenue growth and a 36.9% net margin, supports a view that the core engine is still functioning well.
The most important short term swing factor is demand for domestic and outbound travel, given recent softness in transportation ticketing. The biggest near term risk sits in cost inflation and the antitrust related changes to hotel distribution. On both fronts, this quarter’s figures look incrementally reassuring but not transformational.
One element that ties directly into this update is the previously flagged regulatory action on Trip.com Group’s hotel distribution and pricing practices. The risk was clear. Less control over independent hotel inventory could compress commission rates and limit how much of each booking drops to profit.
The current 36.9% net margin and sizeable net cash balance do not remove that regulatory overhang, but they give management more room to adjust collaboration models and absorb any pressure on individual segments. For you as a shareholder, the operational question is whether that financial cushion buys enough time to keep investing in inbound travel, international platforms and AI tools like TripGenie while those regulatory and demand issues play out.
Trip.com Group's narrative projects CN¥85.8b revenue and CN¥15.6b earnings by 2029, based on analyst estimates. This implies 9.4% yearly revenue growth and an earnings decline of CN¥8.6b from current earnings of CN¥24.2b.
Uncover why Trip.com Group's fair value indicates a 41% potential upside to its current price and why this opportunity could narrow quickly.
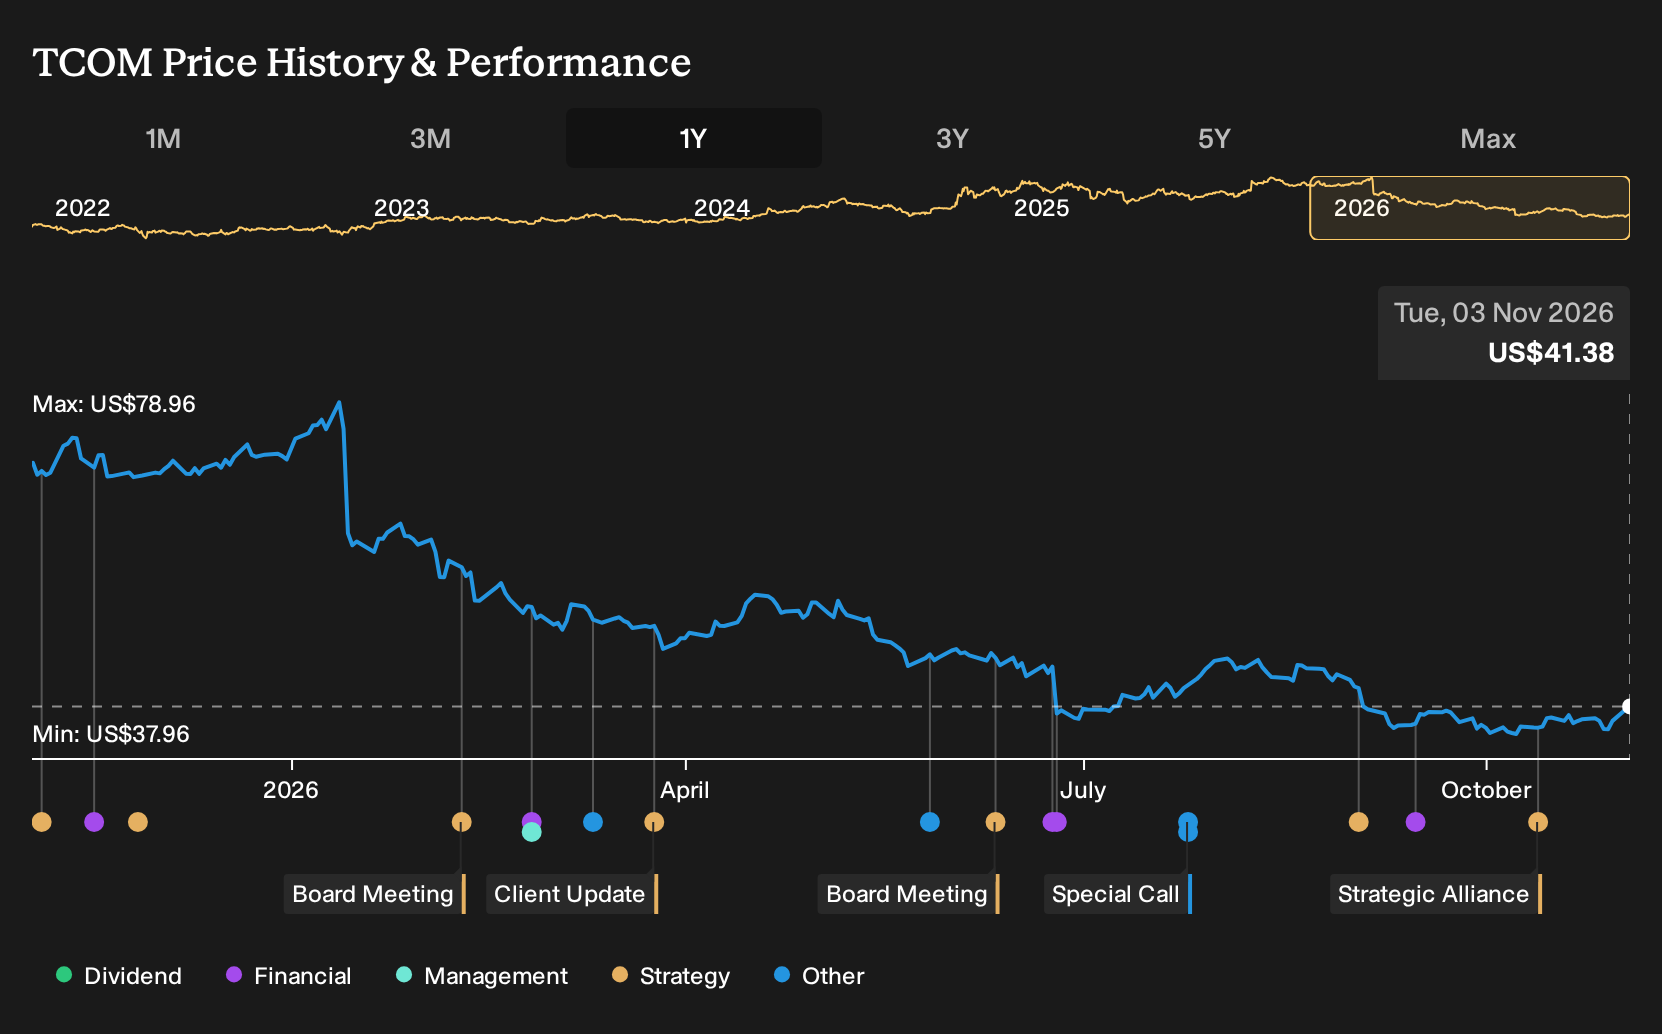
Exploring Other Perspectives
You might read the same Trip.com Group update and focus on a very different risk. The most cautious analysts worry about AI platforms capturing the customer relationship, and before this news they were only penciling in CN¥82.3b of revenue and CN¥12.6b of earnings by 2029. Use that gap in expectations as a prompt to explore several contrasting viewpoints.
Explore 4 other Trip.com Group fair value estimates, including one that suggests it could be worth just $46.83.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Trip.com Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Trip.com Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trip.com Group's overall financial health at a glance.
Looking for more Trip.com Group style ideas?
If this Trip.com Group update has sharpened your thinking and you want to broaden your watchlist, use the Simply Wall St Screener to scan for other businesses that line up with your preferred mix of quality, income, and balance sheet strength.
- If you want a head start on potential mispriced opportunities, review a curated set of value focused names through the 34 high quality undervalued stocks.
- For readers who care about income as much as growth narratives, filter for companies offering robust payouts using the 4 dividend fortresses.
- If capital protection sits high on your checklist, concentrate on financially resilient operators by running the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com