


EN
Is Earnings And Cloud Partnerships Altering The Investment Case For F5 (FFIV)?
- F5 reported fourth quarter revenue of US$917.43 million and full year revenue of US$3.42 billion, alongside fiscal 2027 guidance that points to 8% to 9% revenue growth, while also outlining new collaborations with Oracle Cloud Infrastructure and Telenor AI Factory.
- The Oracle and Telenor arrangements position F5’s security and traffic management software more deeply inside large cloud and AI infrastructures, which directly ties product adoption to customers’ application security and sovereign AI requirements rather than one-off hardware refresh cycles.
- We will look at how F5’s investment narrative is shaped by its revenue guidance and deeper integration into Oracle Cloud Infrastructure.
Scan beyond F5 in this earnings plus AI-infrastructure story by sizing up hand-picked 53 AI infrastructure stocks that could also be plugged into major cloud and sovereign AI buildouts.
F5 Investment Narrative Recap
To own F5, you need to believe its application security and delivery platform can keep winning workload share as enterprises juggle hybrid cloud, APIs, and AI traffic. The short term swing factor is whether management can turn that complexity into higher software and multi product usage while holding to its FY27 revenue growth guidance of 8% to 9%.
The biggest near term risk remains margin pressure and mix. F5 is already flagging lower non GAAP gross margin on component costs, and recurring revenue has been growing more slowly than many would like. The latest Oracle and Telenor wins help the narrative, but they do not remove that execution risk.
The planned Oracle Cloud Infrastructure collaboration is the most relevant new data point. F5 intends to bring its web application and API protection directly into Oracle’s cloud environment, which ties its security tools more tightly to customer workloads rather than one off hardware upgrades. For investors evaluating the story, that speaks directly to the recurring usage debate, not just headline bookings.
Operationally, the key question is whether embedding F5 security into OCI can support steadier demand for WAF and API protection while the firm manages component cost pressure and targets upper single digit growth. That integration also sits alongside deployments like Telenor AI Factory, so execution across both hyperscale and sovereign AI projects will likely shape future catalysts and perceived risk.
F5's current analyst playbook points to revenues of US$4.2b and earnings of US$1.0b by 2029, based on a projected 8.1% yearly revenue growth rate and a move in earnings from US$726.5m today to the US$1.0b consensus, which implies an increase of roughly US$273.5m over that period.
Uncover why F5's fair value indicates a 36% potential upside to its current price, which could narrow quickly.
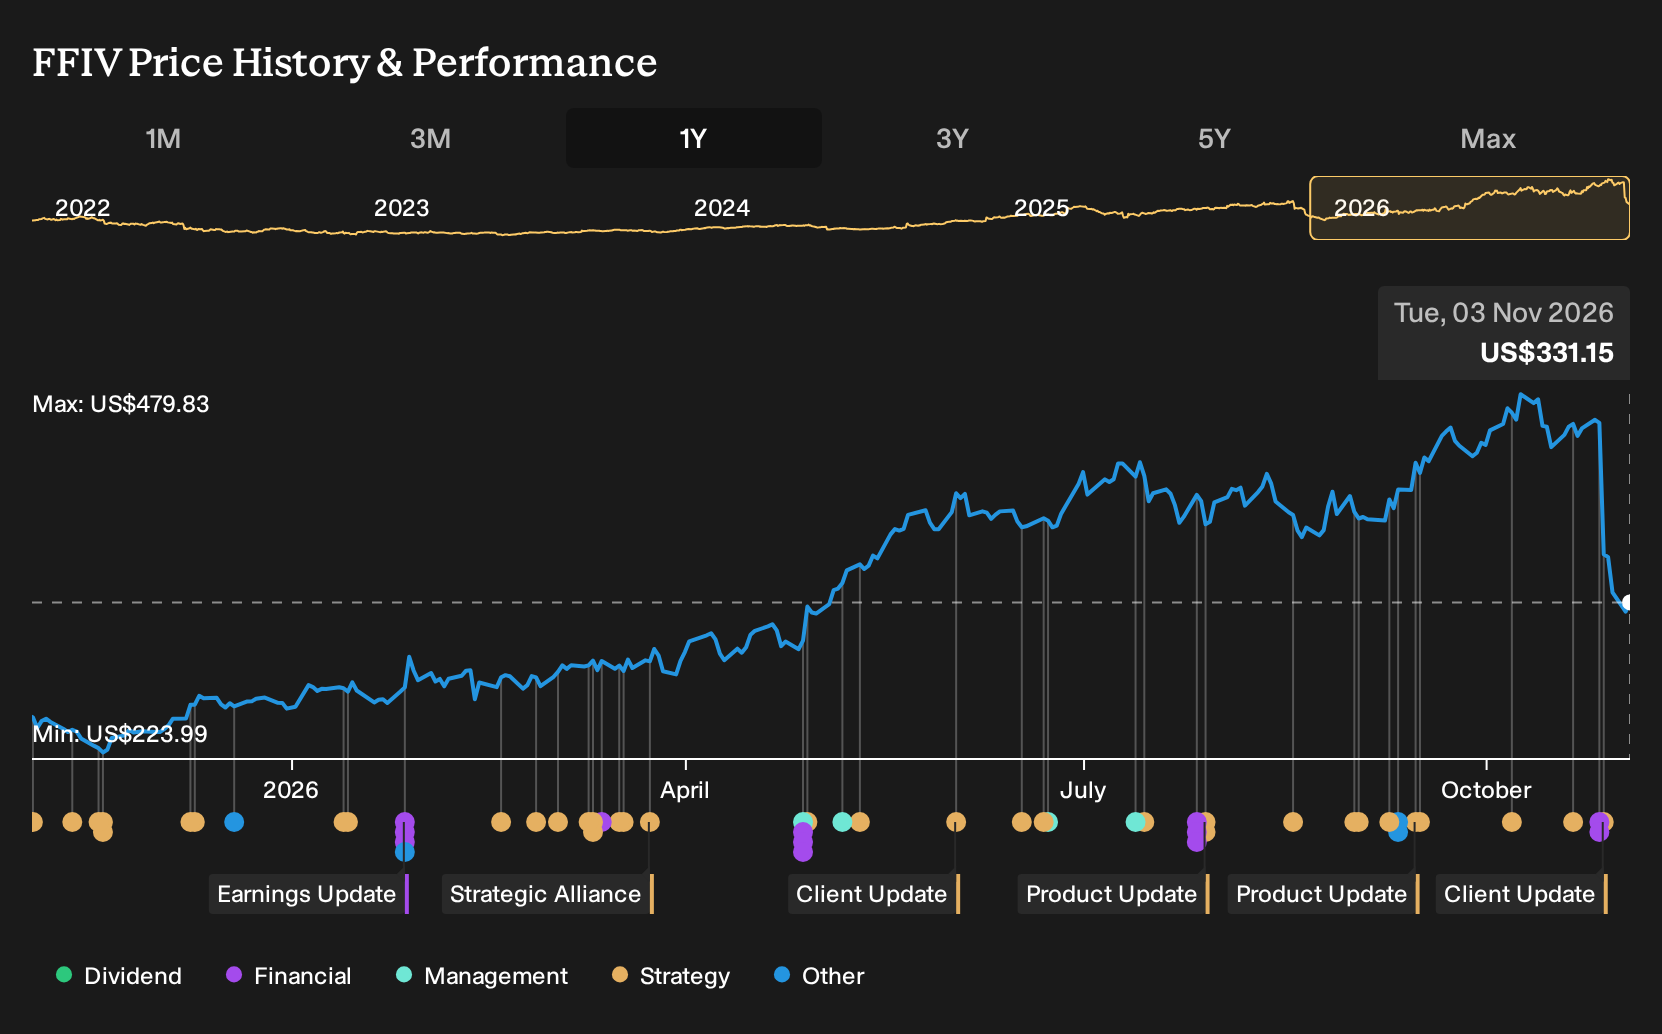
Exploring Other Perspectives
One alternate view around F5 leans heavily on AI security as a potential upside swing factor. The most optimistic analysts were already pencilling in about US$4.3b of revenue and US$1.2b of earnings by 2029, compared with roughly US$4.2b and US$1.0b in the baseline. Those forecasts came before the Oracle Cloud Infrastructure news, so you may want to compare both sets of expectations and decide which feels closer to your own read of the story.
Explore 2 other F5 fair value estimates, including one that suggests there may be as much as 36% potential upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your F5 research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for F5. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate F5's overall financial health at a glance.
Looking For More Ideas Beyond F5?
If the F5 story has sharpened your thinking about risk, balance sheets, and upside, it can be useful to compare it with other listed businesses that fit clear, transparent criteria.
- If capital preservation matters most to you, a good next step is to review 30 resilient stocks with low risk scores that score well on stability metrics and lower observed risk factors.
- If you prefer resilient cash generation and cleaner finances, focus on companies in our list of solid balance sheet and fundamentals (23 results) to see which businesses pair manageable debt with solid fundamentals.
- If you are hunting for underfollowed opportunities with strong underlying numbers, scan through the 19 high quality undiscovered gems that rarely make headlines but meet strict quality tests.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com