


EN
Did Expanded Holiday Events Just Shift United Parks & Resorts (PRKS) Investment Narrative?
- United Parks & Resorts recently outlined expanded 2026 Christmas offerings at SeaWorld and Busch Gardens, including new shows, a drone light display, and family holiday events that are bundled into standard admission and scheduled to run through early January 2027.
- The holiday program leans on seasonal content like the Lights of Wonder drone show and Baby Shark themed experiences, which can test how effectively United Parks & Resorts converts event driven visitation into higher in park spending and more resilient winter demand.
- The next step is to consider how United Parks & Resorts' investment narrative interacts with its expanded holiday event slate, particularly the drone show.
Scan beyond United Parks & Resorts and line up comparable experience driven operators using the curated 19 high quality undiscovered gems as a starting universe for your watchlist.
United Parks & Resorts Investment Narrative Recap
To own United Parks & Resorts, you need to believe the park portfolio can turn fairly modest revenue growth into healthier earnings through higher in park spending, better marketing and tighter cost control. The expanded 2026 Christmas slate looks directionally helpful for attendance and deferred revenue, but, on its own, does not change the short term earnings picture.
The key near term swing factor remains execution on marketing and pricing so that prepaid demand and seasonal events translate into actual visits and spend, while operating costs do not erode margins further. The biggest current risk is that softer attendance and higher expenses persist, which would keep profit margins under pressure and limit cash generation.
The most relevant move here is the decision to bundle the expanded Christmas offerings, including the Lights of Wonder drone show, into standard admission through early January 2027. That keeps the focus on volume and in park monetization rather than one off upcharges. This matters for how the holiday period feeds into forward bookings and deferred revenue.
If these events help fill the parks in what is usually a seasonally choppy window, they can support the existing catalyst of a growing base of prepaid visits and in park spending, even while broader attendance has recently declined. The operational test for investors is whether these layered experiences, alongside digital and food and retail upgrades, show up in steadier guest trends without materially lifting already rising operating costs.
United Parks & Resorts' consensus story connects the holiday build out to a broader earnings and valuation bridge. Analysts are working from revenue growth of 3.1% a year and current earnings of US$133.6 million, with a forecast for US$173.3 million of profit on US$1.8b of revenue by 2029. That implies an earnings increase of about US$39.7 million by the forecast year, a change that supports the current 2029 estimates.
Uncover why United Parks & Resorts' fair value indicates a 45% potential upside to its current price before that discount narrows further.
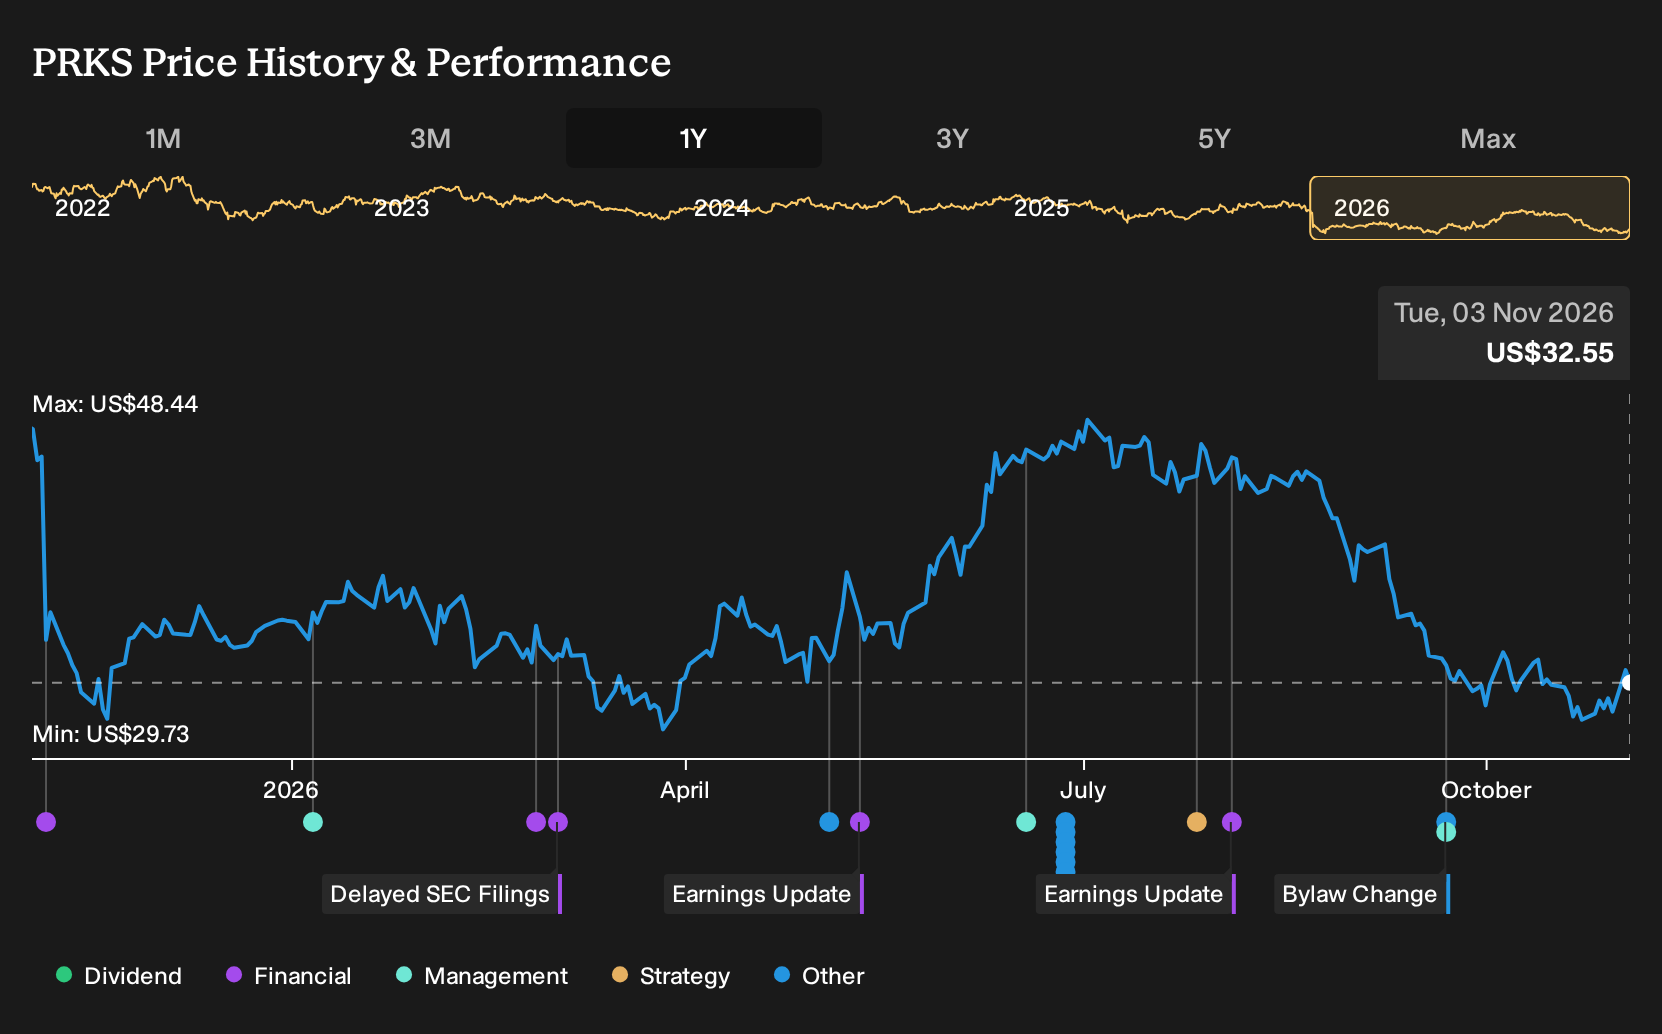
Exploring Other Perspectives
Some of the lowest ranked analysts see the biggest risk in United Parks & Resorts as simple attendance drag. Their pre news forecasts called for only 2.2% annual revenue growth and earnings of about US$138.1 million by 2029. You can read those assumptions as a far more cautious story that fresh holiday content might eventually challenge.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your United Parks & Resorts research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parks & Resorts. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate United Parks & Resorts' overall financial health at a glance.
Looking For More Investment Ideas Beyond United Parks & Resorts?
If the United Parks & Resorts story has you thinking about how different business models handle seasonality, pricing power and balance sheet strength, it can help to widen the lens and compare it with other listed operators across sectors.
- If you want potential upside with a margin of safety, start by scanning companies that currently screen as 34 high quality undervalued stocks that pair quality fundamentals with discounted prices.
- If resilience matters most to you, focus on businesses with conservative finances by filtering through the list of solid balance sheet and fundamentals (23 results) to see which stocks carry lower balance sheet risk.
- If income is a key part of your plan, concentrate on reliable cash payouts using the 4 dividend fortresses and see which higher yielding companies align with your risk tolerance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com