


EN
Western Midstream Partners (WES) Could Be 12% Undervalued As Earnings Views Improve
Analysts have nudged earnings projections higher for Western Midstream Partners (WES), with Wall Street now looking for quarterly profit of $0.89 per share and stronger revenue ahead of the upcoming report.
Western Midstream Partners’ unit price has eased in recent weeks, with the share price slipping 3.2% over the past week and 4.9% over the last 90 days, even as the year-to-date share price return sits at 10.5% and the 5-year total shareholder return reaches 210.4%. This pattern suggests that short-term momentum has cooled while longer-term investors have still seen substantial gains ahead of the upcoming earnings update.
Scan for other energy infrastructure plays that show similar earnings momentum and pricing gaps to Western Midstream Partners by reviewing our curated list of list of solid balance sheet and fundamentals (23 results)
Western Midstream Partners has cooled off in the last few weeks after a strong multi year run, yet analyst targets and earnings estimates still sit above the current price. Is most of the upside already booked, or is the market leaving more on the table?
Most Popular Narrative: 11.7% Undervalued
Western Midstream Partners last closed at $43.87, while the most followed narrative anchors fair value at $49.69. The current price sits below that framework and puts the focus on how basin projects and contracts might bridge that gap.
Investment in large Delaware Basin projects such as the Pathfinder produced water pipeline and the North Loving II gas processing train, which are moving toward expected 2027 in service dates, is described as adding fee based capacity that could affect Western Midstream Partners’ revenue and adjusted EBITDA as volumes move through those assets.
See why 42 investors see Western Midstream Partners as 12% undervalued.
Result: Fair Value of $49.69 (UNDERVALUED)
Still, the whole Western Midstream Partners story can wobble if big capital projects like Pathfinder or North Loving II miss budgets or fail to secure strong long term volumes, or if weaker producer activity in basins such as the Delaware and Powder River undercuts throughput and leaves those assets underused.
Find out about the key risks to this Western Midstream Partners narrative.
Another View: Western Midstream Partners Through The P/E Lens
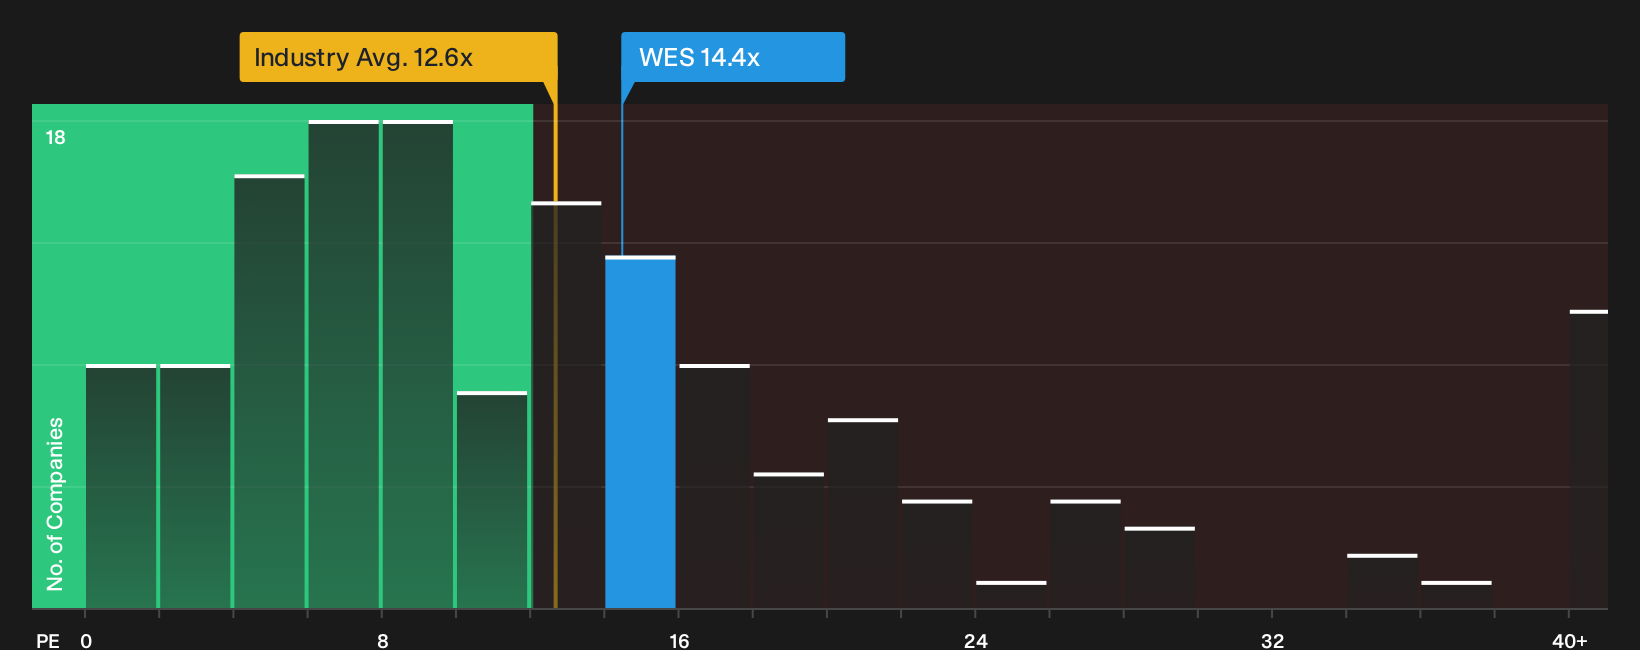
The SWS fair value framework points to Western Midstream Partners trading at a discount, yet the P/E picture is less generous. WES changes hands at 14.4x earnings compared with 12.6x for the wider US Oil and Gas group, while its fair ratio sits higher again at 19.6x. That mix points to a stock priced above the sector but below where the fair ratio suggests the multiple could drift over time, which raises a simple question for investors. Is that gap a comfort buffer or a sign that expectations already bake in a lot of good news?
Our valuation breakdown steps through this P/E gap versus both peers and the fair ratio, and unpacks what it might mean for upside and downside risk in practical terms for Western Midstream Partners holders, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings about Western Midstream Partners after all this. If the blend of flagged risks and upside drivers has you on the fence, move quickly and stress test the story yourself with the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Western Midstream Partners?
If Western Midstream Partners has sharpened your focus on earnings quality and valuation gaps, consider broadening your watchlist and pressure testing your thinking across fresh opportunities.
- Stack the odds toward quality by reviewing a 30 resilient stocks with low risk scores that aims to prioritise resilient balance sheets and steadier return profiles.
- Hunt for mispriced opportunities by scanning a 34 high quality undervalued stocks that focuses on strong fundamentals trading below intrinsic value estimates.
- Target consistent portfolio cashflow by zeroing in on a 4 dividend fortresses that concentrates on higher yielding companies with sturdy financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com