


EN
Regency Centers (REG) Heads Into Earnings With Raised NOI Outlook, Is It Still 11% Undervalued?
Regency Centers (REG) is in focus ahead of its third quarter 2026 earnings report on November 5, as investors consider its raised same property NOI guidance along with expectations for higher revenues and funds from operations.
Recent trading tells a mixed story for Regency Centers, with a roughly 5% decline in the 90 day share price return contrasting with a 4.99% 30 day share price gain and a 10.61% year to date share price return. The 1 year total shareholder return of 13.24% and 3 year total shareholder return of 41.02% indicate that, despite some recent cooling, longer term momentum has been positive as investors weigh the raised same property NOI outlook and upcoming third quarter results.
Scan for other retail REITs showing similar leasing strength and earnings catalysts to Regency Centers with our hand picked 30 resilient stocks with low risk scores.
The share price has climbed back after a softer 90 day stretch, just as expectations build into earnings. For Regency Centers, is that enough to justify entering a position now instead of waiting for a pullback and a lower valuation?
Most Popular Narrative: 11% Undervalued
Regency Centers closed at $75.17 against a most-followed narrative fair value of $84.83, which frames the current earnings setup as pricing in a discount even after the recent rebound into the third quarter report.
Regency Centers' in-process development and redevelopment pipeline of about US$680 to US$700 million at blended returns of roughly 9%, along with an expected US$400 million of new starts in 2026, gives the company a visible source of incremental rent and fee income that can add to revenue and earnings beyond what existing centers already produce.
See why 7 investors see Regency Centers as 11% undervalued.
Result: Fair Value of $84.83 (UNDERVALUED)
Still, tenant bankruptcies or weaker demand for Regency Centers' US$680 to US$700 million development pipeline could quickly challenge the view that the shares are 11% undervalued.
Find out about the key risks to this Regency Centers narrative.
Another View On Regency Centers' Valuation
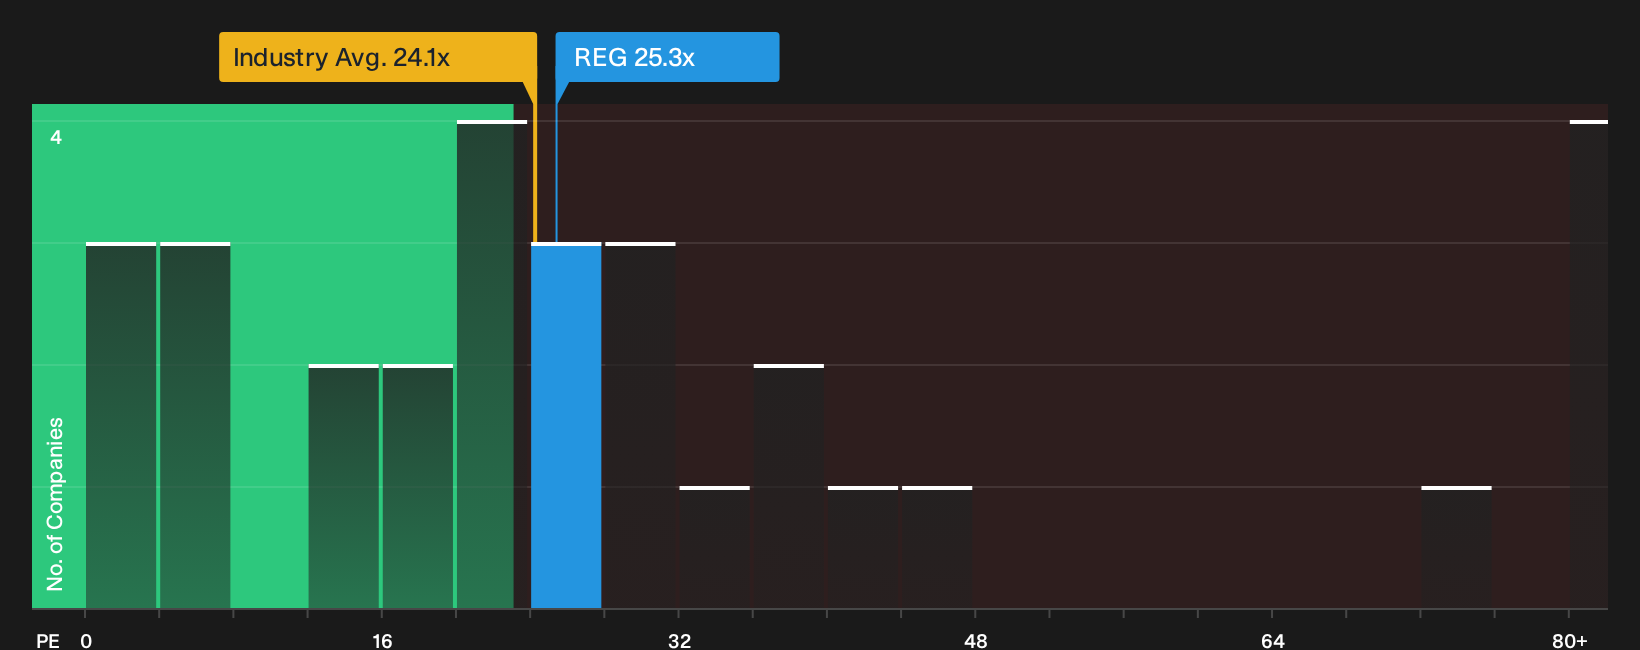
Multiples tell a different story than the 11% undervalued fair value. Regency Centers trades on a P/E of 25.3x, richer than the US Retail REITs industry at 24.1x, yet below its own fair ratio of 31.2x. That mix points to both cushion and risk. Which side do you think dominates?
See what the numbers say about this price in our valuation breakdown, then pressure test your own assumptions against the See what the numbers say about this price — find out in our valuation breakdown..
For more context on how Regency Centers stacks up versus peers and its own history, the
Next Steps
Mixed views on Regency Centers so far. Act while the data is fresh, weigh the positives against the concerns, and ground your decision in the underlying 3 key rewards and 2 important warning signs.
Looking for more Regency Centers style investment ideas?
Do not stop your research with Regency Centers. The market always offers other angles, and the right watchlist today can shape tomorrow's decisions.
- Target stronger downside protection by scanning a 30 resilient stocks with low risk scores that already screens for resilience instead of leaving risk checks to guesswork.
- Hunt for quality at a discount by running a 34 high quality undervalued stocks that filters for fundamentals first so price tags actually mean something.
- Prioritize reliable income by reviewing a curated 4 dividend fortresses that highlights yield potential alongside underlying financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com