


EN
Flowserve (FLS) Could Be 11% Undervalued Following Raised Earnings Guidance
Flowserve (FLS) has caught investor attention after its latest earnings update, where strong third quarter margin execution and higher full year earnings guidance coincided with a reduced sales outlook tied to Middle East project delays.
At around US$81.03, Flowserve’s recent 7 day share price return of 14.38% and 30 day share price gain of 8.96% point to building momentum after the Q3 update and guidance change. A 5 year total shareholder return of 162.94% shows that longer term holders have already seen substantial value creation.
Scan how Flowserve’s renewed earnings guidance and margin story compares with other industrials showing similar momentum in our hand picked 34 high quality undervalued stocks list.
Flowserve appears to be a solid industrial operator with improving profitability and updated earnings guidance, yet the share price has already moved sharply higher on the news. Are you paying a premium for quality or still getting it at a discount?
Most Popular Narrative: 11% Undervalued
Against Flowserve’s last close of $81.03, the most followed narrative pegs fair value at $91.20. This frames the recent share price jump as only part of the story rather than the end of it.
Ongoing work under the Flowserve Business System, including 80/20 portfolio actions, footprint realignment and commercial discipline, is aimed at pushing adjusted operating margin from the roughly 16% expected in 2026 toward the stated 20% target for 2030. This would directly support earnings and free cash flow.
See why 38 investors see Flowserve as 11% undervalued.
Result: Fair Value of $91.20 (UNDERVALUED)
Still, pressure on Middle East activity and any disappointment against ambitious margin targets could quickly challenge the idea that Flowserve is meaningfully undervalued.
Find out about the key risks to this Flowserve narrative.
Another View: Flowserve Through The P/E Lens
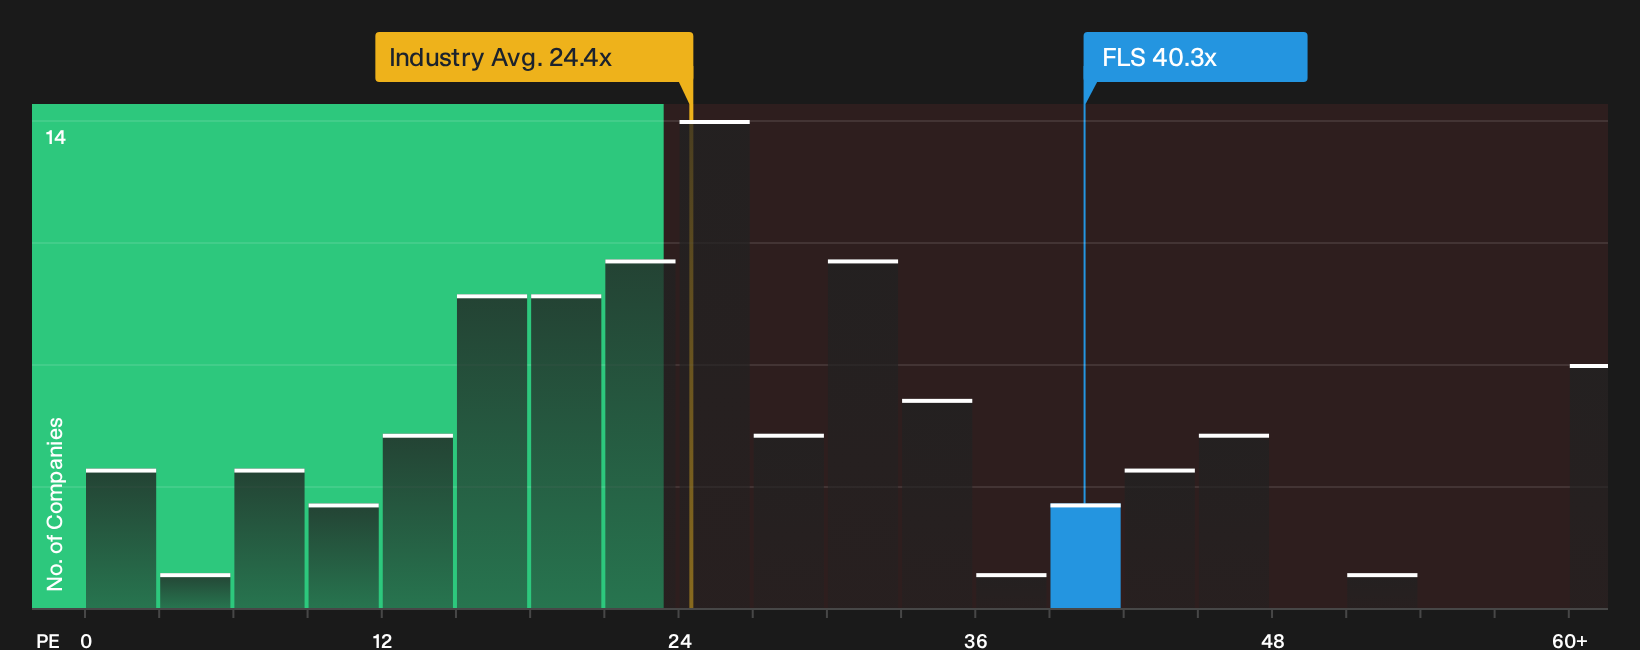
Look at Flowserve through the simple P/E lens and the picture is less forgiving. The stock trades on about 40.3x earnings, compared with roughly 24.4x for the US Machinery industry and 23.3x for peers. That is also in line with its own fair ratio of 40.3x.
This gap points to meaningful valuation risk if earnings forecasts or sentiment cool. The premium can persist while growth expectations stay strong. However, how comfortable are you paying well above sector and peer multiples for this story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about Flowserve after all that. Get to the numbers quickly, weigh the upside against the weak spots, and pressure test the story with 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Flowserve?
If Flowserve has sharpened your focus, do not stop here. Fresh ideas often come from comparing similar quality stories across different parts of the market.
- Hunt for mispriced potential where quality and valuation meet by scanning our 19 high quality undiscovered gems that many investors may not be watching yet.
- Prioritise resilience by filtering for companies with strong finances through the list of solid balance sheet and fundamentals (24 results) and see which businesses look better equipped for shocks.
- Target steadier income streams by reviewing the 4 dividend fortresses and weigh dependable payouts alongside the rest of your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com