


EN
Ilkka Oyj (HLSE:ILKKA) Stock Faces Q3 Earnings Pressure And Dividend Strain
Ilkka Oyj shares closed at €3.56 on 3 November, with the stock drifting over the past month even as fresh Q3 2026 figures hit the tape. Traders focused on the sharp comedown in quarterly earnings per share to €0.01 after a strong second quarter. Long term investors will likely be less fixated on that single soft print and more on the bigger issue, which is valuation strain. The media group now trades on a P/E multiple well above peers while carrying a dividend yield above 7% that current earnings and cash flow have difficulty supporting.
Like the income appeal of Ilkka Oyj but worried that a rich P/E and dividend strain point to a value trap risk instead of a cash backed opportunity? Compare this setup with our 196 high quality undervalued stocks to see companies that pair stronger balance sheets with more robust earnings support for their payouts.
Q3 2026 Ilkka Oyj Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): €9.486 million vs. €9.008 million (up approximately 5.3%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): €0.228 million vs. €1.316 million (down approximately 82.7%)
- Basic EPS (Q3 2026 vs Q3 2025): €0.01 vs. €0.051892 (down approximately 80.7%)
- Trailing 12-Month Net Profit Margin (latest year vs prior year): 12.1% vs. 10.5% (improved by 1.6 percentage points)
Tired of wading through dense tables and raw figures just to make sense of Ilkka Oyj? Get a clear visual view of its valuation, earnings power and recent performance all in one place with our company report for Ilkka Oyj.
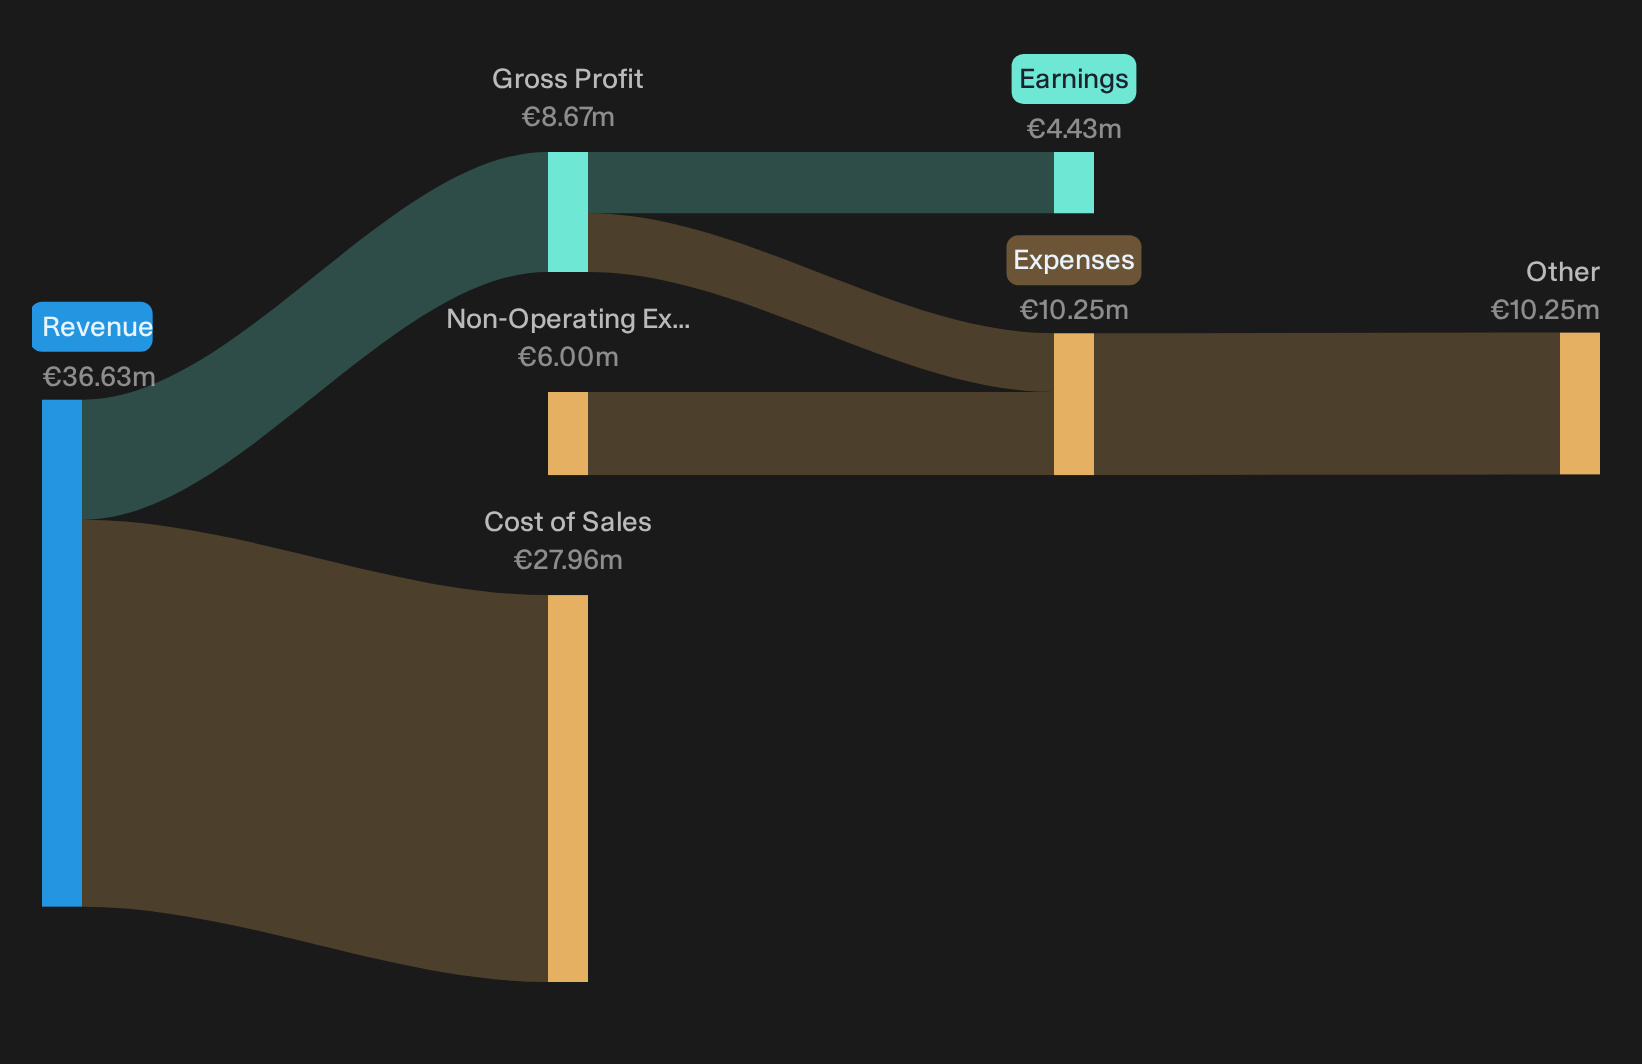
Ilkka Oyj: Testing The Bullish Transformation Story
For anyone backing Ilkka Oyj as a digital transformation story, the latest figures send a mixed but not hopeless signal. Revenue of €9.486 million is higher than the prior €9.008 million, so clients are still spending with the group. The trailing 12 month net profit margin of 12.1% compared with 10.5% also points to healthier profitability over a longer window. That backdrop gives some support to the idea that a more digital, service driven model can generate decent earnings power when viewed beyond a single quarter.
Ilkka Oyj: Earnings Volatility Fuels Bearish Concerns
The bearish angle focuses on fragility, and Q3 2026 adds fuel to that worry. Net income excluding extra items dropped from €1.316 million to €0.228 million and basic EPS fell from €0.051892 to €0.01. Short term profitability looks very choppy. With the share down about 9% over 90 days, the market reaction lines up with that pressure. For a group pitching integrated digital and martech services, such swings raise questions about how resilient underlying demand and execution really are when conditions get tougher.
Are analysts backing Ilkka Oyj’s digital transformation story or fading it after this volatility in earnings quality? Check the consensus price target analysis for Ilkka Oyj.
Hunt For Mispriced Earnings Power
Ilkka Oyj’s latest quarter shows how choppy earnings can complicate reading what the current share price reflects. The real opportunity is spotting stocks that could be undervalued before the market closes that gap.
- Company 1 - 42% below our estimate - use an expanded manufacturing and supply chain build out to support higher margin protective films and installation services across multiple distribution channels.
- Company 2 - 45% below our estimate - build an integrated complex care network that adds higher acuity services while rolling out new facilities supported by an AI enabled operating model.
- Company 3 - 38% below our estimate - shift toward higher fee private market strategies and scale real assets as new wealth products and co investments grow fee earning assets under management.
Three companies from the same screener. Open all 196 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com