


EN
How Raised Earnings Guidance Will Impact Popular (BPOP) Stock
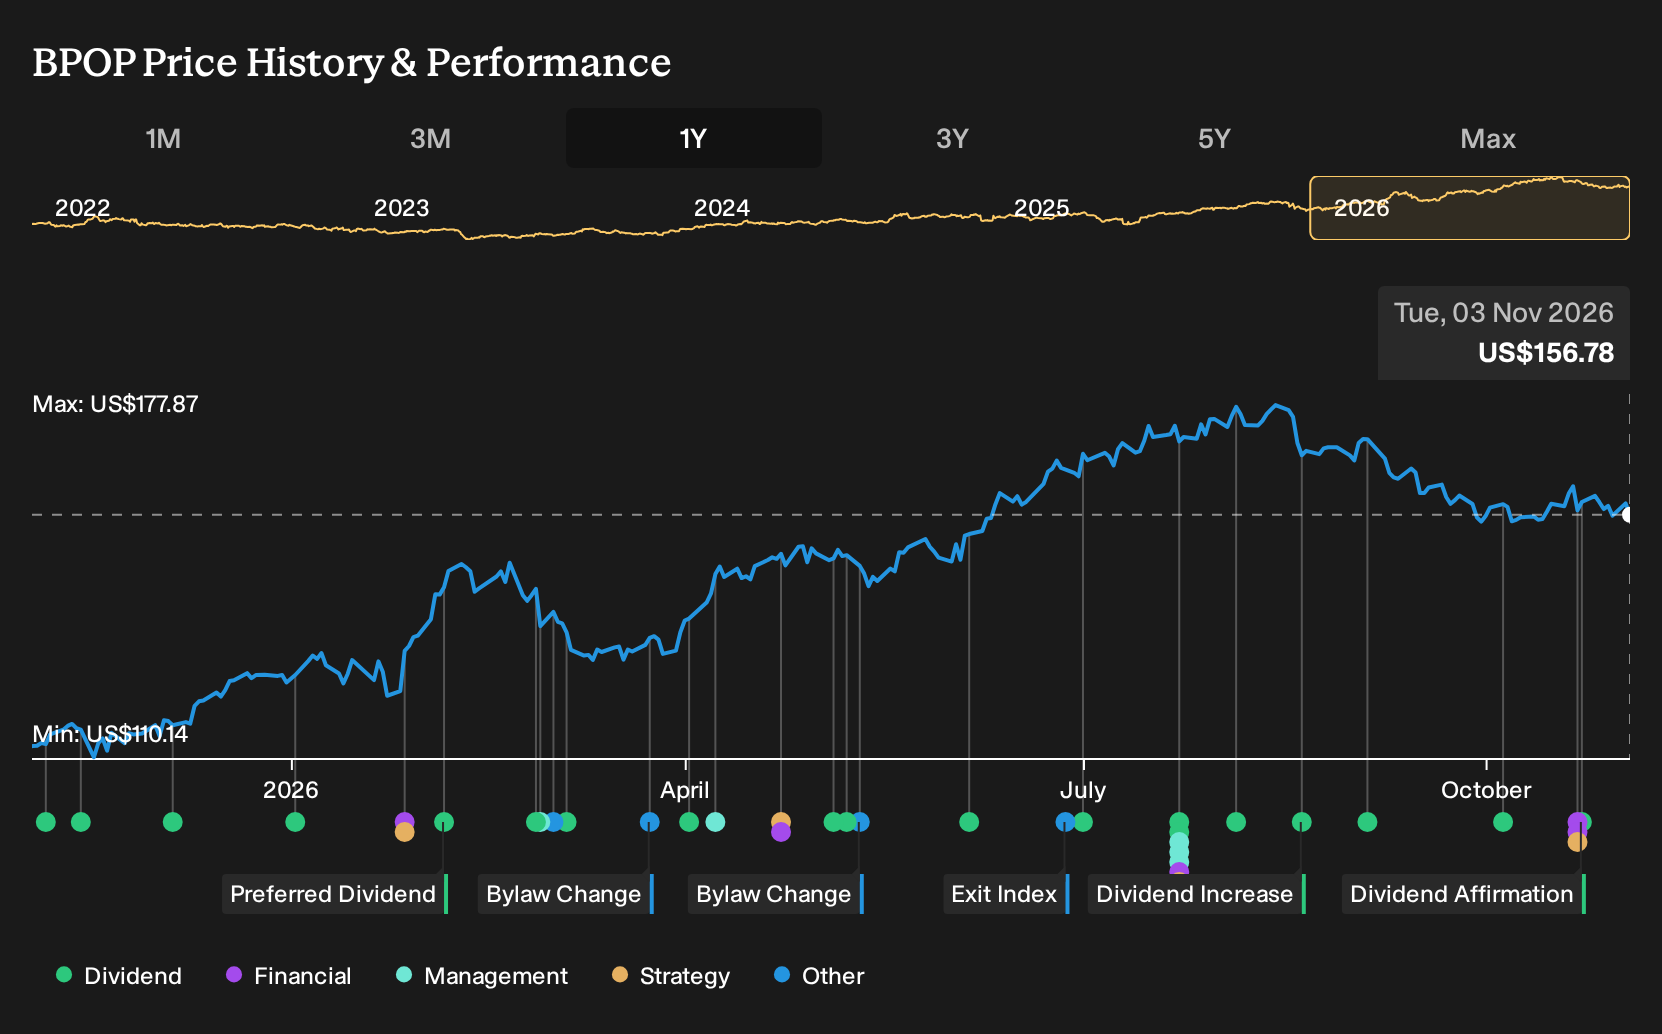
- Popular, Inc. reported third quarter 2026 net interest income of US$698.93 million and net income of US$266.33 million, alongside higher earnings per share for both the quarter and first nine months of the year, and the board affirmed a US$0.90 quarterly dividend payable on January 4, 2027.
- Management paired the stronger reported profitability with an updated 2026 outlook that now points to around 8.5% net interest income expansion for the full year. The company also completed a US$179 million buyback tranche that reduced the share count by 1.66% during the third quarter.
- The focus now turns to how Popular’s stronger third quarter earnings and higher full year net interest income guidance influence its broader investment narrative.
Scan how Popular’s latest dividend affirmation and higher net interest income outlook compare with other income-focused banks by reviewing the hand picked 4 dividend fortresses in the same space.
Popular Investment Narrative Recap
To own Popular, you need to believe the bank can keep turning its Puerto Rico and U.S. franchises, plus its digital and efficiency programs, into steady earnings while managing local economic and credit swings. The raised 2026 net interest income outlook points to a firmer near term earnings engine, with execution on cost savings still a key short term catalyst.
The main near term watchpoint sits on credit quality and loan growth in a concentrated Puerto Rico footprint. Third quarter net charge offs of US$72.94 million, higher than a year ago, keep asset quality firmly in focus. If credit costs trend higher from here, that would work against the improved income guidance story.
The most relevant update for that story is Popular’s guidance for about 8.5% net interest income expansion in 2026, compared with the prior 5% to 7% range. This uplift sits on top of reported net interest income of US$698.93 million in the third quarter and US$2.06b for the first nine months of 2026.
For you as a shareholder, this sharper income outlook ties directly into the existing catalysts around efficiency programs and a capital rich balance sheet. Stronger net interest income supports Popular’s ability to fund digital investment and absorb higher credit costs if needed, while still leaving room for dividends and buybacks to influence per share results.
Popular's narrative projects US$3.9b revenue and US$1.1b earnings by 2029. This assumes revenue growth of 8.8% a year and an earnings increase of roughly US$132m from current earnings of US$967.7m.
Discover how Popular's fair value reflects a 25% potential upside to its current price before that gap closes.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community range from about US$196.70 to roughly US$387.81, which shows how far apart views on Popular can be. Consider these alongside rising charge offs, Puerto Rico concentration risk and ongoing dividend and buyback activity, then explore more community viewpoints before forming your own stance.
Explore another Popular fair value estimate, including one that suggests as much as 147% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent judgment.
- A great starting point for your Popular research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Popular. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Popular's overall financial health at a glance.
Looking for more investment ideas beyond Popular?
If Popular’s mix of dividends, buybacks and credit risk trade offs has you thinking more broadly about where to put fresh capital, use this moment to widen your watchlist with other opportunities that fit your preferred style.
- If you want potential mispricing paired with quality fundamentals, start with a curated set of 19 high quality undiscovered gems that may not yet be on most investors' radar.
- For investors who care most about resilience and capital preservation, focus your research on a 30 resilient stocks with low risk scores that screens for durability first.
- When balance sheet strength is non negotiable, filter for companies on the list of solid balance sheet and fundamentals (24 results) and use that as a base list for deeper fundamental work.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com