


EN
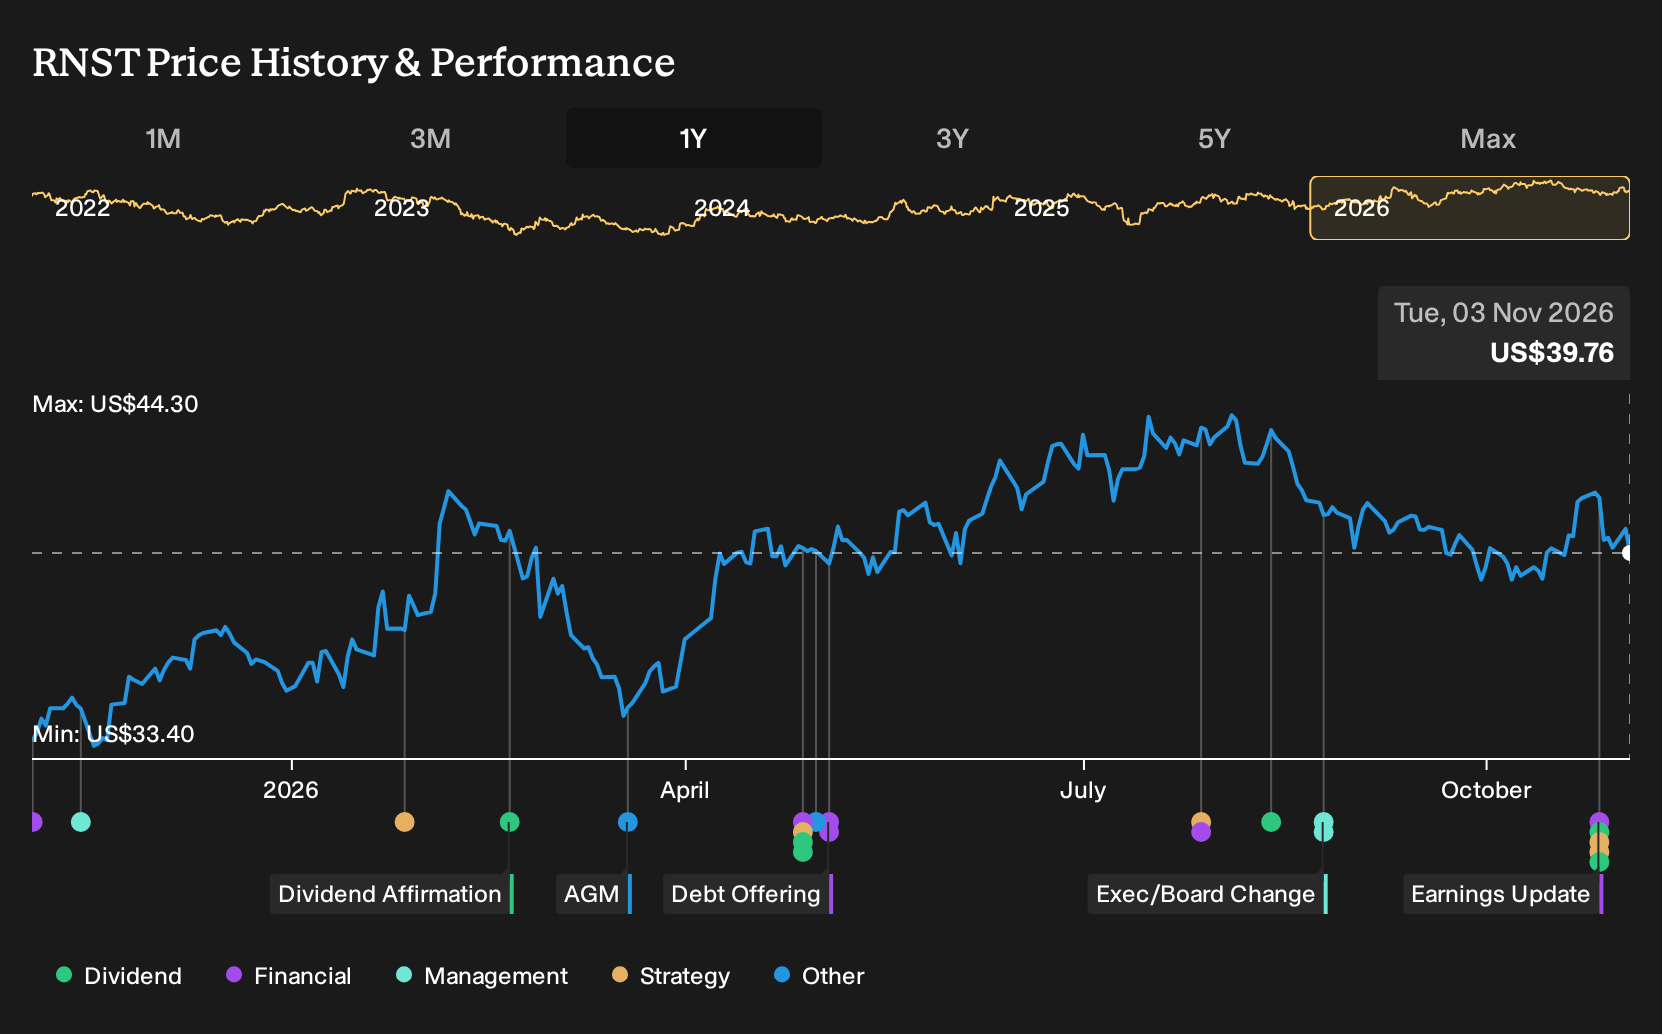
How Strong Earnings Will Impact Renasant Stock Investors
- Renasant Corporation reported third quarter 2026 net interest income of US$223.69 million and net income of US$78.95 million, along with higher basic and diluted earnings per share from continuing operations compared with the prior year. The company also outlined nine-month results that showed higher net interest income and earnings compared with the same period in 2025.
- Management paired these earnings with an updated capital return plan, including a new share repurchase authorization of up to US$175 million and the completion of a prior buyback program that retired more than 5% of shares. Net loan charge-offs increased compared with the third quarter of 2025.
- This article examines how Renasant's investment narrative is influenced by stronger earnings in conjunction with the newly authorized US$175 million buyback program.
Scan beyond Renasant's earnings and fresh buyback authorization by lining up its profile against list of solid balance sheet and fundamentals (24 results) to see how other businesses pair profitability with balance sheet strength.
Renasant Investment Narrative Recap
To own Renasant, you need to be comfortable with a regional bank that relies on steady loan and deposit growth in the Southeast, tighter costs and a growing mix of fee income. The latest quarter delivered higher net income and earnings per share, but also higher net loan charge offs, so credit quality remains in focus.
The key short term catalyst is whether Renasant can keep earnings resilient while credit costs stay manageable as Southeast commercial real estate and traditional lending remain under pressure. The biggest risk is that higher charge offs spread beyond current pockets of stress and start to erode that improved profitability.
The new US$175 million buyback authorization running through October 2027 is the clearest operational signal tied to this earnings release. It follows completion of a prior program that retired more than 5% of shares and it keeps capital management firmly in play alongside the existing dividend and loan growth ambitions.
For you, that means execution on three fronts matters most. Renasant has to keep generating enough earnings to comfortably fund repurchases, absorb elevated charge offs of US$10.0 million this quarter and still support measured balance sheet expansion, or the buyback could end up competing with core franchise investment and risk control.
Renasant's current analyst narrative points to revenue of US$1.2b and earnings of US$367.6 million by 2029. That profile rests on 5.4% yearly revenue growth and an earnings increase of about US$53.5 million from US$314.1 million today.
Uncover how Renasant's fair value indicates a 20% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
Fair value estimates for Renasant from 2 private investors in the Simply Wall St Community span roughly US$47.7 to US$66.1 per share, so opinions already stretch meaningfully apart. Set those views against rising net income, a fresh US$175 million buyback plan and higher net charge offs, and you get plenty of room for differing conclusions.
Explore another Renasant fair value estimate, including one that suggests as much as 66% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Renasant research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Renasant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renasant's overall financial health at a glance.
Looking For More Renasant Investment Alternatives?
If Renasant's story has sharpened your thinking about banks and balance sheets, you can use that same lens to scan a wider field of opportunities with the Simply Wall St Screener. Start with a few focused filters so you are comparing businesses on the quality signals that matter most to you.
- Prefer to keep risk in check while still staying in equities? Shortlist companies screened for resilience with a 30 resilient stocks with low risk scores to see which ones have profiles that may suit a more cautious approach.
- Hunting for quality at a sensible entry point? Line up companies that currently look attractively priced using the 34 high quality undervalued stocks and see which fundamentals appeal most to you.
- Want holdings that can potentially complement Renasant with steadier financial footing? Compare its metrics against a list of solid balance sheet and fundamentals (24 results) to see which other businesses pair robust balance sheets with underlying fundamentals you rate highly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com