


EN
Semtech (SMTC) Router Update Puts Valuation Focus Back On A Bullish Narrative
Semtech (SMTC) just put fresh attention on its AirLink 5G routers, rolling out new resilient communications features for public safety fleets that meet updated FIPS 140-3 security standards through a software upgrade.
For investors watching the tape, Semtech’s latest router update lands after a sharp reset in momentum. The stock’s 1 day share price return of 4.1% comes after the share price fell 34.6% over 30 days. However, the year to date share price return of 69.3% and a 1 year total shareholder return of 97.8% still point to a strong run that has left expectations and perceived risk elevated.
Pace your exposure to Semtech by comparing it with a curated group of peers that also lean into secure connectivity and resilient infrastructure, starting with 53 AI infrastructure stocks.After a near 35% slide in a month, Semtech now trades at a sizeable discount to both analyst targets and some fair value estimates. Is that markdown simply late recognition of rising risks, or has caution swung too far?
Most Popular Semtech Narrative: 42.1% Undervalued
Against a last close of $127.42, the most followed Semtech narrative anchors fair value at $220.00, which implies a sizeable gap that only closes if the long-term execution story holds together.
Accelerating demand from hyperscale data centers and AI infrastructure is driving robust, multi-year growth across Semtech's high-margin data center business, supported by design wins in advanced optical (FiberEdge), low-power (LPO), and active copper interconnects (CopperEdge/ACC). As data rates move from 400G to 800G and 1.6T, Semtech stands to capture significant revenue and margin expansion from new content per deployment.
See why 42 investors see Semtech as 42% undervalued.
Result: Fair Value of $220.00 (UNDERVALUED)
Still, the Semtech narrative can crack if integration issues around past deals drag on profitability or if weaker mix-driven margins in key segments persist.
Find out about the key risks to this Semtech narrative.
Another View On Semtech’s Valuation
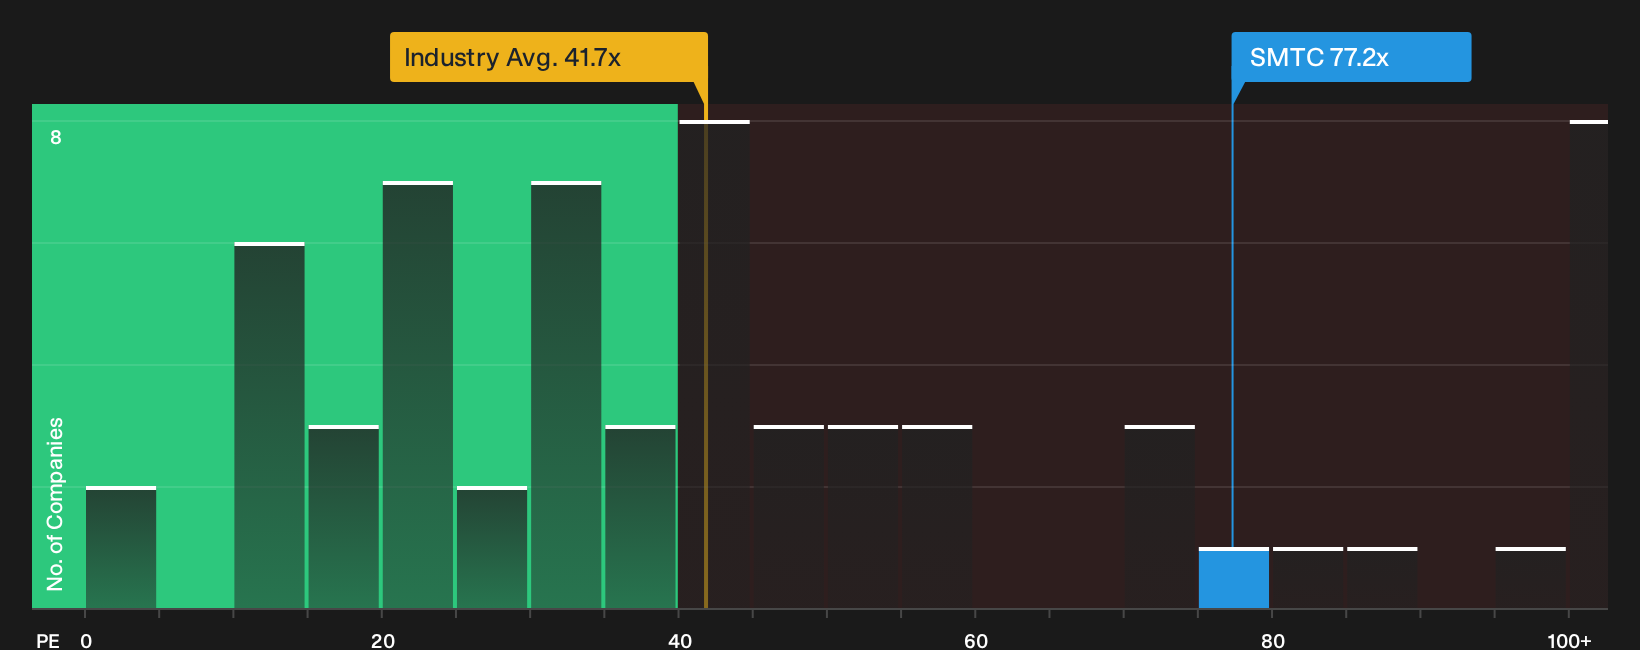
On price multiples, Semtech looks far less forgiving. The shares trade on a P/E of 77.2x against about 41.7x for the wider US Semiconductor group and 41.3x for peers, while the fair ratio sits at 45.6x. That gap points to real valuation risk if sentiment cools.
For investors who prefer to lean on earnings-based markers rather than narratives, this kind of premium raises a simple question: Is the current multiple a cushion for future delivery or a margin of error if the story stumbles, according to See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed views on whether Semtech is overvalued or still attractively priced relative to its risk. Act promptly, verify the financials independently, and then weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Semtech?
Do not stop with Semtech. Broaden your watchlist using focused stock ideas that match different risk levels and income goals so your next move is deliberate, not accidental.
- Target long term value opportunities by scanning a curated pool of businesses trading on compelling fundamentals using the 34 high quality undervalued stocks.
- Prioritise resilience and capital protection by filtering companies with robust financial footing through the 30 resilient stocks with low risk scores.
- Sharpen your income strategy by focusing on companies with substantial yields and staying power using the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com