


EN
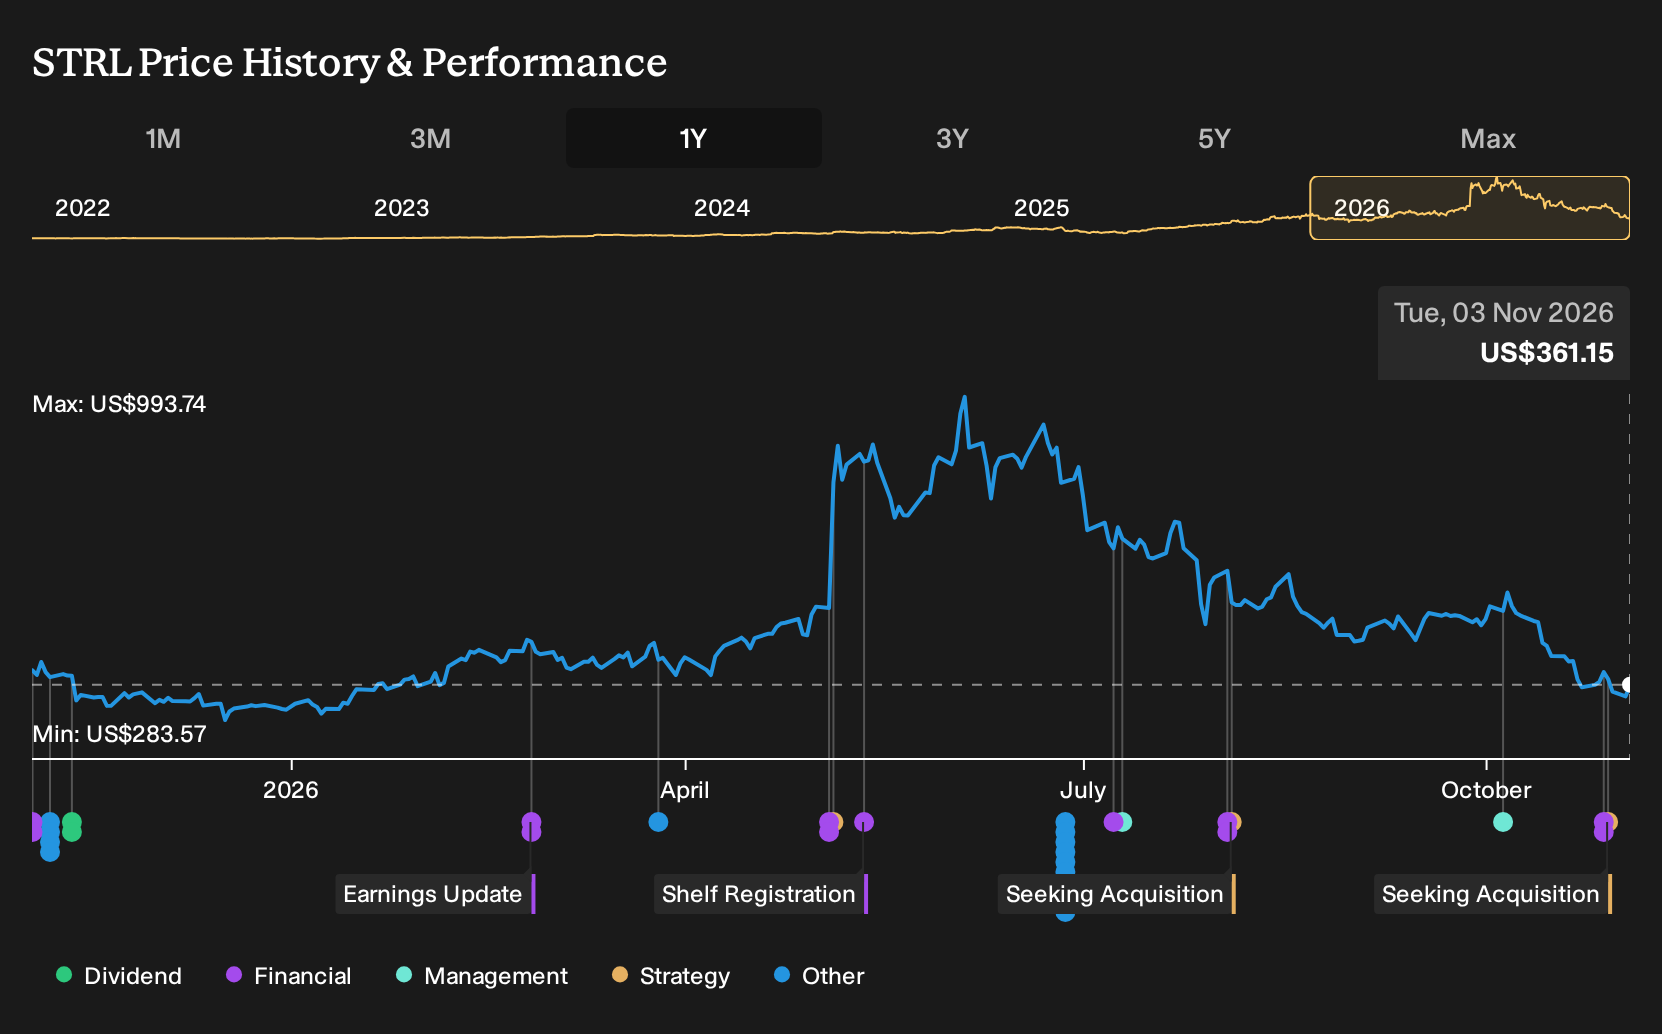
Sterling Infrastructure Stock Is Up 7.7% What's Changed After Earnings Beat
- Sterling Infrastructure reported very strong Q3 2026 results, with US$1.56b in sales, higher earnings, raised full year guidance and a completed US$133.34m share repurchase program.
- Management highlighted the E Infrastructure Solutions segment and a larger backlog tied to AI data centers and semiconductor projects, alongside plans for larger acquisitions supported by a flexible balance sheet.
- The focus now shifts to how Sterling Infrastructure's raised 2026 outlook could influence the longer term investment narrative already in place.
Sterling Infrastructure Investment Narrative Recap
To own Sterling Infrastructure, you need to believe the multiyear backlog in AI data centers and semiconductor projects can translate into sustained, profitable execution. The raised 2026 outlook and Q3 results support that story on paper, with strong sales, higher earnings and a larger pool of mission critical work already contracted or highly probable.
The key near term catalyst is continued conversion of that US$7b plus E Infrastructure pipeline into on time, on budget delivery while managing tight skilled labor and higher capex. The biggest risk remains execution strain if electrician hiring, training and equipment utilization fall behind, which would cap segment growth and pressure returns.
The most relevant fresh data point is Sterling Infrastructure’s upgraded 2026 guidance to US$4.63b to US$4.73b of revenue and US$596m to US$604m of net income. Management explicitly tied that confidence to momentum across the portfolio, including AI data center and semiconductor related contracts that sit inside the E Infrastructure Solutions arm.
For you as an investor, that higher bar raises both opportunity and scrutiny. Delivery against this outlook would support the existing growth narrative and keep E Infrastructure at the center of the story. Any stumble on labor availability, project timing or capex payback would quickly feed back into the same guidance that looks supportive today.
Sterling Infrastructure’s current analyst narrative points to revenues of US$7.6b and earnings of US$1.1b by 2029, based on an assumed 21.0% yearly increase in revenue and an earnings step up of roughly US$545.7m from US$554.3m today.
Uncover how Sterling Infrastructure's fair value indicates a 119% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view focuses on acquisitions rather than backlog. You see Sterling Infrastructure highlighting larger deals today, while the most cautious analysts were, before this news, only assuming revenue of about US$7.2b and earnings of roughly US$972m by 2029. That is a materially lower bar. It illustrates how far opinions can differ, so it can be useful to compare several narratives before deciding how this new acquisition push might reshape the story.
Explore 5 other Sterling Infrastructure fair value estimates, including one that suggests it could be worth just $693.43!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sterling Infrastructure research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Sterling Infrastructure. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sterling Infrastructure's overall financial health at a glance.
Looking for more investment ideas beyond Sterling Infrastructure?
Once you have a view on Sterling Infrastructure, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. That way you can compare the business to peers with different income profiles, risk levels and balance sheet strength rather than viewing it in isolation.
- If capital preservation is a priority, focus on resilience and financial robustness by screening for a 30 resilient stocks with low risk scores that can sit alongside higher volatility holdings.
- For income oriented portfolios, tilt your watchlist toward cash generating companies supported by 4 dividend fortresses that may suit a yield focused approach.
- When hunting for future leaders before broader attention builds, scan a curated 19 high quality undiscovered gems and compare their fundamentals to what you see at Sterling Infrastructure.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com