


EN
Levi Strauss (LEVI) Faces A 22% Fair Value Gap On Cramer Backed Rebound
Jim Cramer recently spotlighted Levi Strauss (LEVI) after the retailer addressed inventory shortages and saw its shares rebound more than 20% following earnings, drawing fresh attention to the stock’s valuation and income profile.
Against that backdrop, Levi Strauss has seen momentum swing back and forth, with a 15.1% 1 month share price return and a 5% 7 day gain offset by a 7.6% decline over 90 days as investors weighed the class action filing, fresh holiday marketing pushes and Cramer’s endorsement. Across that choppy path, the stock’s share price return so far this year and its 1 year total shareholder return of 20.66% suggest sentiment has improved recently. However, the 3 year total shareholder return of 71.43% and slightly negative 5 year figure point to a mixed longer term record.
Spot fresh opportunities alongside Levi Strauss by scanning a hand picked 19 high quality undiscovered gems that may be flying under the radar while sentiment shifts around branded apparel.After a sharp rebound and a mixed longer term track record, the real tension for Levi Strauss now sits in the numbers. Does the current valuation still leave meaningful upside on the table, or has most of it already been claimed?
Most Popular Narrative: 22% Overvalued
Levi Strauss last closed at $22.87, while the most followed narrative on Simply Wall St, according to LunaRodas, puts fair value at $18.72. This frames the current rebound as pricing in more than the narrative suggests.
The framing shift on the U.S. distribution network transition is the most consequential piece of this call, and it’s worth sitting with the actual commitment before assessing how management now talks about it. The plan had been specific: close the Hebron distribution center, consolidate into Groveport, and do it with urgency because “the fact that we have given the intent, given notice, is indicative that we’re serious about it.” A Bank of America analyst cites the number management itself had set: “an immediate $5 million in cost savings per quarter as soon as you shut these parallel DCs down.” Management confirms the Hebron closure happened, on schedule, at quarter’s end. The $5 million in quarterly savings that closure was supposed to trigger has been pushed to 2027, with no month specified.
See why 1 investors see Levi Strauss as 22% overvalued.
Result: Fair Value of $18.72 (OVERVALUED)
Still, the delayed U.S. distribution savings and softer direct to consumer performance at Levi Strauss create clear room for the current narrative to be challenged.
Find out about the key risks to this Levi Strauss narrative.
Another View: What Levi Strauss’s P/E Is Saying
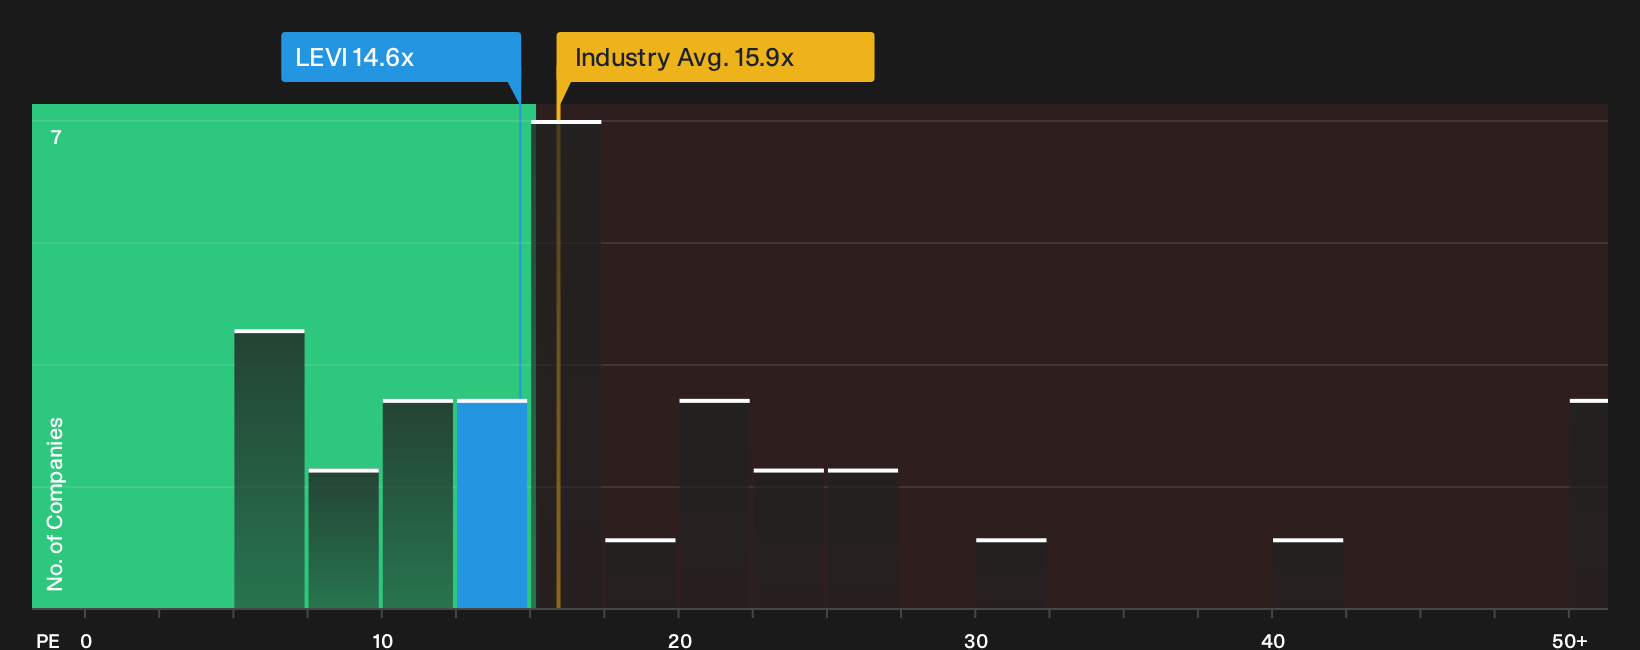
The Simply Wall St narrative pegs Levi Strauss at $18.72, about 22% below the recent $22.87 price. Yet the P/E picture points in a different direction. At 14.6x earnings, LEVI trades below the US market on 18x, below US Luxury at 15.9x, and under a fair ratio of 19.6x that the market could move toward over time. That gap suggests either the DCF style fair value is too cautious or the multiple is underpricing risks. Which one do you view as more informative for now?
To stress test that question against hard numbers rather than headlines, review how this P/E gap fits into the broader valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or opportunity in disguise? If you want to move quickly and base your judgment on more than one angle, weigh both the risks and potential upsides through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Levi Strauss?
If Levi Strauss has sharpened your focus on valuation and risk, do not stop here. Fresh ideas often come from comparing different business models and balance sheets.
- Target resilience by scanning a 30 resilient stocks with low risk scores that aims to keep drawdowns in check while you stay invested.
- Hunt for mispriced quality through a 34 high quality undervalued stocks that filters for stronger fundamentals and more reasonable valuations.
- Prioritise financial strength with a list of solid balance sheet and fundamentals (24 results) that highlights sturdier capital structures when markets turn choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com