


EN
3 Growth Stocks With Earnings Growth Over 24%
Higher borrowing costs after the Reserve Bank of Australia lifted rates to 4.85% have put extra pressure on weaker companies, yet growth-focused investors still want exposure to businesses that can expand even as money becomes more expensive. That is where fast growing firms with significant insider ownership come in. This article highlights three such stocks from the screener and explains why their mix of growth and insider alignment may appeal now.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management and analysts are aligned on the outlook. However, if you want the absolute best, these 51 high growth high conviction stocks are the cream of the crop.
Pinterest (PINS)
Pinterest plugs directly into this screener’s theme because its entire business is built around turning visual discovery into ad and shopping revenue. This gives investors a more focused exposure to insider-backed monetization rather than a sprawling mix of unrelated activities.
Pinterest runs a visual search platform where users discover, save, and shop ideas, while advertisers pay for promoted placements and ad auctions. It generated about US$4.7b from its Internet Information Providers segment and has a market value of roughly US$11.6b.
"Ongoing advancements in AI-driven visual search and personalized content curation, supported by proprietary multimodal and generative retrieval models, are deepening user engagement and increasing session times."
What really matters next is how one unresolved pressure shapes the gap between Pinterest’s user engagement story and its future earnings power.
To see how that tension could resolve, read the full narrative for Pinterest and see whether accelerating engagement can eventually decouple Pinterest’s story from its current earnings profile.

Estée Lauder Companies (EL)
Estée Lauder Companies runs a global beauty portfolio focused on prestige skincare, makeup, fragrance, and hair care that leans heavily into higher-end skincare lines supporting the screener’s growth and insider-aligned premiumization story, and the business currently carries a market value of about US$37.9b.
For this screener, Estée Lauder Companies matters because its prestige skincare labels give the business a direct way to pursue higher margins while insiders remain heavily invested in that growth path, setting the stage for a more focused profit recovery story.
"Estée Lauder Companies is progressing its multi year Profit Recovery and Growth Plan and One ELC operating model, which, according to management, has already lifted gross margin by nearly 400 bps between fiscal 2024 and fiscal 2026 and expanded operating margin by 320 bps to 11.2%."
What really matters now is whether the next round of efficiency gains can be achieved without dulling demand for those high-end skincare and fragrance lines.
If that trade off between efficiency and brand heat matters to you, read the full narrative for Estée Lauder Companies to see whether Estée Lauder Companies' reset is quietly accelerating.
Oracle (ORCL)
Oracle is a key fit for this fast growing, insider-backed screener because its cloud applications and infrastructure push turns long contracts and AI-heavy workloads into recurring subscription income that can scale far beyond its legacy software roots.
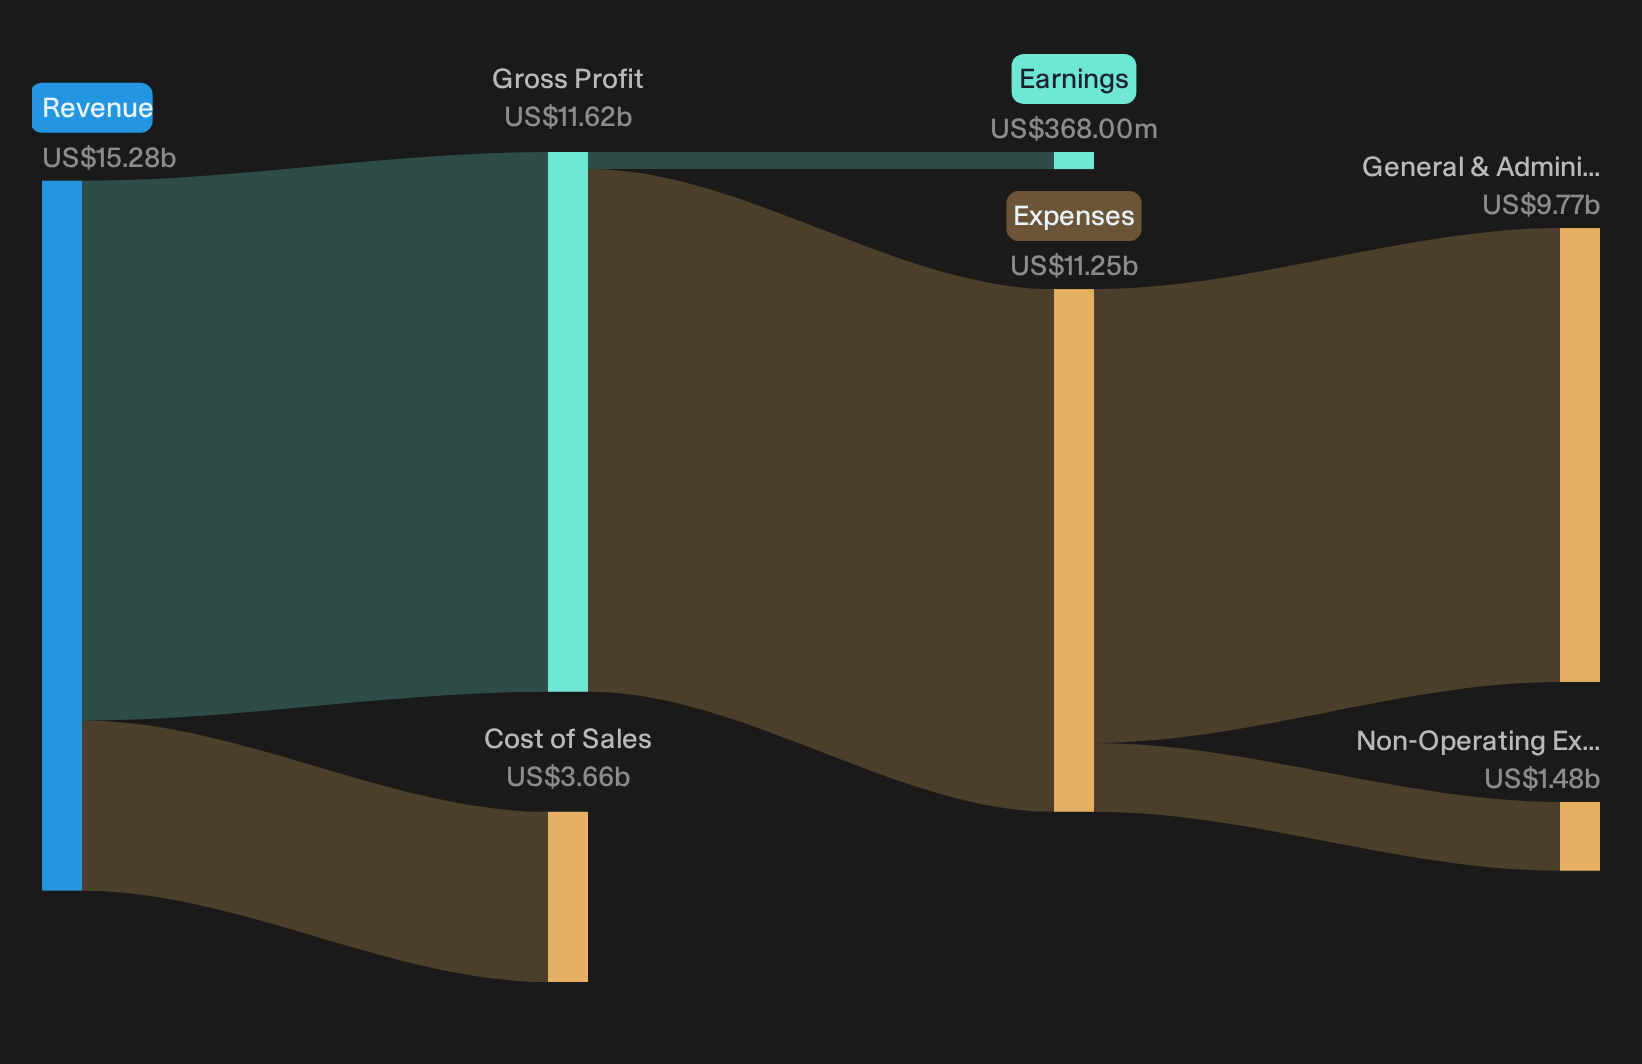
Oracle runs a broad enterprise software and cloud platform that spans databases, AI-ready infrastructure and SaaS suites such as Fusion and NetSuite, with about US$62.8b from cloud and software, US$5.8b from services and US$3.2b from hardware, and the group is valued at roughly US$361.4b.
"OpenAI began leveraging OCI Superclusters, which are capable of scaling up to 32,768 Nvidia GPUs per cluster, providing the immense capability critical for training and fine-tuning cutting-edge large language models."
What happens to Oracle’s growth story if one unseen pressure in its funding and buildout cycle meaningfully shifts cash generation or long term margins?
If that cash trade off between funding heavy cloud buildouts and protecting long term profitability is what you care about, read the full narrative for Oracle to see whether Oracle’s AI infrastructure push is accelerating or quietly masking new risks.

Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. By the time every headline catches on, the early opportunities may already have shifted. Consider scanning these under the radar for now ideas and reviewing them promptly.
- Explore resilient compounding potential with a curated 30 resilient stocks with low risk scores designed to help keep downside contained while markets continue to debate the next shift in sentiment.
- Review 53 AI infrastructure stocks related to data centers, chips, and networking gear before any changes in demand momentum are fully reflected in current pricing.
- Assess structural demand in critical metals with a focused 33 best rare earth metal stocks that screens for quality balance sheets and established production profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com