


EN
Why REA Group Fell Even As Sales Rose
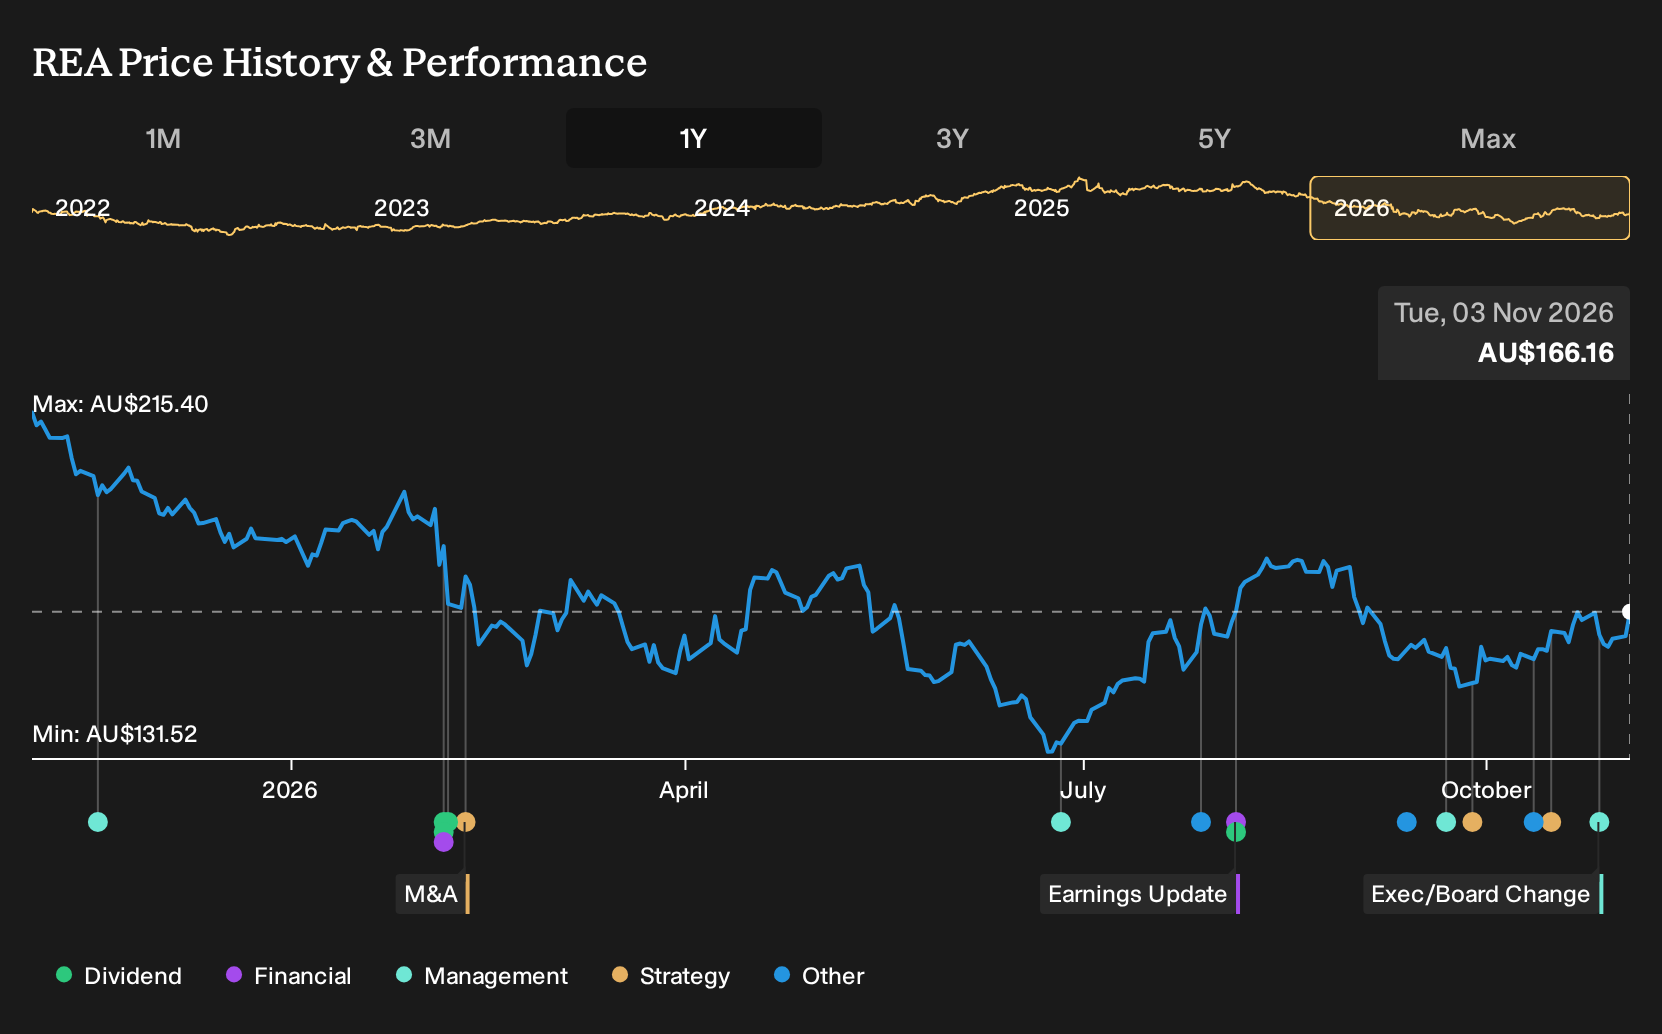
REA Group kept reporting rising revenue while profit margins slipped and the share price quietly sagged. Investors who held REA Group over the past year are down 20.4%, including dividends. If you had been weighing the upbeat analyst targets and growth stories in late 2025, that outcome might feel jarring today. With fresh earnings pressure, an ACCC undertaking and new expansion bets now on the table, what exactly was visible before the slide began?
REA Group has already moved. See which of 3 high quality undervalued stocks still trade below our estimates.
The Two REA Group Stories Investors Had To Weigh
The shares cost A$215 at the start of the period, and REA Group sat between two sharply different stories about where the property portal could go next.
The bullish narrative pointed to digital transformation, urban housing demand and premium listings. It treated A$256 as a fair value that reflected assumptions such as revenue growth of 7.1% a year and profit margins rising toward 38.8% on a three-year view.
The bearish view argued that an aging Australian market and tighter data rules might cap progress. It used a fair value of A$132 and highlighted risks such as margin pressure from regulation, competition and higher technology and expansion costs.
What The Results Changed For The REA Group Story
The clearest new fact was the earnings report. REA Group’s revenue moved from A$1,767.3m in H2 2025 to A$1,976.9m in H2 2026, yet net income slipped from A$708.4m to A$673m and net margin declined from 40.1% to 34.0%. That pattern challenged the optimistic case that counted on rising profitability and gave more weight to the cautious view on margin pressure.
The lesson is simple. When a growth story leans on higher margins, it is important to check whether net margin and profit per dollar of revenue are moving in the desired direction, not just whether sales increased.
What You Would Be Paying For In REA Group Today
With the share price at A$166, the selected Narrative’s Fair Value sits above the current level and rests on REA Group’s ability to turn product mix, data and AI tools into higher long term earnings power.
Anyone buying at today’s price would need to believe REA Group can lift listing yields while keeping operating costs growing slower than revenue.
"Some analysts expect REA Group to continue compounding the benefits of AI driven products, premium listing tiers and adjacent finance and data businesses into higher earnings power over time. The main condition for this view is that REA Group continues to grow yield on Australian residential listings through premium tiers and add ons while keeping operating cost growth below revenue growth."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 32% below our estimate - targets household electronics, appliances and entertainment buyers through big box retailers and online platforms.
- Company 2 - 17% below our estimate - supplies cloud, security and AI software, hardware and managed services to institutional technology buyers.
- Company 3 - 29% below our estimate - focuses on keeping commercial trucks and buses operating through specialist aftermarket parts supply and support.
That is three of the list. See every one of the 12 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com