


EN
Should Strong Earnings Require Action From Rambus Stock Investors?
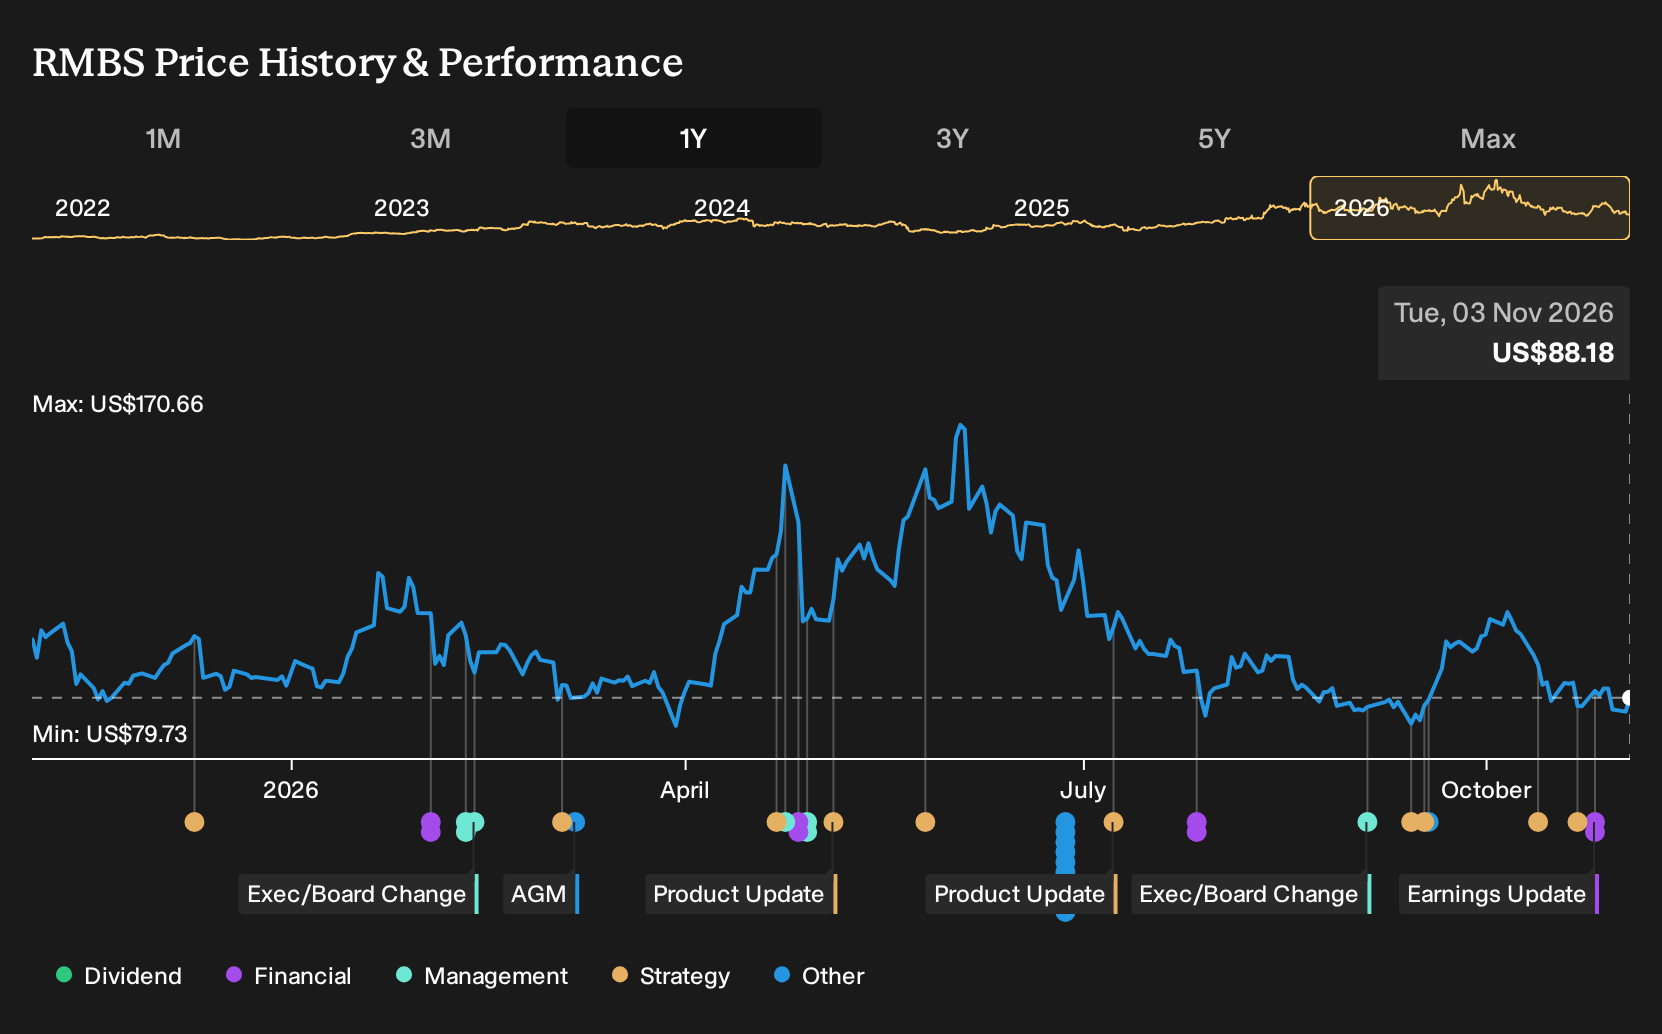
- Rambus reported third quarter 2026 revenue of US$218.29 million and net income of US$74.57 million, with higher basic and diluted EPS than a year earlier. The company also shared nine month 2026 results showing increased revenue and earnings compared with the prior period.
- The firm paired this earnings update with guidance for fourth quarter GAAP revenue of US$227 million to US$233 million and GAAP diluted EPS of US$0.68 to US$0.76. It also announced a multi faceted AI focused design agreement and investment with ChipAgents that points to deeper use of agentic AI in its chip development workflows.
- The following sections will explore how Rambus's investment narrative could be influenced by the new AI focused ChipAgents partnership and the updated guidance.
Scan Rambus alongside other chip players that are leaning into AI workflows by reviewing our curated list of 53 AI infrastructure stocks for potential beneficiaries of this design and data surge.
Rambus Investment Narrative Recap
To own Rambus, you need to believe the business can keep turning demand for high speed memory interfaces and security IP into durable earnings, even with supply bottlenecks and margin pressure in the background. The latest quarter showed higher revenue, net income and EPS versus a year earlier, which supports the idea that the model is still working. The key short term swing factor remains how well Rambus manages manufacturing constraints without giving up pricing power.
The biggest near term risk still comes from possible pressure on gross and net margins if costs rise faster than pricing or mix. The updated fourth quarter outlook for GAAP revenue of US$227 million to US$233 million and GAAP diluted EPS of US$0.68 to US$0.76 gives you a reference point. If future results track materially below those ranges, the earnings story investors are leaning on starts to look more fragile.
Among the recent updates, the companywide ChipAgents agreement is the one worth watching most closely alongside these earnings. Rambus plans to use agentic AI across chip and silicon IP design and verification workflows, with an eye on faster development and what it calls better Quality of Results for customers. That touches the core of how the firm creates products rather than just how it markets them.
If this AI centered tooling meaningfully speeds up design cycles or improves performance, it could influence several of the long running catalysts investors track, from MRDIMM readiness to DDR5 companion chip execution. There is also direct financial exposure through the investment in ChipAgents itself. On the flip side, integration missteps, limited productivity gains or customer pushback on AI driven workflows would dilute the operational benefit that many shareholders are likely hoping for.
Rambus' narrative projects US$1.2b revenue and US$474.9 million earnings by 2029. This rests on analysts modeling 17.4% yearly revenue growth and an earnings increase of about US$235 million from the current level of US$239.7 million.
Uncover why Rambus' fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Rambus focuses on the bullish margin story rather than supply risk. Before this news, the most optimistic analysts were modeling revenue of about US$1.3b and earnings of US$906.6 million by 2029, with profit margins rising from 31.7% to 70.7%. That is a very different narrative. Use this earnings and ChipAgents update as a prompt to compare those forecasts with your own expectations.
Explore 2 other Rambus fair value estimates, including one that suggests potential upside of as much as 61% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Rambus research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Rambus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rambus' overall financial health at a glance.
Looking for more investment ideas beyond Rambus?
If the Rambus story has you thinking more broadly about where to put fresh capital to work, the Simply Wall St Screener can help you scan other opportunities fast without drowning in data.
- If you prefer to focus on potential mispricings and quality in one place, and want a quick way to see which companies screen as both strong and attractively valued, start with the 34 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, and you want to narrow in on businesses with lower risk characteristics, filter the market using the 30 resilient stocks with low risk scores.
- For investors who care about balance sheet strength and fundamentals first, and want a shortlist of financially sound candidates before doing deeper work, kick off your research with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com