


EN
Revenue Jump Might Change The Case For Investing In Howard Hughes Holdings (HHH)
- Howard Hughes Holdings recently reported year over year revenue growth of 330.2% in its latest quarter, alongside a 33.6% decline in earnings per share and a net margin of 12.3%, while retaining a no dividend policy.
- The scale of this revenue jump, combined with the absence of dividend payouts, puts a brighter spotlight on how effectively Howard Hughes Holdings can turn its master planned communities and undeveloped land bank into sustained cash generation.
- We will examine how Howard Hughes Holdings' investment narrative aligns with this 330.2% revenue increase and what that may indicate for investors.
Scan 19 high quality undiscovered gems that, like Howard Hughes Holdings, are turning under-the-radar assets and management shifts into potential catalysts for their next phase of value creation.
Howard Hughes Holdings Investment Narrative Recap
To own Howard Hughes Holdings, you need to believe the master planned community engine and large US$2.4b revenue base can keep supporting project cash flows while management reorients toward an insurance centric holding structure. The sharp 330.2% revenue jump alongside weaker EPS puts the focus on quality of earnings rather than headline growth.
The short term swing factor is execution around land sales, operating assets and capital recycling while servicing US$5.2b of debt that is not well covered by operating cash flow. The biggest risk right now remains that this balance sheet and capital shift dilute returns if new investments underperform.
The most directly relevant update is the planned departure of Chief Accounting Officer Elena Verbinskaya in March 2027, with a long handover that covers the 2026 Form 10 K. For a business juggling large one off items and a complex portfolio shift, continuity in financial reporting matters for investor confidence.
You want that transition to support clear disclosure around recurring NOI, land monetization and any insurance assets the group brings in. Clean accounts help you judge whether forecast earnings growth near 22% and revenue expansion above 20% are translating into healthier margins, better return on equity and more predictable cash generation.
Howard Hughes Holdings is currently modeled to reach US$3.6b in revenue and US$369.4m in earnings by 2029, based on analyst estimates. That outlook corresponds to 15.3% yearly revenue growth and an earnings increase of about US$77.3m from the current US$292.1m level.
Uncover how Howard Hughes Holdings' fair value indicates a 10% potential upside to its current price before that gap starts to close.
Exploring Other Perspectives
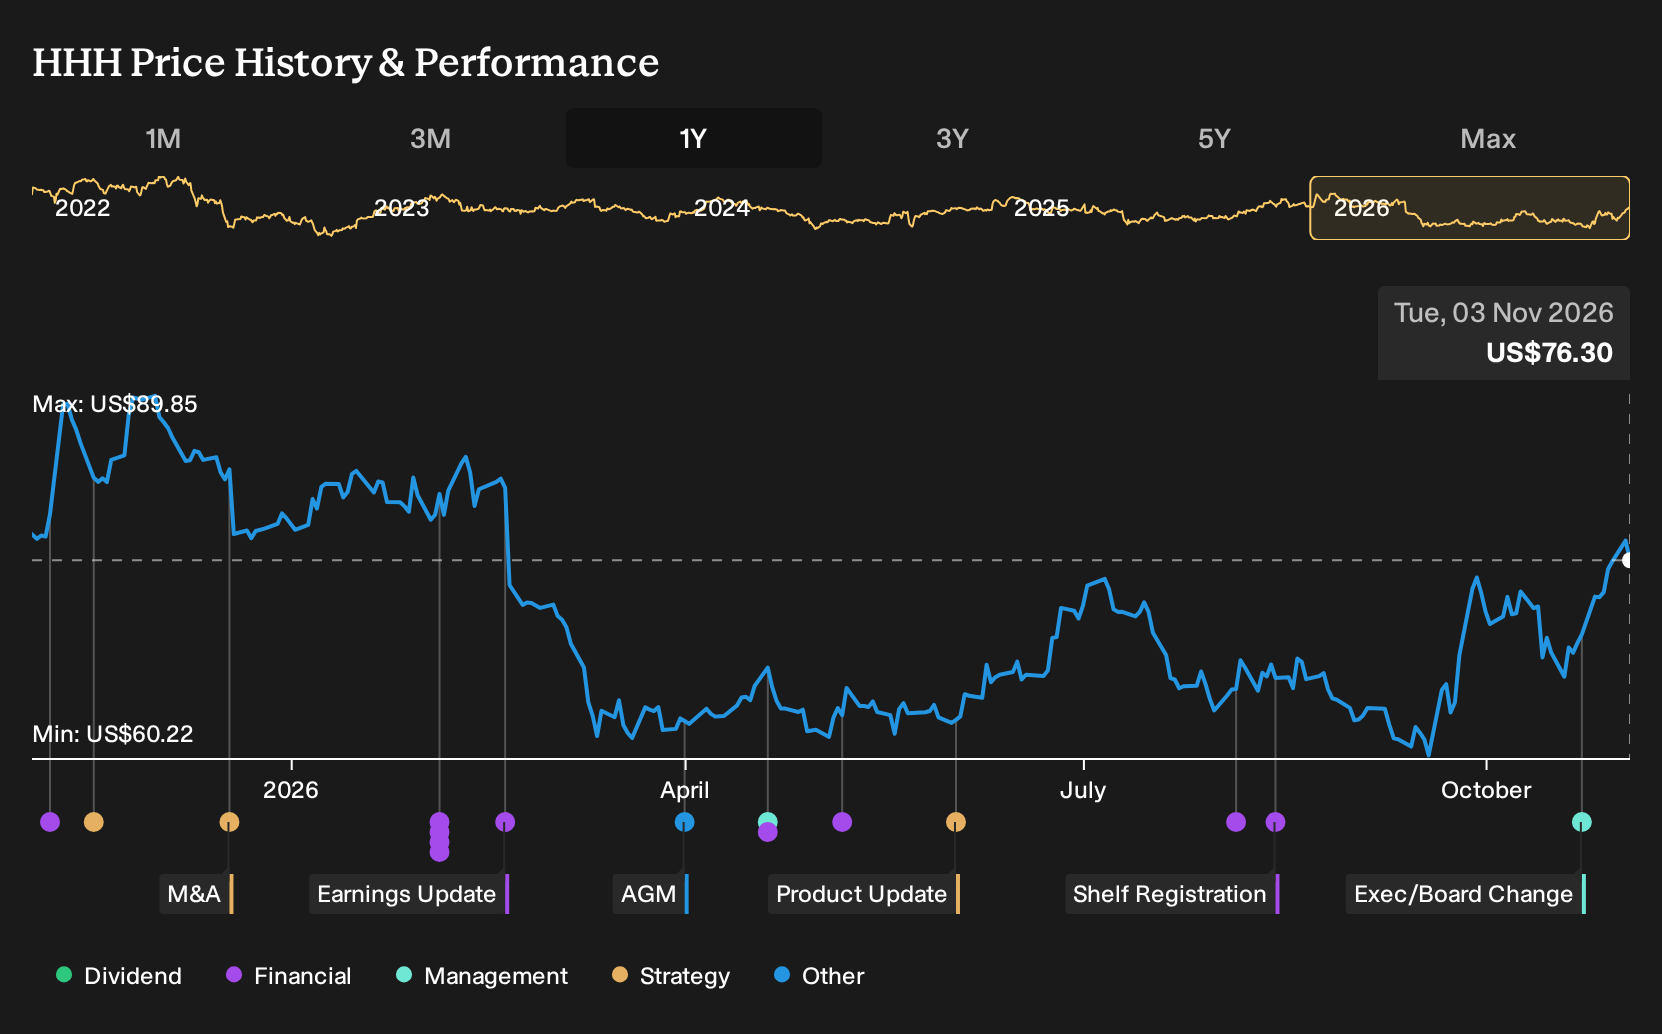
Six fair value estimates from the Simply Wall St Community span roughly US$84 to just under US$140 per share, which is a wide band for Howard Hughes Holdings. These views do not reflect the October 2026 chief accounting officer exit or the execution risks around the planned insurance tilt, so you should compare multiple viewpoints before setting expectations.
Explore 5 other Howard Hughes Holdings fair value estimates, including one that suggests potential upside of up to 83% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Howard Hughes Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Howard Hughes Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Howard Hughes Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Howard Hughes Holdings?
If Howard Hughes Holdings has sharpened your focus on quality, balance sheet strength and clear earnings power, it can be useful to line those insights up against a wider watchlist built with the Simply Wall St Screener.
- If you are hunting for quality at a reasonable price, start with companies that combine strong fundamentals with a discount to intrinsic value through the 34 high quality undervalued stocks.
- If capital preservation matters most to you, filter for businesses with sturdier finances and conservative risk profiles with the 30 resilient stocks with low risk scores.
- If resilience of the balance sheet is your first test, focus on companies that pair manageable debt with robust assets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com