


EN
Is Earnings Strength Altering The Investment Case For Visa (V)
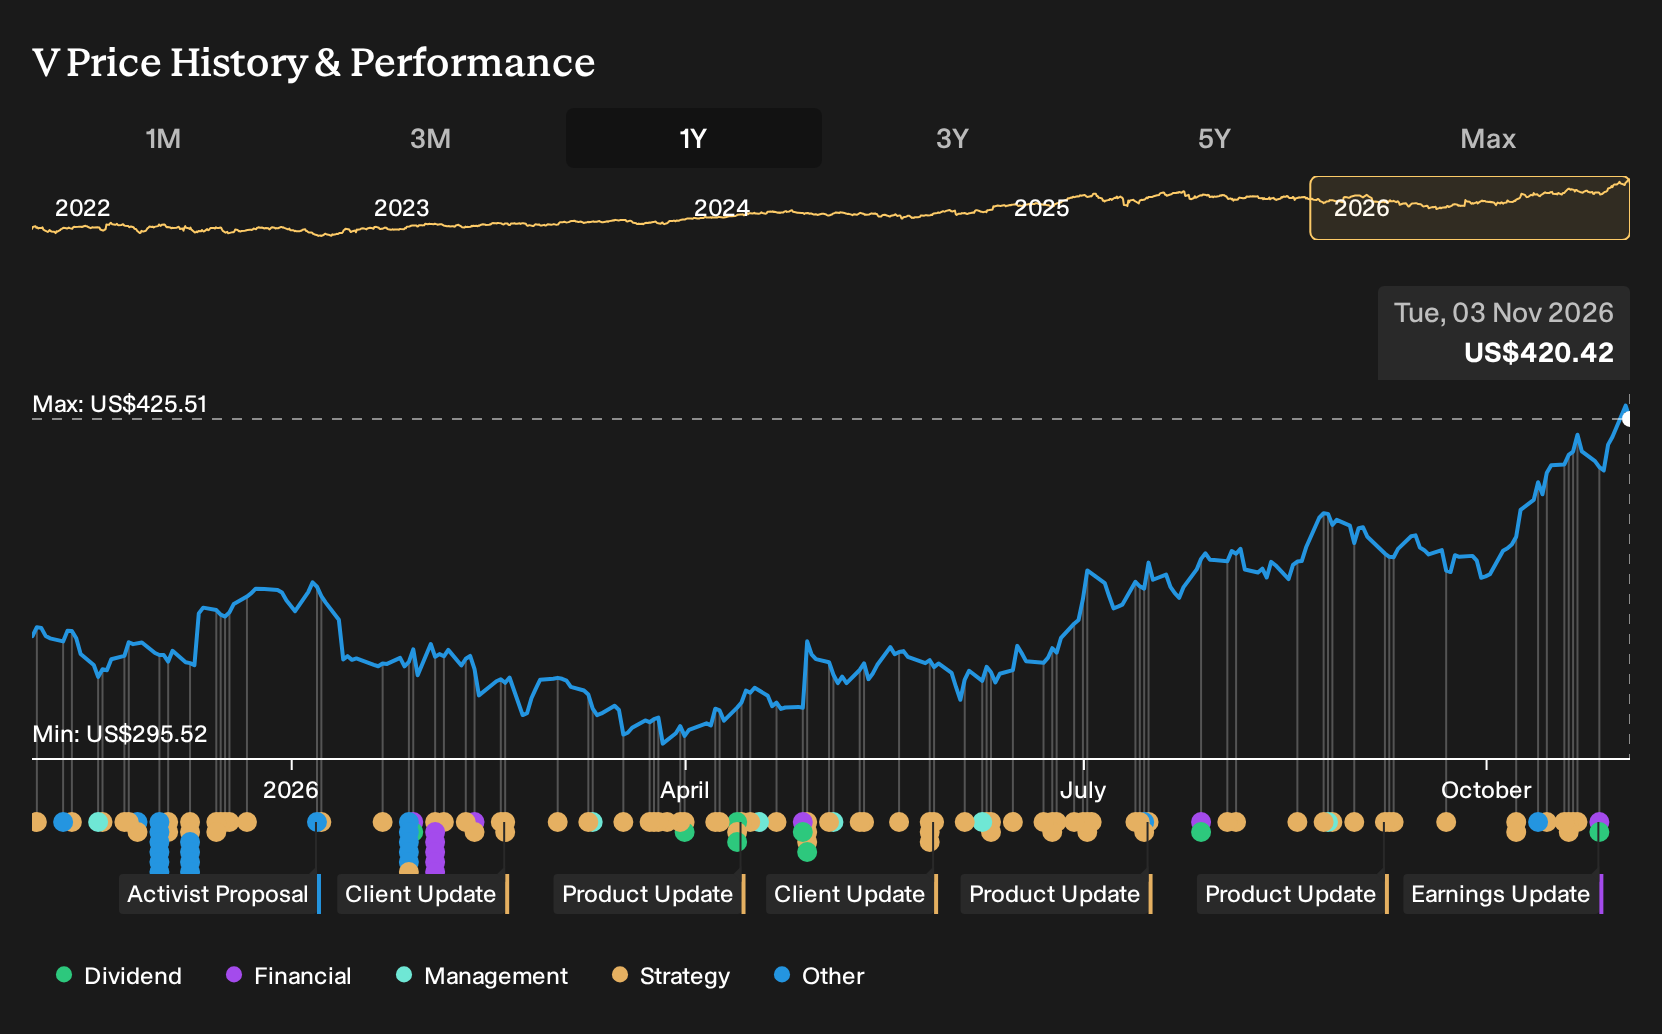
- Visa reported fourth quarter sales of US$12,139 million and net income of US$6,002 million, alongside a 16% lift in its quarterly cash dividend to US$0.780 per share, following a full year where sales reached US$45,903 million and net income was US$23,504 million.
- Beyond headline numbers, Visa is leaning into AI driven commercial tools and fraud controls, while exploring acquisitions such as Fireblocks and expanding partnerships in AI enabled commerce and digital payments across markets including Hong Kong and Senegal.
- Next, the focus turns to how Visa's stronger earnings and higher dividend may influence the investment narrative and the longer term balance between risk and reward.
Visa Investment Narrative Recap
To own Visa, you need to believe its global payment network and value added services can keep attracting more volume and higher quality fees even as alternatives like real time account to account rails grow. The latest earnings and dividend lift reinforce that the core franchise is currently throwing off substantial cash without changing the near term story.
The most important near term swing factor still sits in how quickly regulators, merchants and local schemes in regions like Europe push on pricing and access. Recent results and the higher payout do not materially change that risk. They mainly underscore that Visa is operating from a position of financial strength as it invests in AI and money movement.
The launch of SESA 2.0 and Visa Commercial Fraud Solutions is the announcement that aligns most directly with the earnings and dividend news. Visa is trying to deepen its role in commercial payments and supplier enablement, an area where management already reports solid volume growth and where value added services contribute a meaningful slice of revenue.
For you as an investor, that product suite matters because it links directly to current catalysts such as a higher mix of software like services, more commercial card usage and broader Visa Direct adoption. It also touches on key risks, since stronger fraud controls and better supplier analytics can help address pressure from new payment schemes and potential fee caps.
Visa's current analyst narrative points to revenue of US$61.3b and earnings of US$33.1b by 2029, based on assumed yearly top line growth of 11.3% and an earnings increase of about US$10.7b from US$22.4b today.
Uncover why Visa's fair value indicates a 4% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fifteen fair value views from the Simply Wall St Community cluster between about US$373 and US$486, with some members seeing Visa near the bottom of that band and others placing it close to the top. Compare those retail models with real world swing factors such as faster real time payment adoption or stronger value added services growth and you get a wide spread of possible outcomes. Opinions clearly differ, so treat these as starting points and explore several alternative viewpoints before you decide how Visa fits your portfolio.
Explore 14 other Visa fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Visa research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Visa. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Visa's overall financial health at a glance.
Looking for more ideas beyond Visa?
If Visa has sharpened your thinking about payment networks and cash generation, it can be useful to line it up against companies with very different profiles on value, income and balance sheet strength. The Simply Wall St Screener helps you scan those groups quickly so you can spend more time weighing risk and reward instead of hunting for tickers.
- For investors who want mispriced quality, start with companies that pair solid fundamentals with a discount to intrinsic metrics via the 34 high quality undervalued stocks.
- If reliable income is a priority, focus on businesses with higher yields and stronger payout profiles using the 4 dividend fortresses.
- For a more cautious approach, look at companies with robust financial positions and lower risk scores through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com