


EN
Is Alignment Healthcare (ALHC) Undervalued After Raised Guidance And A Quarterly Loss?
Why Alignment Healthcare’s latest earnings matter for investors
Alignment Healthcare (ALHC) just posted third quarter results that paired higher revenue with a quarterly net loss, then followed up by raising full year sales and health plan membership guidance.
Those two signals point investors toward the tension between top line expansion and near term profitability, and they put fresh focus on how this Medicare Advantage operator is sizing its opportunity against current execution risks.
Recent trading shows how sharply sentiment has swung. Alignment Healthcare’s share price has jumped 5.71% over the past day but is still down 45.91% over 90 days and 63.40% year to date. The 3 year total shareholder return of 19.74% contrasts with a 56.70% decline over the past year, suggesting long term holders have seen earlier gains give way to pressure as investors weigh growth potential against rising perceived risk around profitability.
Spot similar Medicare and healthcare operators that might be seeing their own inflection points by scanning our curated list of 34 healthcare AI stocks aligned with this Alignment Healthcare update.Alignment Healthcare has just bounced on raised guidance after a rough year for the stock. Is that enough reason to buy now, or does it still pay to wait for a cheaper entry before the valuation case stacks up?
Most Popular Narrative: 40% Undervalued
Alignment Healthcare closed at $7.40, while the most followed narrative pegs fair value closer to $12.31. The gap between market price and that estimate is wide and puts the spotlight firmly on whether today’s discount reflects opportunity or execution risk.
The company is investing in AI driven risk stratification, Care Anywhere clinical teams, automation and the Facets claims system migration to increase auto adjudication and payment integrity. These initiatives are aimed at lowering administrative intensity and improving net margins over time.
See why 15 investors see Alignment Healthcare as 40% undervalued.
Result: Fair Value of $12.31 (UNDERVALUED)
Still, the Alignment Healthcare story can be knocked off course if Medicare Advantage reimbursement tightens or if higher medical costs and quality bonus pressure prove harder to contain than expected.
Find out about the key risks to this Alignment Healthcare narrative.
Another View: What the multiples say about Alignment Healthcare
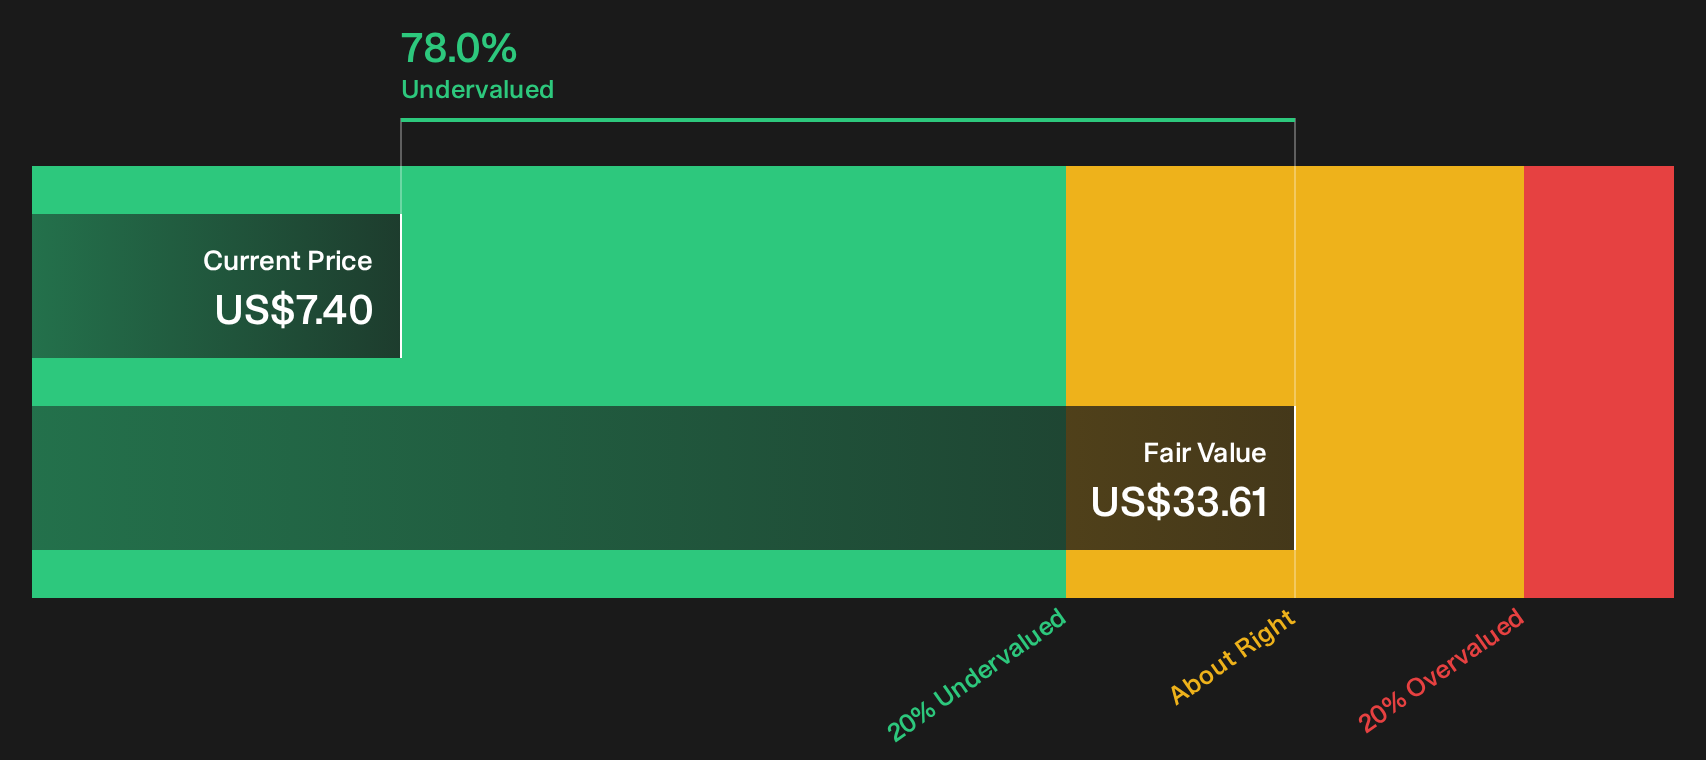
The SWS DCF model points to a large gap between Alignment Healthcare’s share price of $7.40 and an estimated future cash flow value of $33.61, which flags the stock as undervalued. That sits against a P/E of 53.6x versus 25x for the US Healthcare industry and 32.9x for peers, which looks rich on current earnings and highlights how much depends on those forecasts playing out.
Given this split between cash flow upside and a stretched earnings multiple, which signal do you trust more for your own checklist: the long runway implied by the model, or the premium P/E you are paying today?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Alignment Healthcare’s value case and risk profile can feel messy. Move quickly and stress test the full picture for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Alignment Healthcare?
Alignment Healthcare might be on your radar today, but your next opportunity could be sitting quietly in a completely different corner of the market.
- Spot companies that the market might be mispricing right now by zeroing in on 34 high quality undervalued stocks that pair quality with attractive entry points.
- Prioritise resilience and sleep better at night by combing through 30 resilient stocks with low risk scores that score well on stability and downside protection.
- Hunt for underfollowed opportunities by scanning 19 high quality undiscovered gems before they land on every other investor’s watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com