


EN
Learn Why The Bull Case For First Financial Bancorp Stock Could Change Following Earnings Beat
- First Financial Bancorp reported third quarter 2026 net interest income of US$196.26 million and net income of US$81.18 million. Earnings per share from continuing operations were modestly higher than a year earlier, and a quarterly dividend of US$0.26 per share was approved for payment on December 15, 2026.
- The appointment of veteran human capital executive Timothy A. Massa to the board adds extensive experience in compensation, succession planning and large scale integrations. This directly intersects with First Financial Bancorp’s ongoing acquisition program and its focus on execution quality.
- Next, the article will examine how First Financial Bancorp’s investment narrative is influenced by stronger fee driven earnings and loan activity.
Scan how First Financial Bancorp’s fee driven model and acquisition push compares with a curated list of regional lenders in the list of solid balance sheet and fundamentals (24 results).
First Financial Bancorp Investment Narrative Recap
For an investor to stay on board with First Financial Bancorp, the core belief is that acquisition driven growth, fee income and a resilient net interest margin can keep pulling more earnings out of the existing footprint. The latest quarter supports that story, with net interest income of US$196.26 million and net income of US$81.18 million backing that operational thesis.
The near term swing factor is still execution on deals like Finward and the broader loan and fee pipeline, while keeping credit costs controlled as net charge offs reached US$7.24 million in the quarter. Rising charge offs remain the biggest risk to the story right now, although the current level is not a break in the thesis by itself.
The most directly relevant update for this narrative is the third quarter earnings release on 27 October 2026. Record fee income, resilient net interest margin and strong commercial and industrial lending were highlighted as the drivers that helped offset pressure in commercial real estate and keep earnings per share ticking higher year on year.
Those results matter because they link directly to the main catalysts investors are watching in First Financial Bancorp. Fee diversification reduces reliance on spread income, while loan demand gives the pending Finward acquisition more deposits and assets to work with if integration goes to plan. The combination of earnings mix, credit quality and deal execution will likely set the tone for how the story evolves from here.
First Financial Bancorp’s current analyst script ties many points back to explicit earnings math. Consensus assumptions indicate revenue growth of 13.5% a year and earnings increasing from US$285.2 million today to US$455.1 million by 2029. This represents an earnings increase of roughly US$169.9 million over that period, with revenues projected to reach US$1.4b and earnings US$455.1 million in 2029.
Uncover why First Financial Bancorp's fair value indicates a 16% potential upside to its current price before other investors close that discount gap.
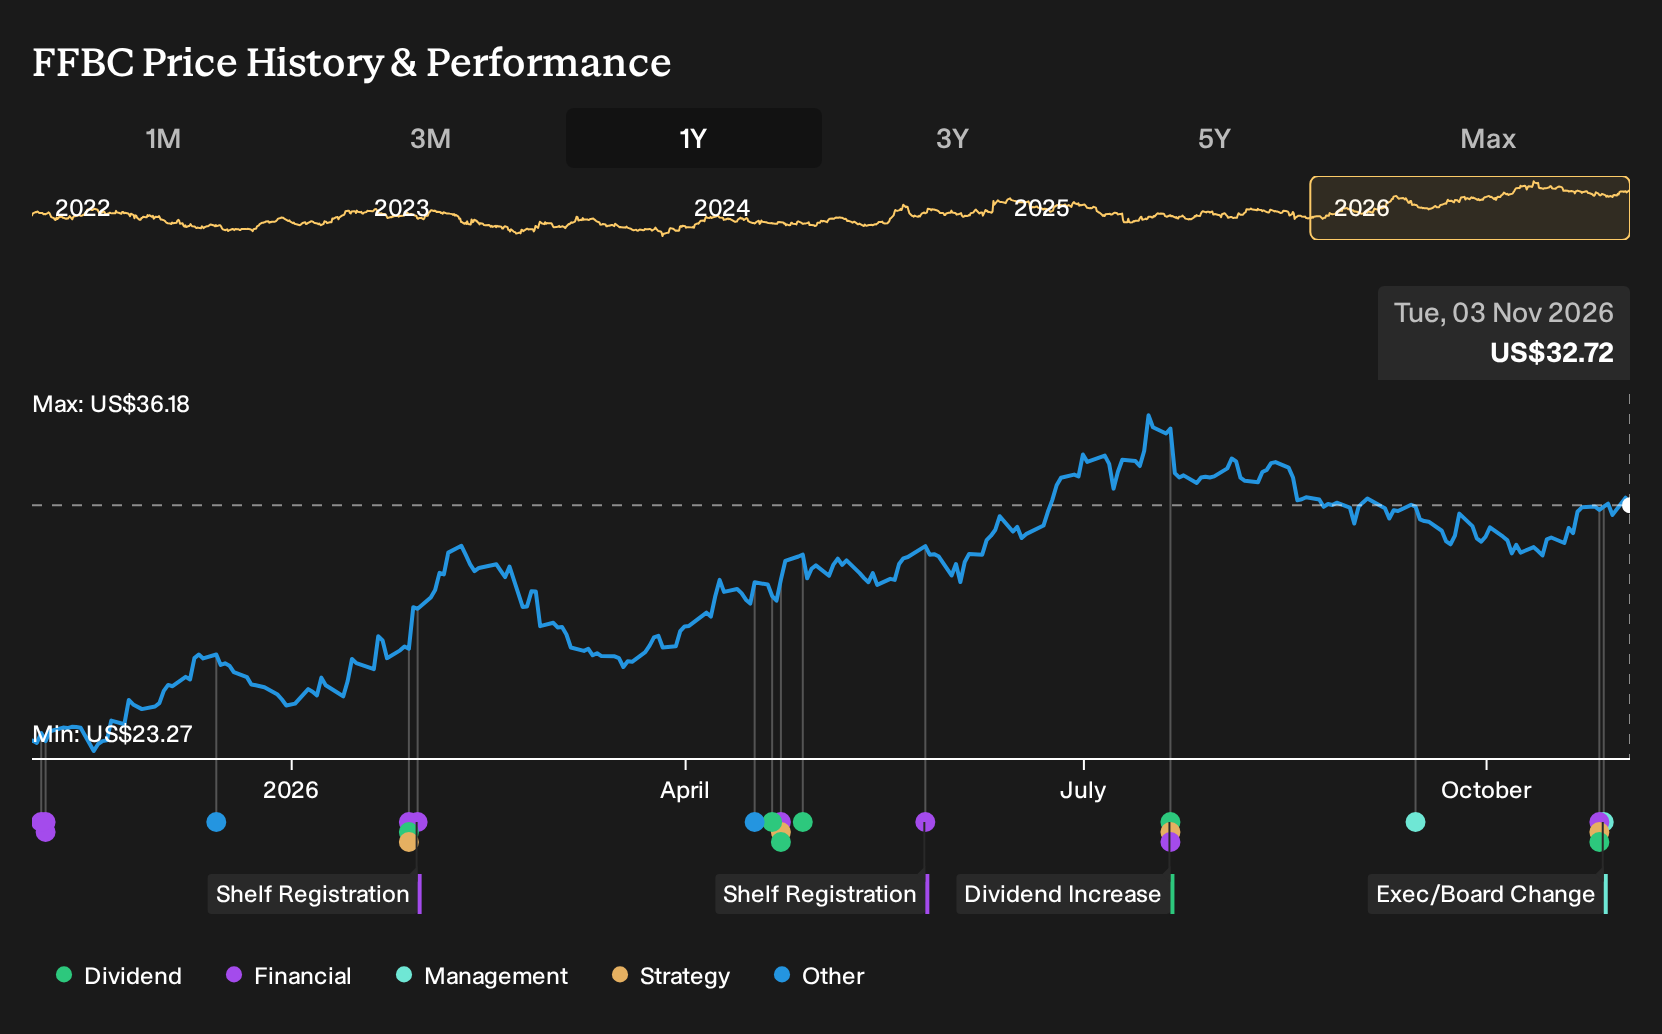
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$37.86 to US$53.78, so private investors are clearly not marching in lockstep on First Financial Bancorp. When you set that spread against rising net charge offs and the Finward acquisition plans, you can reach very different conclusions on future earnings resilience. Explore those alternative views directly before leaning on any single narrative.
Explore another First Financial Bancorp fair value estimate, including one that suggests it could be worth just $37.86.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First Financial Bancorp research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First Financial Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Financial Bancorp's overall financial health at a glance.
Looking for more investment ideas beyond First Financial Bancorp?
If you like the structure of First Financial Bancorp’s story but want a wider bench of possibilities, it helps to line it up against other companies with different income mixes, balance sheets, and payout profiles.
- For investors who want potentially mispriced quality, compare First Financial Bancorp with a curated group of businesses flagged as 34 high quality undervalued stocks based on fundamentals rather than hype.
- If reliable income sits high on your priority list, weigh First Financial Bancorp’s payout against a set of stocks screened as 4 dividend fortresses to see how its yield and consistency stack up.
- To reduce portfolio stress when conditions get choppy, set First Financial Bancorp alongside companies identified as 30 resilient stocks with low risk scores and see which mix of risk and reward feels right for you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com