


EN
From breaking to stabilizing the issue price, the Eston (02715) quarterly report conceals a “profit revaluation” card?
In the field of domestic industrial robots, ESTON (002747.SZ, 02715) has always occupied the “leading” position. Meanwhile, the third quarter report disclosed on October 30, 2026 handed over a report card sufficient to allow the market to re-examine the company's value.
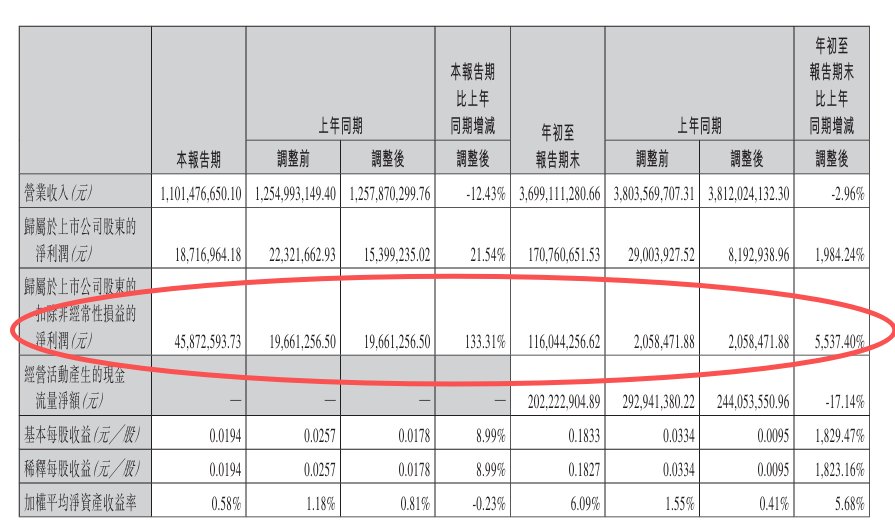
According to financial reports, in the first three quarters, the company achieved operating income of 3,699 billion yuan and net profit attributable to shareholders of listed companies of 171 million yuan, an increase of 1984.24% over the previous year; net profit after deducting non-recurring profit and loss of 116 million yuan, an increase of 5537.40% over the previous year. Looking at a single quarter, net profit deducted in the third quarter increased by 133.31% year on year. Against the backdrop of revenue pressure, the profitability of the company's main business showed a strong recovery trend.
As can be seen, the value of this performance report goes far beyond the increase in numbers. It marks the substantial results of Eston's strategic transformation from scale expansion to efficiency improvement, and also reveals the unique resilience of the domestic robot industry in the current economic cycle.
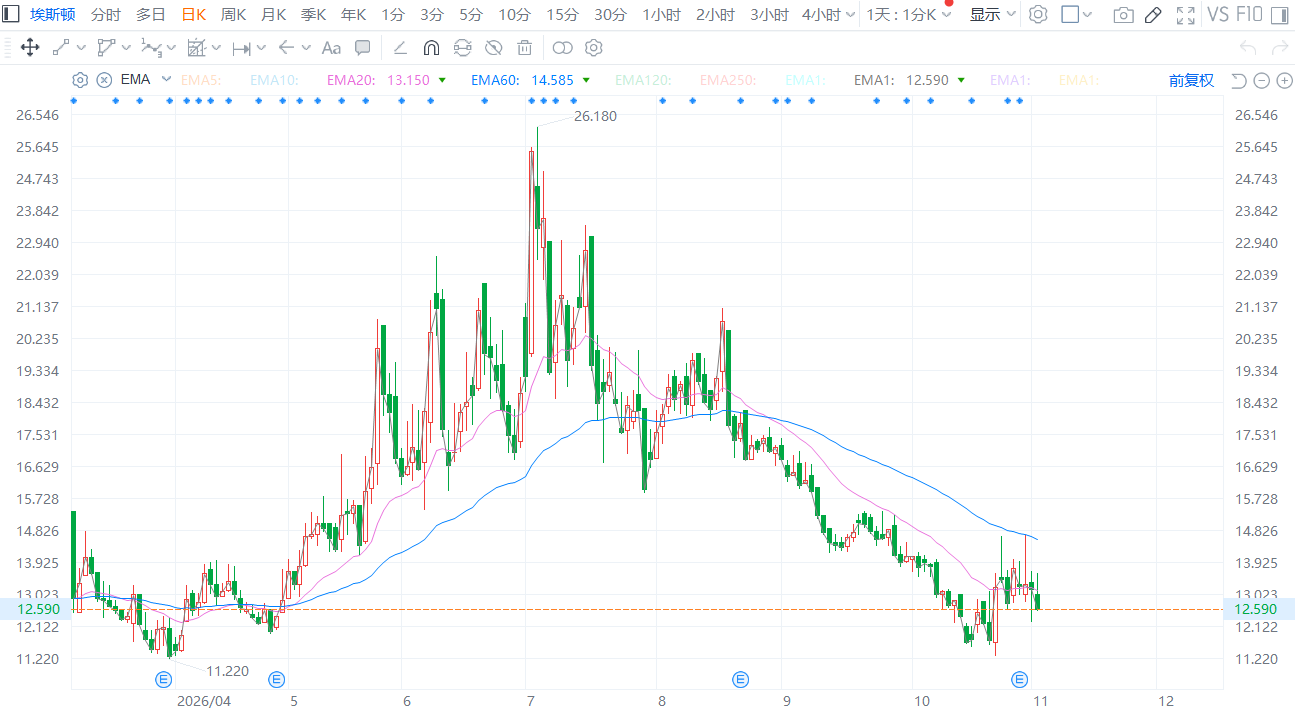
Of course, this astonishing growth rate in the third quarter also stimulated its stock price to a certain extent. On the same day, Eston H shares surged higher during the intraday period, hitting a high of HK$14.66, the biggest intraday increase of more than 10%, then fell back to HK$13.29 at the close, narrowing to around 0.3% throughout the day. An intraday surge indicates that high performance did stimulate buying in a short period of time, but the closing almost all of the gains was taken back, which also suggests that the market's pricing is not unidirectional.
Since its listing on March 9, the stock price of Eston H shares has also completely gone through the complete process of “breaking ground - anticipation-driven rebound - returning to fundamental screening”. From breaking on the first day of listing, bottoming out at the end of March, to basically standing above the issue price at the end of the third quarter, it hit a high of HK$26.18 in 52 weeks, and now the stock price continues to fluctuate around HK$13.
(Market source: Futu)
Will this three-quarter report, which has seen a high increase in performance, prompt Eston to revalue?
Gross profit margin, expenses, and infrequency resonate with the main business
Extend the timeline to the first half of 2026, and Eston's growth trend may be even more clear.
In the first half of the year, the company achieved revenue of 2,578 billion yuan, up 1.14% year on year; net profit to mother was 161 million yuan, up 2314.23% year on year; after deducting non-net profit of 70 million yuan, an increase of 498.64% year on year. Gross profit margin was 31.81%, up 4.17 percentage points year on year; Q2 single quarter gross profit margin was 33.08%, up 6.04 percentage points year on year. From H1 to Q3, gross margin increased quarterly, and continued growth after deducting non-profit, indicating that profit restoration was not an accident in a single quarter, but rather a continuation of structural optimization and cost reduction and efficiency.
The low base for the same period in 2025 certainly provides a background for profit elasticity, but what is more critical is the simultaneous improvement of gross profit margin, expense ratio, and net profit deduction in 2026.
Specifically, the primary driver for improving Eston's profit was gross profit margin. The company's operating costs fell 8.16% in the first three quarters. Based on this, gross margin was estimated to be about 32.36%, an increase of about 3.83 percentage points over the same period last year. Behind this is a combination of factors such as product and customer structure optimization, supply chain cost reduction, domestic substitution of raw materials, and lean manufacturing. The Q3 gross margin increased by 33.64%, which is higher than the overall level of the previous three quarters, indicating that the improvement trend continues at the quarterly level rather than a one-time jump.
The second step is cost control. In the first three quarters, the company's management expenses fell 6.9% year on year, financial expenses fell 15.5% year on year (mainly benefiting from reduced interest expenses), and sales expenses and R&D expenses also declined slightly. Reduced cost ratio pressure and increased gross margin together drive an increase in operating profit. This is the healthiest way to release profits — not by reducing R&D or cutting sales, but by improving efficiency.
The third trigger comes from simultaneous improvements in deducting non-profits. During the reporting period, the participating company Nanjing Process Asset was restructured, and the company's shares were replaced with Nanjing Chemical Fiber shares, which brought about fair value changes and increased net profit to mother. However, looking at the Q3 single-quarter data, non-recurring profit and loss were negative, and the year-on-year increase of 133.31% was achieved after deducting non-net profit. This key change directly confirms that the core driving force of profit improvement comes from an increase in one's own operating capacity, not simply the dividends brought about by asset revaluation.
(Photo Credit: Eston Quarterly Report)
In addition to this, at the capital level, the issuance of H shares has established a secure cushion for the enterprise. Monetary capital reached 1,499 billion yuan at the end of the reporting period, an increase of 65.98% over the end of the previous year. Owners' equity increased dramatically at the same time. The capital raised will continue to enable R&D iteration, market expansion, and industry integration. The net cash flow from operating activities of RMB 202 million maintains a positive inflow, guarantees the daily operating turnover of the enterprise, and provides a stable cash base for subsequent business expansion.
It is easy to see that Eston's high performance increase in this round is not a short-term illusion spawned by cyclical dividends and one-time earnings, but rather a definitive reversal of gross margin restoration, cost optimization, improvement of main business quality, and consolidation of cash flow in multiple dimensions.
Based on industry trends, “endogenous extension” drives growth potential
Of course, Eston's profit recovery is not an isolated incident; it is embedded in the soil of industry trends.
On the one hand, the domestic substitution process is speeding up. Demand for intelligent and flexible transformation in downstream automotive, new energy, electronics and other manufacturing fields continues to be released, and the market share of domestic brands is steadily increasing. According to MIR data, the 2026H1 Eston industrial robot continues to rank first among all brands in the Chinese market. It has maintained the lead for six consecutive quarters and ranked first among domestic brands for eight consecutive years. The leading position provides a solid foundation for scale effects, supply chain bargaining, and customer introduction, and also creates industrial conditions for improving gross margin.
On the other hand, robot+AI opens up room for growth. The company continues to promote the deep integration of robots and AI and the implementation of intelligent industrial scenarios. The advantages of the entire industry chain of “core components+robot machine+solution” provide a complete closed loop of hardware, scenarios and system capabilities for AI implementation. Robotic AI is not a conceptual decoration; it is an era window for Eston to move from an equipment vendor to an intelligent solution provider. When AI moves from the cloud to production lines, companies with complete machines, core components, and scenario data can truly have the conditions to turn technology into profit.
In such a development environment, Eston closely follows the trend of the industry and insists on combining internal optimization with external expansion, forming a development pattern of “building a solid domestic market, opening up new space overseas, and expanding the growth potential of leading players”.
Internally, the company actively reshapes product and customer structures, actively reduces gross profit orders, and tilts resources towards high value-added products and high-quality customers. The gross margins of the two major sectors, core components of automation and complete industrial robots, increased simultaneously. The technology side continues to advance. 1,200kg oversized payload robots and high-precision six-axis robots have entered many leading car companies to achieve batch implementation; at the same time, the company closely follows industry trends, promotes the integration of robots and AI, lays out intelligent scenarios for the industry, and reserves technical potential for medium- to long-term product iteration.
Capital operations continued to improve the industrial puzzle. During the reporting period, the company completed the acquisition of 100% of Eston Cool's shares, with transaction consideration of 487 million yuan. The target was officially included in the scope of the consolidated statement. Cool Zhuo focuses on the R&D and manufacturing of collaborative robots and embodied intelligent robots. After the acquisition is completed, it will make up for shortcomings in the product matrix and further strengthen the competitive advantage of the entire industry chain. Subsequent business collaboration and integration results will become an important incremental focus for future performance.
Externally, the strategy of globalization has grown into an important engine of growth. As early as the first half of 2026, the company's overseas revenue reached 936 million yuan, an increase of 25.06% over the previous year, and the share of overseas revenue increased to 36.33%. In addition, the company has built 75 global service outlets, and the Polish warehousing and manufacturing base has been successfully put into operation. Relying on localized production and delivery capabilities, it has successfully entered the supply chain of many leading European auto parts and general industrial customers. Overseas business is growing rapidly, effectively hedging phased fluctuations in the domestic market and opening up a larger growth boundary for the company.
As can be seen, Eston's profit recovery is not driven by a single factor, but rather the result of “endogenous quality improvement” and “epitaxial expansion” intersecting along the same logical line.
Summarize
In summary, Eston's three-quarter report already marks that the company has officially entered a critical stage of profit recovery. Reducing costs and increasing efficiency, optimizing business structures, expanding globally, and replacing domestic production resonates with multiple forces to jointly promote basic improvement. Although the domestic market is under pressure in the short term, the company actively chose to improve quality and efficiency, abandoning inefficient orders in exchange for improving profit quality; in the medium to long term, relying on the advantages of the entire industry chain, overseas market growth, and AI robot technology layout, the growth story of this domestic industrial robot leader continues, and this will also become a key catalyst for valuation digestion and revaluation.