


EN
Zebra Technologies (ZBRA) Stock Looks Below Fair Value On Its 58% Run
Zebra Technologies has delivered a powerful share price run over the past few years, yet the recent pullback raises a straightforward question for anyone looking at the stock. Is the current US$329.50 price properly supported by the cash the business is expected to generate over time, based on a Discounted Cash Flow (DCF) view of its intrinsic value.
- The stock has returned 58.4% over the past 3 years, which puts real weight on whether that gain lines up with the cash the business can produce in the future.
- Recent earnings updates and raised expectations for revenue and free cash flow can shift how durable Zebra Technologies' cash generation looks and how much is being paid today for that stream.
- Prefer to judge Zebra Technologies on earnings? See why Zebra Technologies's 28.9x P/E tells a different valuation story.
The issue now is whether Zebra Technologies' current share price is justified by its cash flows when you compare it with the intrinsic value suggested by a Discounted Cash Flow (DCF) model.
If you want to test the same "is the price justified by its cash flows" question across a wider field, compare Zebra Technologies with companies in the 94 robotics and automation stocks.
Is Zebra Technologies Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses on the cash Zebra Technologies can return to shareholders over time. On the latest twelve month view, the group produced roughly $893.9 million of free cash flow, and the 2 Stage Free Cash Flow to Equity model then projects this to keep building from current levels rather than shrinking.
Those projections point to growing free cash generation through the early 2030s, with the later years assuming a steadier, lower growth path as Zebra Technologies matures. Because management recently guided to at least $1b in free cash flow for the full year and raised its outlook after a strong Q3 2026, the richer cash profile helps explain why the Discounted Cash Flow (DCF) result suggests an intrinsic value substantially above the current $329.50 share price. Find out what Zebra Technologies could be worth using our Discounted Cash Flow (DCF) estimate.
The Zebra Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the DCF puzzle on Zebra Technologies leaves off. They set out which combinations of future growth, profitability and earnings power would need to play out for the current share price to look materially higher or lower. Instead of giving a single number, Narratives describe the future path that number relies on so you can judge over time whether Zebra Technologies' actual progress is keeping in step with that story. Narratives sit on Simply Wall St's Community page and link the cash flow maths to a clear, trackable set of business outcomes.
One of the top community narratives on Zebra Technologies: 21% undervalued
"The accelerating shift toward automation, digital transformation and real time workflow optimization, supported by Zebra Technologies products that feed data into robots, automation systems and connected assets..."
Discover why this Narrative puts Zebra Technologies at 21% undervalued.
The Zebra Technologies story is not complete if you only look at the share price
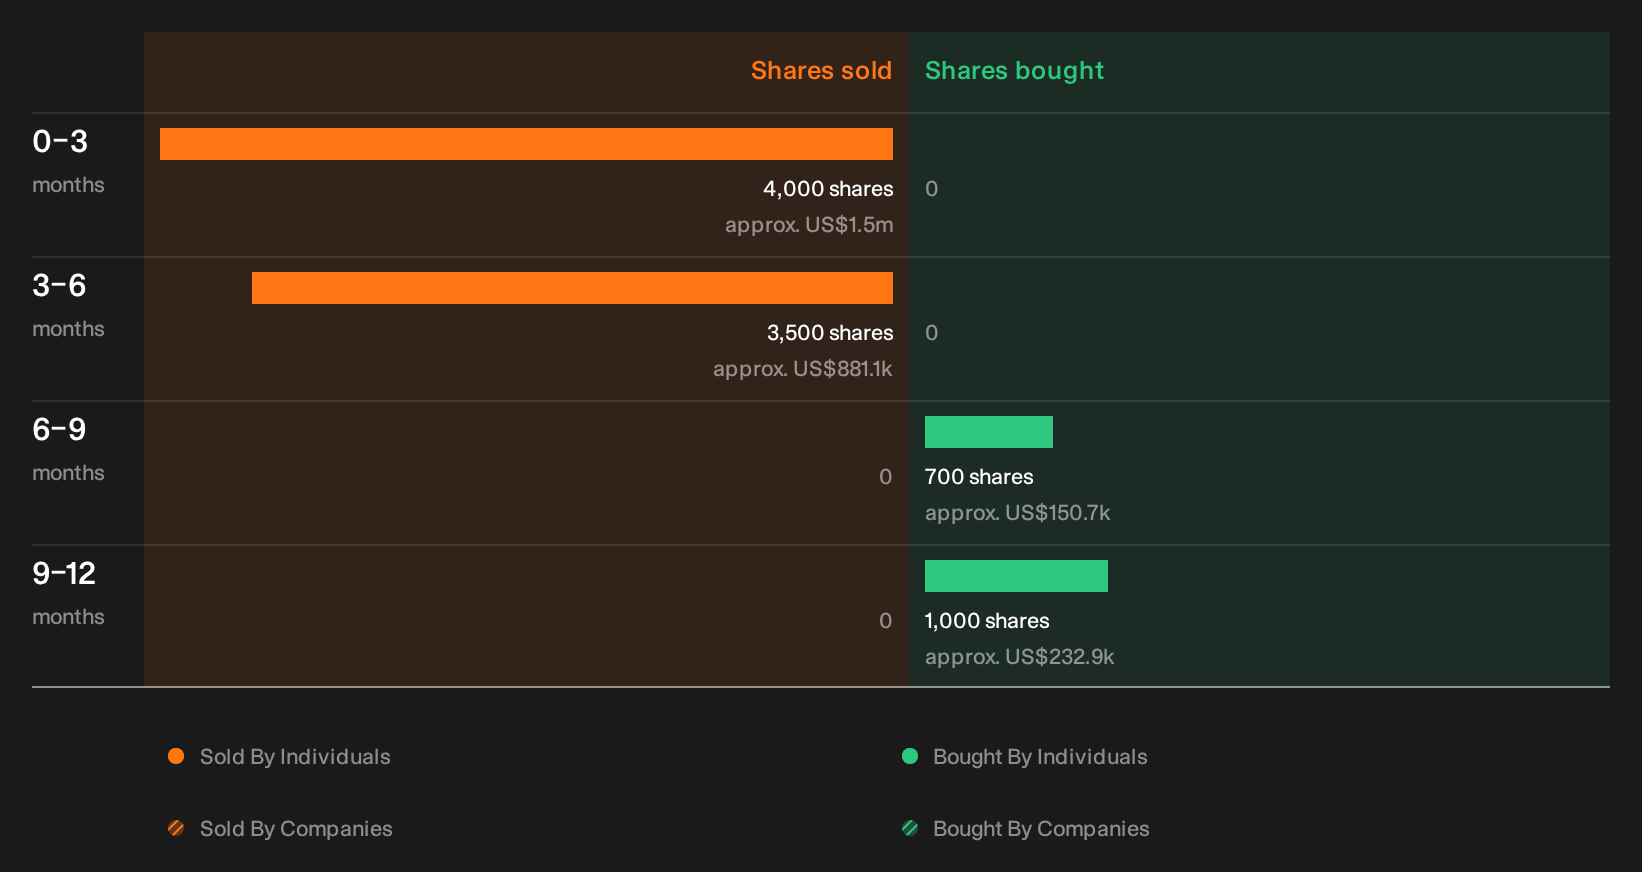
Valuation work helps frame what you might pay, but recent dealing by Zebra Technologies insiders could shine a very different light on risk and conviction, with who sold, how much and why still to unpack. See the recent insider selling flagged for Zebra Technologies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com