


EN
Choice Hotels (CHH) Stock Faces Q3 Earnings Margin Squeeze
Choice Hotels International stock barely moved after its Q3 2026 earnings release, edging up around 0.3% to about $118. Yet the headline result was not flat at all. Adjusted diluted earnings per share came in at $2.33, with adjusted EBITDA near $193 million, pointing to a franchise engine that is still throwing off solid profit.
Short term traders may see a sleepy reaction. Long term holders are more likely to focus on the bigger tension. Forecast earnings growth and a 25.8x P/E multiple sit alongside a net profit margin that has compressed and a balance sheet where debt coverage by operating cash flow looks tight.
Like the earnings power at Choice Hotels International but uneasy about compressed margins and tight debt coverage? Check a curated list that focuses on companies with stronger balance sheets and cash support with the list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$285.4 million vs. US$277.9 million (up about 2.7%)
- Net Income, excl. extra items (Q3 2026 vs. Q3 2025): US$57.7 million vs. US$179.1 million (down about 67.8%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$1.29 vs. US$3.89 (down about 66.9%)
- Net Profit Margin, trailing 12 months vs. prior year: 20.3% vs. 39.0% (compressed by 18.7 percentage points)
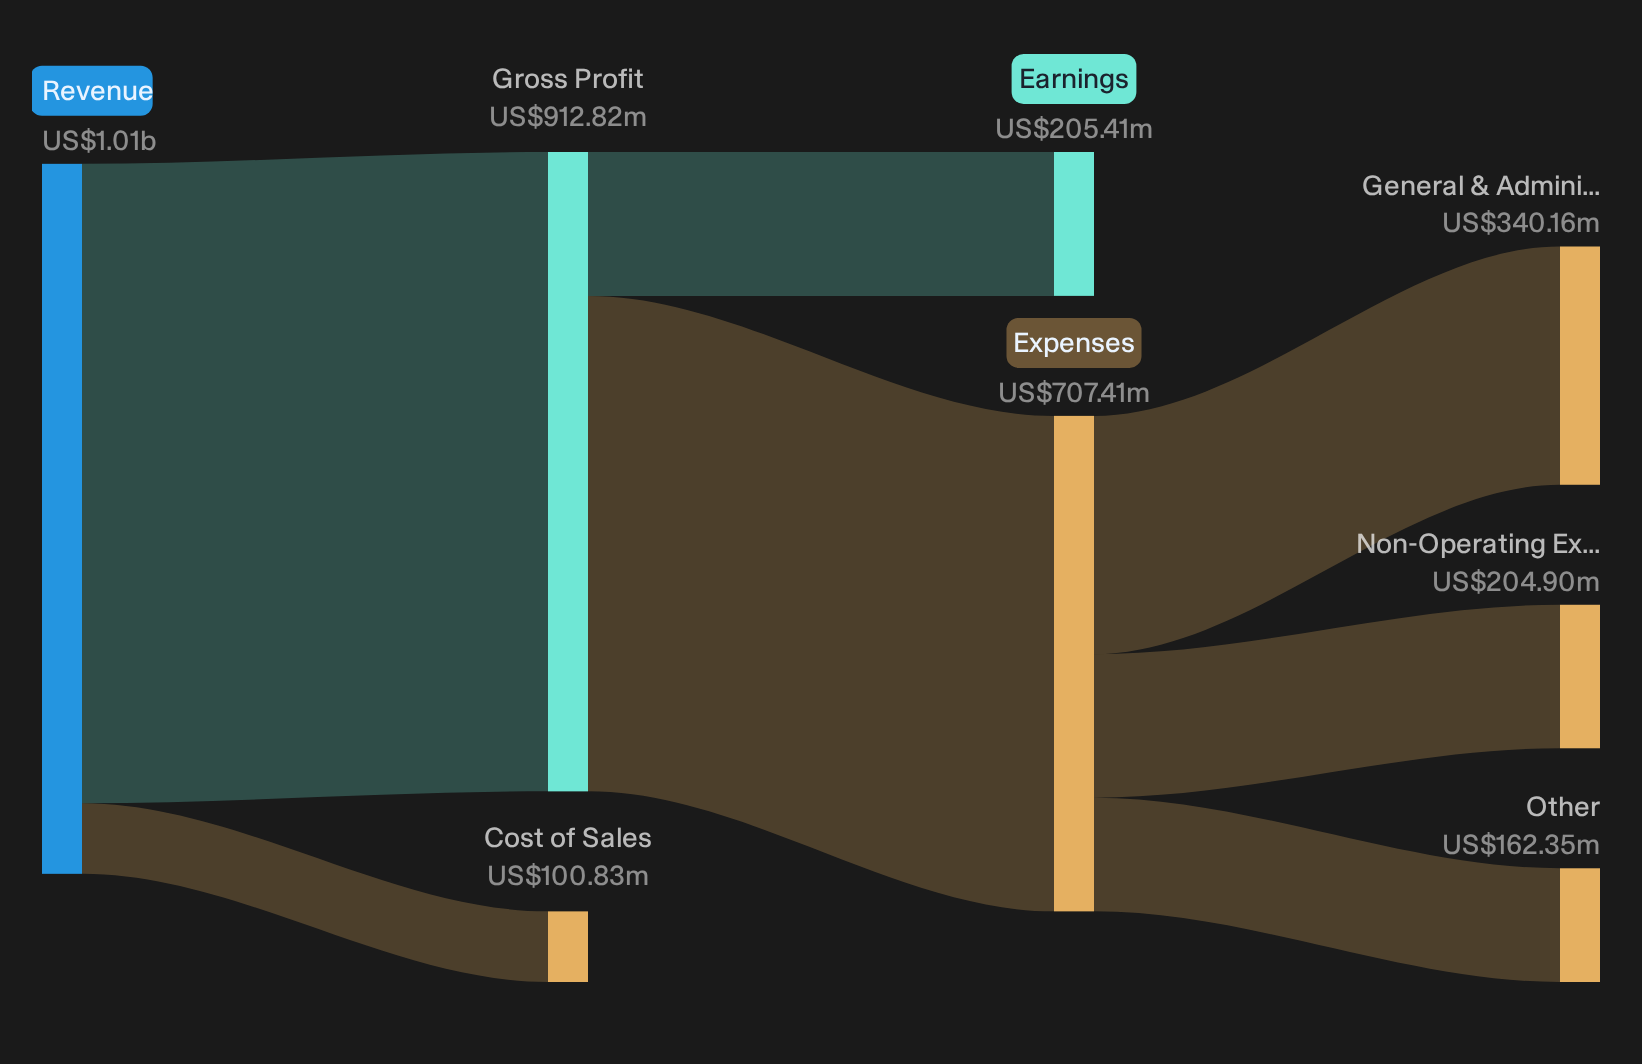
Choice Hotels Bull Case Meets Mixed Evidence
Optimists argue that Choice Hotels International can turn its tech spend into a real edge for franchisees and revenue quality.
"The main thing that has to go right is that Choice Hotels International converts its technology and AI investments into better franchisee economics and demand generation, so tools like CHARLIE and EasyBid continue to lower franchisee costs and support higher quality revenue across the system."
Early signs help that argument. EasyBid lifted group revenue 27% and raised RFP win rates 210 bps. AI tools cut reputation management fees about 30%. Loyalty and Business Direct are pulling more demand into proprietary channels. Yet trailing net profit margin compression and softer operating cash generation show this efficiency story is not fully flowing through to bottom line results.
Bear Case On Returns And Risk Still Lingering
Skeptics worry that even with an asset light tilt, returns and perceived risk may not improve enough to change how the market treats Choice Hotels International.
"External analysis pointing to plateauing RevPAR, declining return on invested capital, weak financial strength scores around 4 out of 10 and only moderate free cash flow margins suggests that if returns on the shift back to an asset light model do not improve, the stock could continue to be treated as higher risk, which would pressure valuation multiples and total shareholder return."
Q3 shows some progress against that concern. Adjusted EBITDA rose, U.S. RevPAR advanced 3.8%, and development outlays dropped sharply as owned hotels are sold and re-franchised. Liquidity of about US$928 million and net leverage of 3.2x sit within management’s target. At the same time, operating cash flow fell year on year and net income, excluding extra items, dropped heavily with margin compression, so the shift toward higher returns is not yet clear in the reported profitability or cash conversion.
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for.
Hunt Mispriced Earnings Power
Choice Hotels International recently reported results that highlighted how a complex income statement can leave the share price relatively steady. The real opportunity may lie in companies where fundamentals and market expectations still diverge.
- Company 1 - 48% below our estimate - uses an expanding app-led store network to trial new beverages and lift ordering frequency among heavy users despite mixed same-store performance.
- Company 2 - 28% below our estimate - turns rising digital engagement and underpenetrated credit demand into fee income and interest revenue across lending, payments and wealth offerings.
- Company 3 - 43% below our estimate - rolls out cash recycling ATMs and branch-in-a-box systems that help banks reduce physical locations while preserving automated transaction capacity.
Three companies from the same screener. Open every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com