


EN
Information Services Group (III) Stock Sinks Despite Strong Q3 Earnings Margins
Information Services Group came into this Q3 2026 report with its stock up strongly over the past three months, yet traders hit the sell button on the print, pushing the share price down about 4.3% to US$6.01 on Wednesday. That quick markdown clashes with what the quarter actually showed. Revenue reached US$65.1m and adjusted EBITDA landed at US$10.0m, delivering the firm’s highest EBITDA margin in four years. The real story sits in that margin performance, not the one day price reaction, and it frames how you might evaluate this consultancy’s earnings power from here.
Like the earnings profile at Information Services Group but want more consulting and tech stocks that pair strong margins with solid balance sheets? Compare Benchmark III with a curated set of peers in our list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$65.1m vs. US$62.4m (up about 4.4%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): US$3.37m vs. US$3.06m (up about 10%)
- Basic EPS (Q3 2026 vs. Q3 2025): US$0.07 vs. US$0.06 (up about 10%)
- Adjusted EBITDA Margin (Q3 2026 vs. Q3 2025): 15.4% vs. roughly 13.4% (about 200 bps expansion and the highest margin in four years)
Prefer interactive charts instead of another wall of earnings tables and footnotes? View Information Services Group's full financial picture, including a visual overview of valuation and profitability trends, in the company report for Information Services Group.
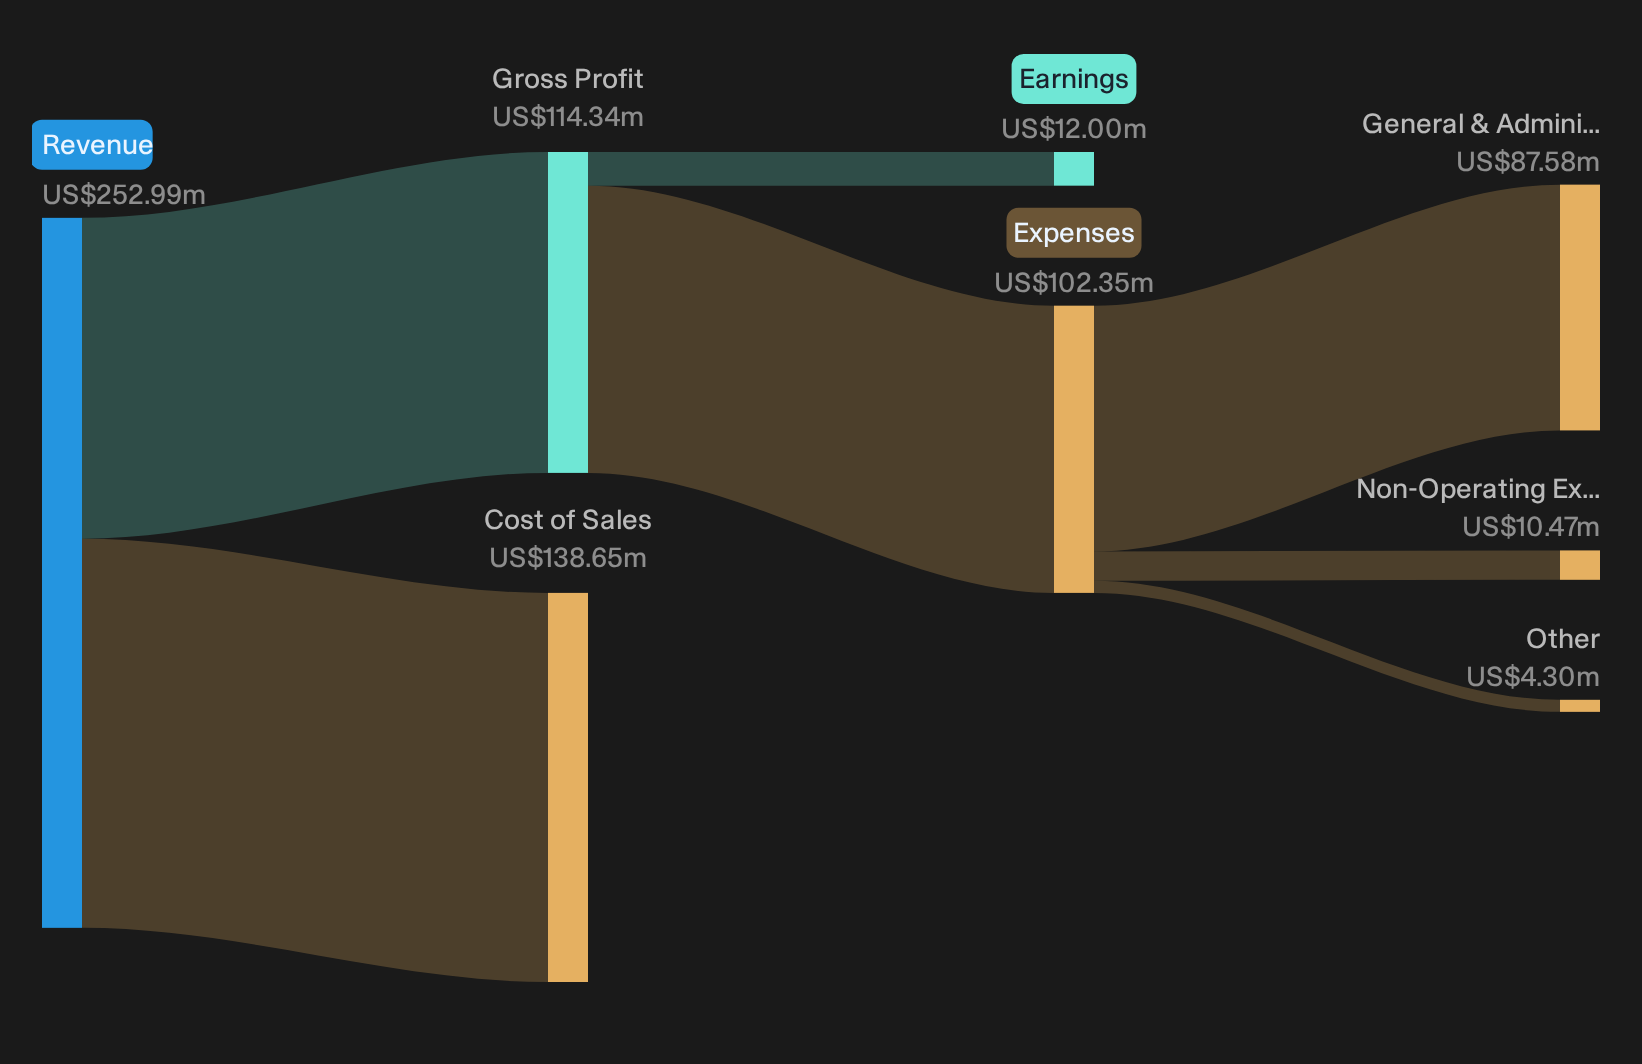
AI Mix Targets Met Early, Margins Back Them Up
The bullish pitch is that Information Services Group can reposition around AI and recurring work, then translate that into fatter economics and capital returns.
"Some analysts expect Information Services Group to focus on its AI related and recurring revenue streams, while aiming to expand margins and return cash to shareholders through dividends and buybacks."
Q3 shows that shift happening in practice. AI related revenue reached nearly US$34m and is now more than 50% of sales, two years ahead of the 2027 mix goal. Adjusted EBITDA margin expanded to 15.4%, the best in four years. Cash generation of US$12.3m funded US$2.4m of dividends and US$4.3m of repurchases.
AI Driven Fee Pressure Still Lurks In The Model
The bear story argues that the same AI tools driving demand for Information Services Group could also give clients more power to squeeze pricing.
"If clients apply similar cost expectations to the advisory and governance work that Information Services Group provides, fee rates and project sizes could come under pressure, which would weigh on revenue and net margins."
Current figures do not show that pressure biting yet. Revenue grew 4.4% year on year and EBITDA margin widened by about 200 bps. Consulting utilization held at roughly 74% with headcount flat. Management did flag billions of legacy outsourcing contracts up for renewal that may embed AI and lower unit economics, so the risk remains live even as margins improved this quarter.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Mispriced Earnings Power
Information Services Group illustrates how earnings and margins can shift without a major share price move. The real opportunity is identifying stocks that may be undervalued before the market reassesses their earnings power.
- Company 1 - 33% below our estimate - turns a large backlog of AI infrastructure and multicloud database deals into long-term contract workload demand.
- Company 2 - 42% below our estimate - expands manufacturing and supply chain capacity to support higher margin film and installation channels.
- Company 3 - 43% below our estimate - scales larger LED display projects and recurring software and services as venues and transport hubs adopt digital boards.
That is three of the list. See every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com