


EN
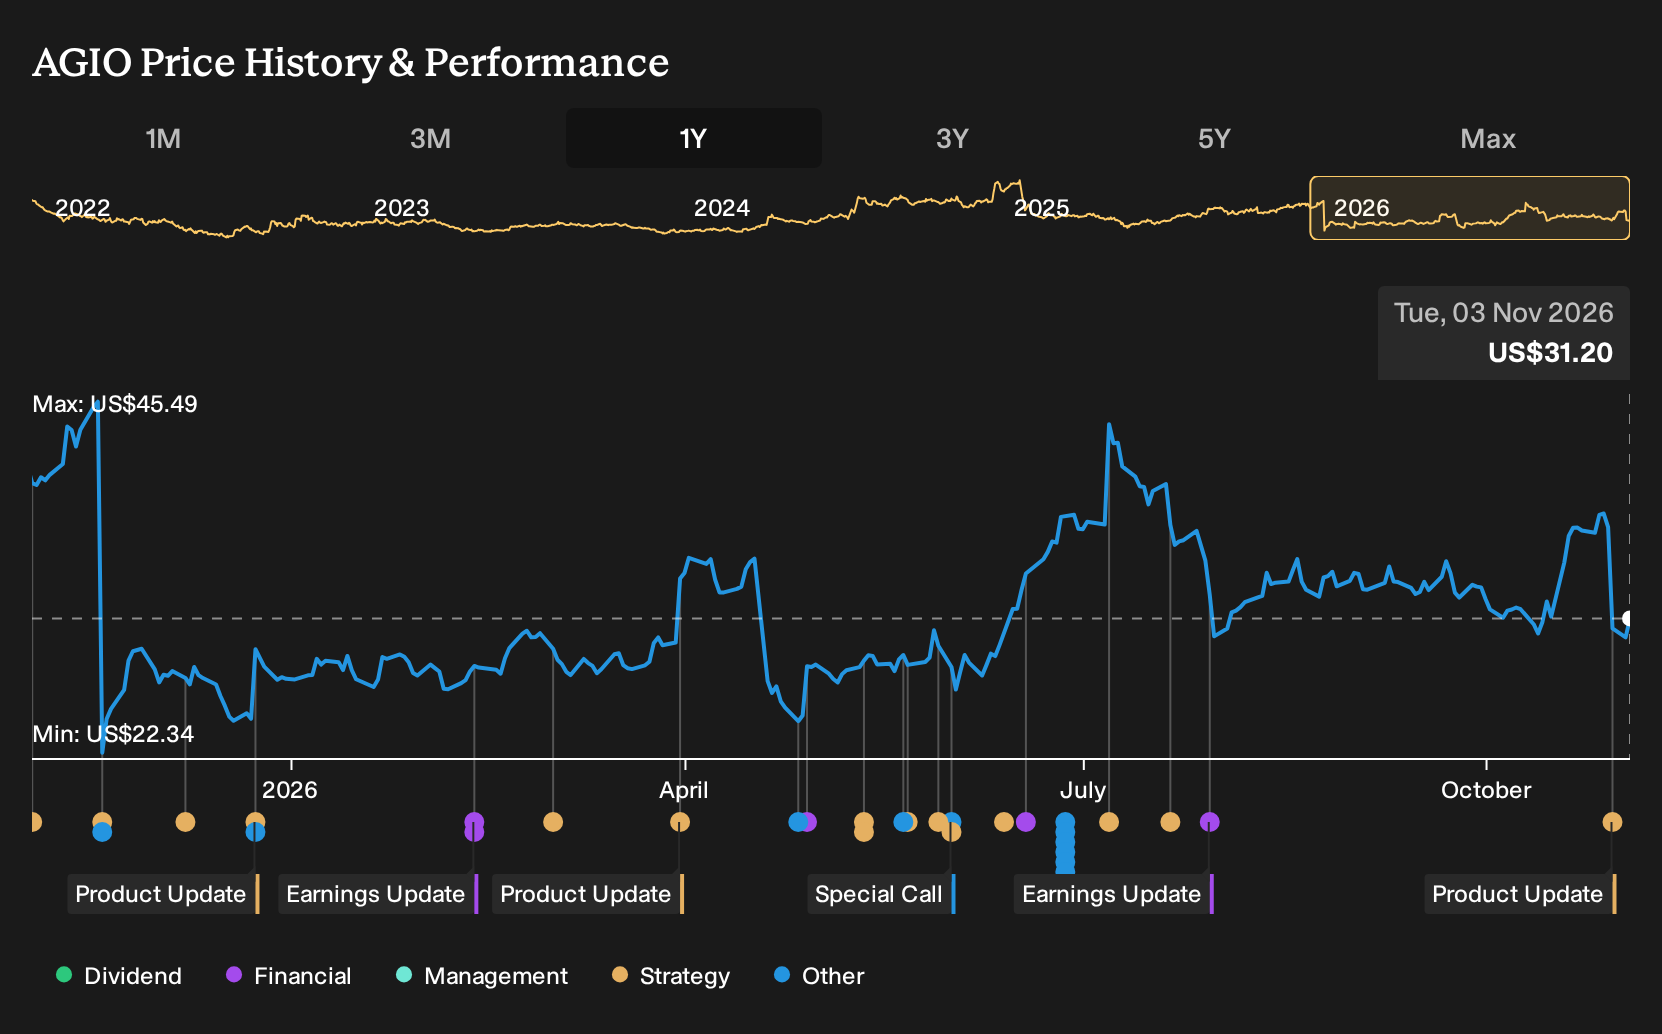
What Agios Pharmaceuticals (AGIO)'s FDA Review Delay Means For Shareholders
- Agios Pharmaceuticals reported that the FDA extended the PDUFA goal date for mitapivat’s sickle cell disease sNDA to February 1, 2027, after classifying updated safety information and REMS-related materials as a major amendment and continuing benefit risk discussions.
- The extension keeps mitapivat’s sickle cell profile anchored in long term RISE UP and REIGNITE trial work. It highlights execution demands around safety monitoring, labeling negotiations and any potential REMS that could influence how efficiently Agios converts its rare hematology pipeline into commercial use.
- The focus now shifts to how Agios Pharmaceuticals’ broader investment narrative absorbs an FDA review extension tied to mitapivat’s evolving safety package.
Compare how Agios Pharmaceuticals fits within rare disease and hematology plays by scanning a curated set of 19 high quality undiscovered gems that are still flying under most investors’ radars.
Agios Pharmaceuticals Investment Narrative Recap
To own Agios Pharmaceuticals, you need to believe the mitapivat franchise can support a focused rare hematology platform while the rest of the pipeline slowly broadens that base. The firm is still loss making, so the operating story is about turning growing rare disease revenue into a more efficient cost structure over time.
The FDA’s three month PDUFA extension keeps the mitapivat sickle cell decision as the key short term catalyst, now shifted to February 2027. The update appears operational rather than thesis breaking, although prolonged review or complex REMS requirements would keep regulatory risk and commercial timing front of mind for investors.
The current extension directly ties into the earlier sickle cell catalyst many investors were watching for November 2026. Agios has now supplied roughly nine months of additional safety data from the RISE UP open label period, with the firm stating the mitapivat benefit risk profile in sickle cell disease remains unchanged versus prior disclosures.
The same announcement also confirms ongoing labeling discussions and potential REMS elements, which now become part of the near term execution test. For anyone tracking catalysts, attention is on how effectively Agios Pharmaceuticals can address these requirements while continuing to build the broader mitapivat and AQVESME thalassemia commercial base and funding AG 236 into later stages.
Agios Pharmaceuticals' analyst narrative points to revenues of US$580.5 million and earnings of US$92.4 million by 2029, alongside an assumed 80.7% yearly revenue growth rate and an earnings swing of roughly US$503.7 million from a current loss of US$411.3 million.
Uncover how Agios Pharmaceuticals' fair value indicates a 47% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view treats the extended FDA review as a reminder that mitapivat’s sickle cell label could still end up quite narrow. This would cap how far Agios Pharmaceuticals can stretch its rare hematology platform. The lowest analysts were already penciling in around US$518.1 million of revenue and US$82.8 million of earnings by 2029, so their case was more cautious even before this news. Those forecasts show how far opinions can diverge. Use this as a prompt to compare several viewpoints before deciding how this updates your own thesis.
Explore another Agios Pharmaceuticals fair value estimate, including one that suggests it could be worth just $46.00!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Agios Pharmaceuticals research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Agios Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Agios Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Agios Pharmaceuticals?
Once you have a handle on Agios Pharmaceuticals and its mitapivat story, cast the net wider using the Simply Wall St Screener so your portfolio is built from a broader set of opportunities rather than a single rare disease catalyst.
- If you want income to play a bigger role in your returns, scan a curated group of reliable payers through 4 dividend fortresses that meet your yield and stability preferences.
- For investors who care most about balance sheet strength and fundamentals, filter for resilient operators using the list of solid balance sheet and fundamentals (24 results) that can handle tougher conditions.
- When you are hunting for ideas that the crowd has not fully focused on yet, broaden your watchlist with a focused 19 high quality undiscovered gems that could complement a position in Agios Pharmaceuticals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com