


EN
Black Rifle Coffee (BRCC) Stock Price Reels From Q3 Earnings Losses
BRC came into this week with a mixed recent record and a stock that had drifted but not collapsed. That changed after the Q3 2026 release, as the share price dropped about 23% to US$9.77 in a single session.
The coffee specialist just posted higher quarterly revenue of about US$108 million, yet reported another net loss and a sharply weaker basic earnings per share of about US$0.28 in the red. The gap between a stronger packaged coffee story and a heavier hit to profitability is what shocked the market, not the sales line itself.
Love the packaged coffee growth story at BRC but concerned about recurring losses and pressure on earnings per share? You can benchmark that view against a curated list of stronger operators with the list of solid balance sheet and fundamentals stocks (24 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs. Q3 2025): US$108.0 million vs. US$100.7 million (up about 7%)
- Net Loss (Q3 2026 vs. Q3 2025): loss of US$3.3 million vs. loss of US$0.5 million (loss widened sharply)
- Basic EPS (Q3 2026 vs. Q3 2025): loss of US$0.28 per share vs. loss of US$0.05 per share (per share loss increased materially)
- Gross Margin (Q3 2026 vs. Q3 2025): 37.1% vs. roughly 36.8% (slight margin improvement helped by tariff refunds)
Ask Charlie what Project Core really changes at Black Rifle Coffee.
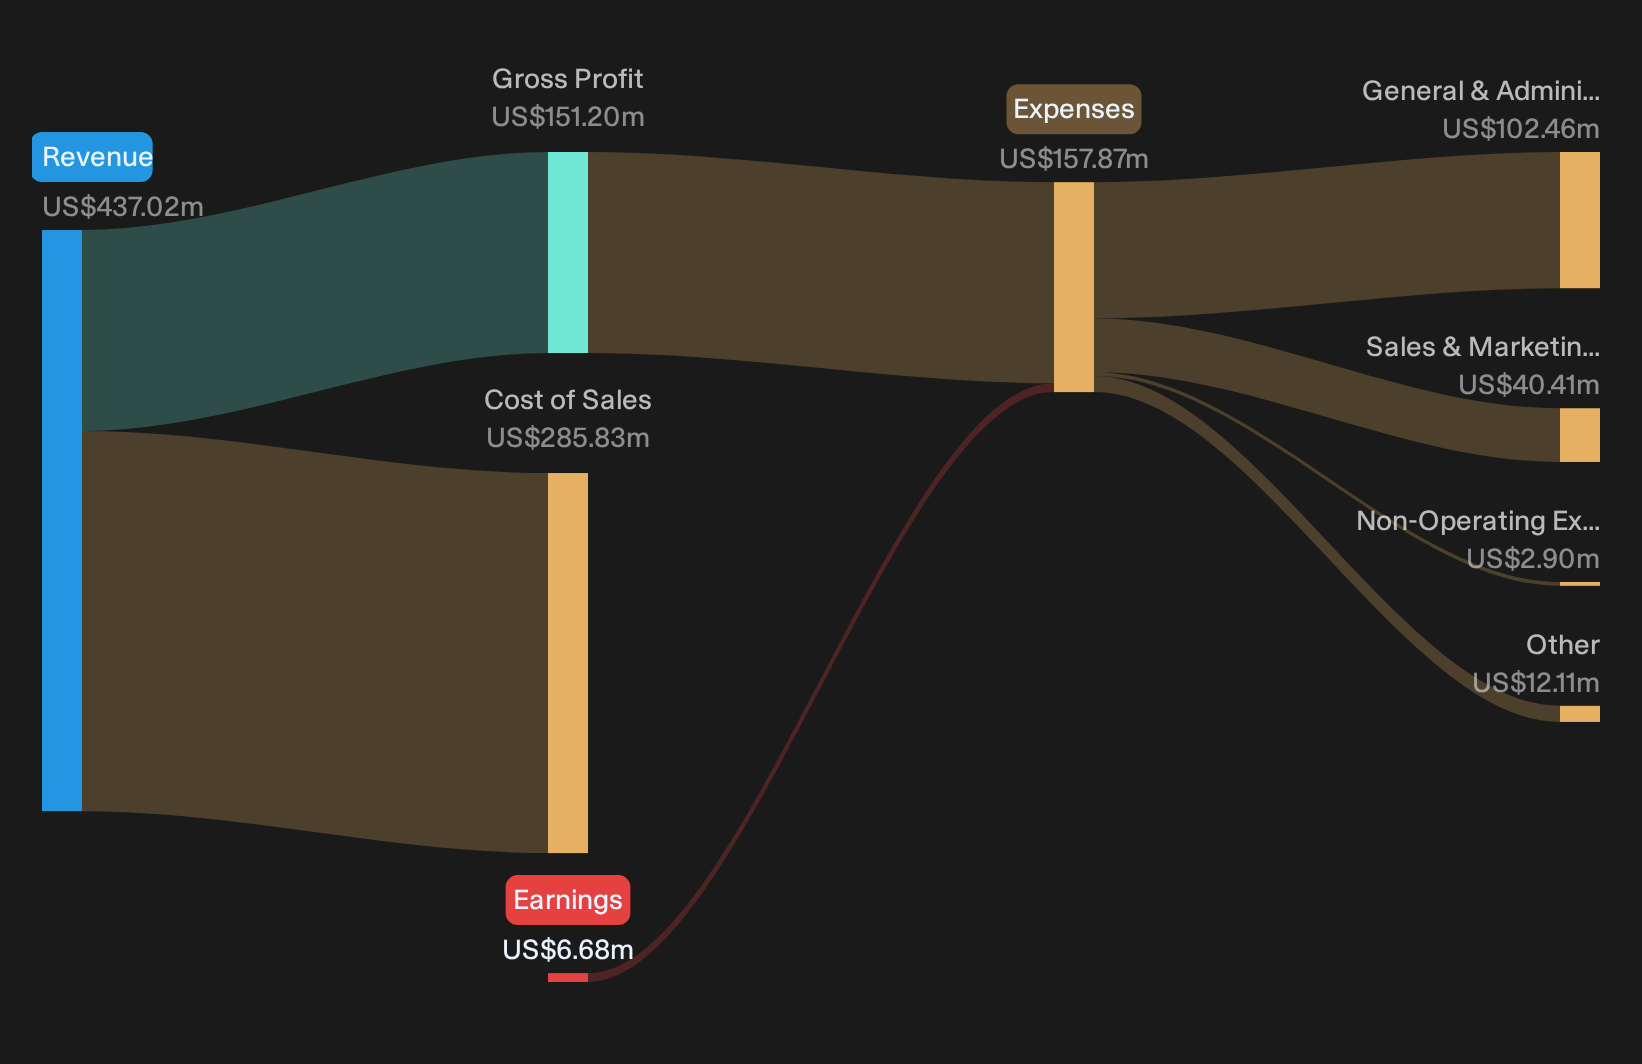
Evaluating BRCC’s Margin And Cash Flow Milestones
The bullish story hinges on Black Rifle Coffee turning distribution wins into leaner economics and stronger cash generation.
"The main thing that has to go right is that BRC sustains packaged coffee and wholesale momentum while keeping gross margin and free cash flow on the improved trajectory management describes."
On that score, Q3 does show partial follow through. Packaged volumes and wholesale channels helped push revenue to US$108 million, while gross margin held at 37.1% even with heavier trade spend once tariff refunds are stripped out. Adjusted EBITDA margin inched higher and free cash flow improved year to date, which supports the idea of a more cash generative model.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Bear Case On Black Rifle Coffee Still Has Teeth
Bearish investors worry that Black Rifle Coffee can win shelves yet still see profitability slip as costs and execution issues bite.
"Although Black Rifle Coffee is gaining packaged coffee shelf space with higher ACV and more items per grocery account, the recent 305 basis point gross margin decline to 33% in Q1 2026 from higher green coffee costs, tariffs, and DTC fulfillment onboarding shows how quickly input and execution issues can erode profitability, which can limit the earnings benefit of further distribution gains."
Q3’s 37.1% gross margin helped, but the story is complicated. The net loss widened to US$3.3 million and basic EPS loss deepened, despite revenue of US$108 million. That mix suggests the margin scare in the bearish narrative is not fully resolved. The 22.9% share price drop indicates that investors are treating this print as a miss on profitability milestones, not on top-line reach.
Hunt For Mispriced Operators Now
BRC reports that revenue momentum does not always translate neatly into earnings progress. The real opportunity is finding stocks that could be undervalued before the market shifts its view.
- Company 1 - 39% below our estimate - shows lidar units ramping from pilot volumes into full production programs as adoption broadens.
- Company 2 - 43% below our estimate - expands higher margin software and managed services as banks and retailers upgrade to advanced cash automation platforms.
- Company 3 - 16% below our estimate - converts program wins in complex industrial and aerospace hardware into ongoing production through tight operating discipline.
That is three of the list. See every one of the 34 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com