


EN
HUTCHMED (China) (AIM:HCM) Gains A Fresh Test As ORPATHYS Reviews Revive Undervalued Talk
HUTCHMED (China) (AIM:HCM) is back in focus after partner AstraZeneca secured European and Japanese reviews for the ORPATHYS plus TAGRISSO lung cancer regimen, supported by SAFFRON Phase III data and a prior US filing.
The latest regulatory milestones arrive after a mixed share price pattern for HUTCHMED (China), with a 14.61% 90-day share price return contrasting with a declining 1-year total shareholder return of 12.82% and deeper 3- and 5-year total shareholder return declines. This suggests that short-term momentum is improving, while longer-term holders remain under water.
Scan other oncology-focused opportunities on Simply Wall St by checking the curated 9 healthcare AI stocks, which could sit alongside HUTCHMED (China) in a research watchlist.
HUTCHMED (China) now has a deeper oncology pipeline and fresh trial momentum, yet the share price history tells a tougher story. Does that recent rebound leave the stock still looking cheap, or already fully reflecting the promise?
Most Popular Narrative: 41% Undervalued
HUTCHMED (China) closed at £2.04 against a widely followed fair value estimate of £3.46. This frames the current debate around how much optimism is already in the price.
Expansion of approved indications and upcoming NDA submissions for key oncology products (savolitinib and fruquintinib) are set to drive higher revenue growth, leveraging strong demand from an aging population and increased chronic disease prevalence in China and globally.
Launches and global expansion of FRUZAQLA, including strong growth outside China (notably in Japan and anticipation of further global rollouts), position the company to capture rising healthcare spending and broader reimbursement coverage, supporting robust top-line growth.
What is behind that 41% gap in perceived value and today’s share price 6 investors see HUTCHMED (China) as 41% undervalued.
The prevailing narrative applies a 7.56% discount rate and arrives at a £3.46 fair value. This sits comfortably above the current £2.04 level while still accounting for execution risks, heavy R&D spend, and regulatory uncertainty that feature prominently in HUTCHMED (China)'s story.
For readers weighing that framework, the key tension is that HUTCHMED (China) scores only 2 on Simply Wall St's internal value score, yet is also assessed as trading 58.4% below an internal estimate of fair value and below an estimated future cash flow value of £4.90. The share price is therefore being judged against optimistic long term earnings assumptions and a relatively high future P/E multiple of 43.8x that analysts use in their forecasts.
Result: Fair Value of £3.46 (UNDERVALUED)
Still, the HUTCHMED (China) story could look very different if competition intensifies in key cancer markets or if high R&D spend does not translate into successful drugs.
Find out about the key risks to this HUTCHMED (China) narrative.
Another View: What Multiples Say About HUTCHMED (China)
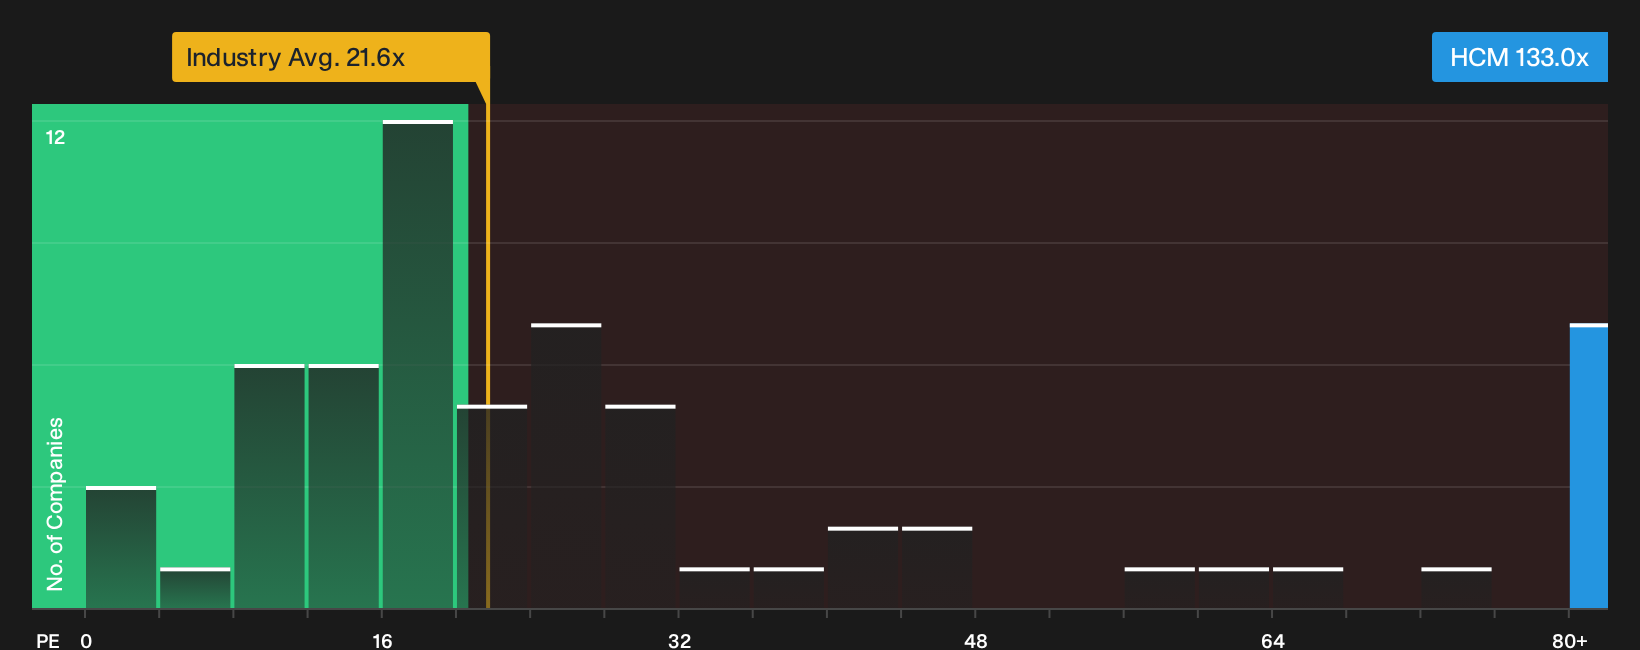
The headline story paints HUTCHMED (China) as undervalued, yet the P/E picture looks far less forgiving. On 133x earnings, the stock trades well above the European pharmaceuticals average of 21.6x, the peer group on 19.1x, and a fair ratio of 29.1x that the market could move toward over time.
That gap points to a meaningful risk that sentiment or earnings expectations may need to catch up to the price, not the other way around. This leaves you deciding whether the premium multiple is a sign of quality or simply a lot of hope baked in already.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early inflection: either way HUTCHMED (China) has both clear concerns and clear positives that you need to weigh for yourself. If you want a concise snapshot of both sides before deciding what the story looks like from here, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HUTCHMED (China)?
Do not stop with a single oncology story. Spread your research across different styles so you are not relying on one high conviction bet.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (10 results) that highlight businesses with cleaner finances and room to handle surprises.
- Hunt for mispriced quality using the 15 high quality undervalued stocks to see which companies combine stronger fundamentals with prices that lag underlying strength.
- Lock in potential income streams by reviewing the 4 dividend fortresses that focus on yields from established payout histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com