


EN
Should Uzbekistan Loan Shift Require Action From TBC Bank Group (LSE:TBCG) Investors?
- TBC Bank Group has been gaining attention for its push to expand digital and universal banking in Georgia and Uzbekistan, while gradually reshaping its Uzbek loan book away from unsecured cash loans toward business, credit card, auto and secured SME lending.
- The combination of strong insider ownership and management conviction around this shift in Uzbekistan highlights how tightly aligned leadership is with the long term outcomes of its diversification plan.
- We will now look at how this Uzbekistan loan book reshaping could influence TBC Bank Group's broader investment narrative for investors.
Scan other fast growing, high conviction banking and fintech plays alongside TBC Bank Group with our curated 5 high quality undiscovered gems, tailored for under the radar opportunities with solid fundamentals.
TBC Bank Group Investment Narrative Recap
To be comfortable as a shareholder in TBC Bank Group, you need to believe its digital banking push and expansion in Georgia and Uzbekistan can keep translating into healthy usage, while the Uzbek loan book clean up does not erode returns. The short term swing factor is how successfully management keeps net interest margin and credit costs balanced as unsecured cash exposure reduces.
The biggest near term risk remains asset quality and regulation in Uzbekistan. Non performing loans there have already lifted the group NPL ratio to 3.3%, and cost of risk is guided to peak in the low to mid teens. If loss rates or new consumer loan rules stay tough rather than easing, earnings could feel pressure.
The most relevant development for this story is the shift in Uzbekistan away from unsecured cash loans toward business, credit card, auto and secured SME lending. That change directly affects where TBC Bank Group earns interest income and how exposed it is to consumer credit shocks in that market.
In terms of catalysts, this migration could matter in two ways. A broader mix of secured and business lending can support a more balanced net interest margin and give the Uzbek franchise more fee and ecosystem opportunities, particularly as payment volumes and card usage grow. The trade off is execution risk while non performing loans are elevated and new risk weight rules for consumer lending remain uncertain.
TBC Bank Group's narrative projects GEL 5.7b revenue and GEL 2.2b earnings by 2029. This assumes 21.9% yearly revenue growth and an earnings increase of GEL 0.7b from GEL 1.5b today.
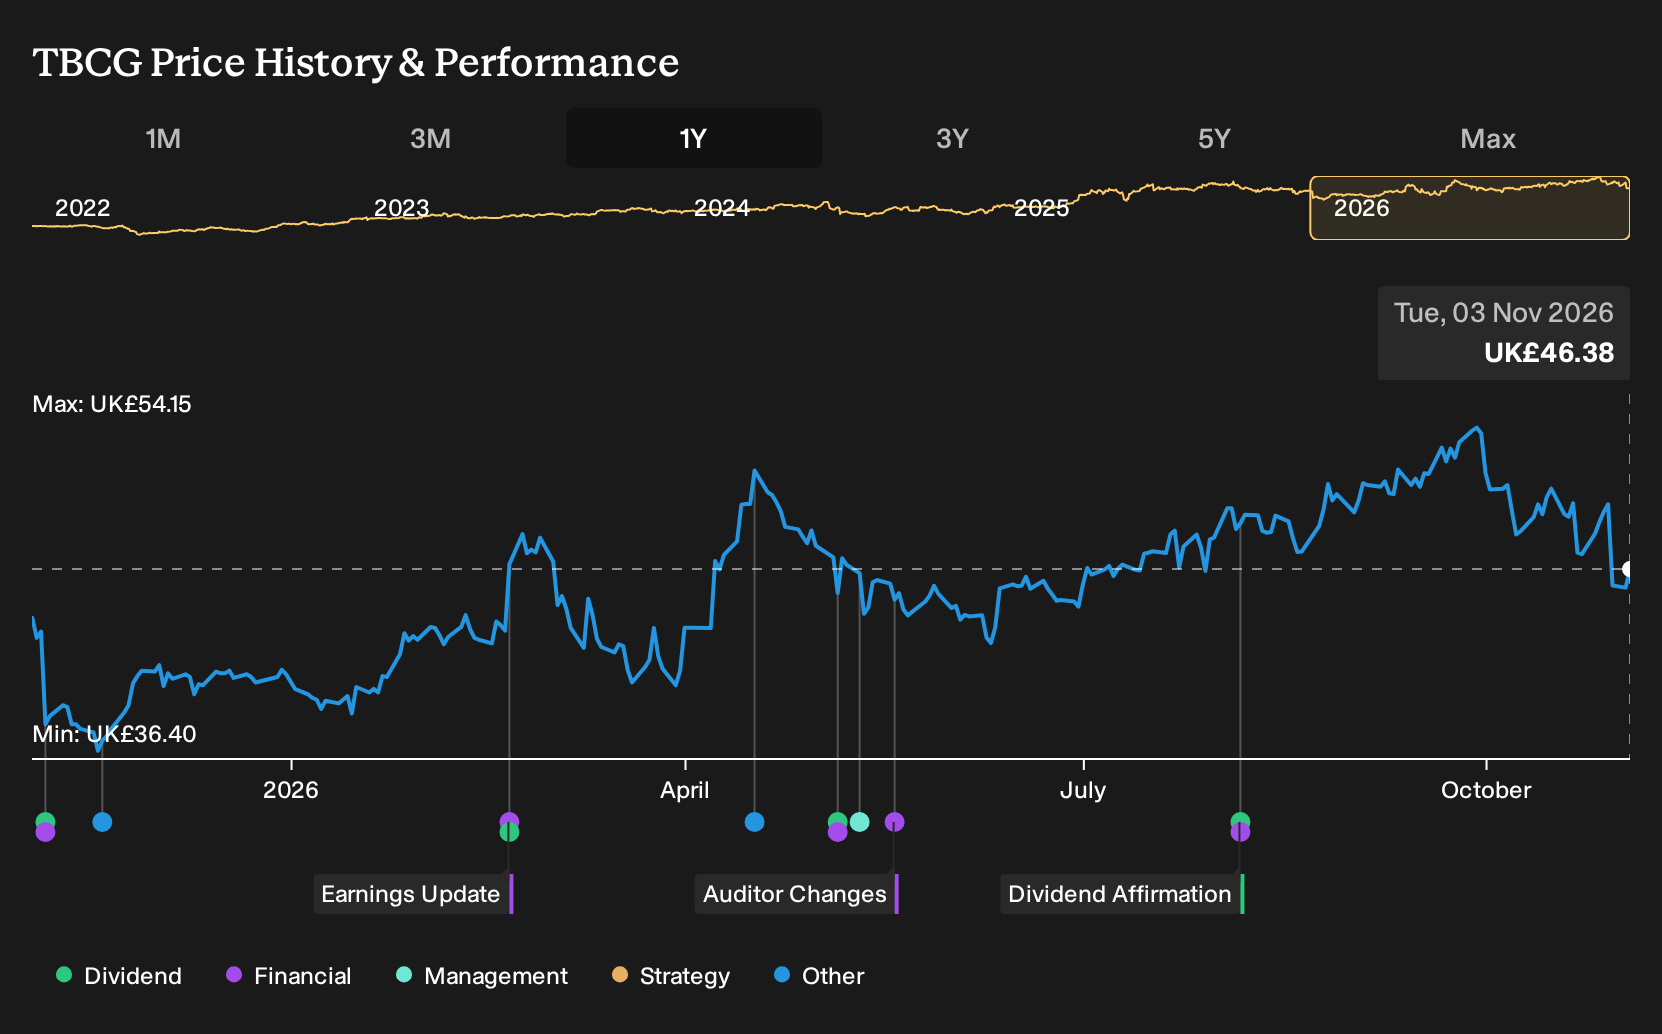
Uncover why TBC Bank Group's fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community stretch from about 57.6 to 117.0, so some retail investors see TBC Bank Group at roughly double the worth others do. Set that against Uzbekistan asset quality and regulatory uncertainty, and it becomes clear why opinions diverge. Explore several viewpoints before deciding your stance.
Explore 2 other TBC Bank Group fair value estimates, including one that suggests it could be worth just £57.65!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TBC Bank Group research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TBC Bank Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TBC Bank Group's overall financial health at a glance.
Looking for more TBC Bank Group investment ideas?
If the TBC Bank Group story has sharpened your thinking, use that momentum to widen your watchlist. The Simply Wall St Screener can help you line up other opportunities that fit the kind of balance between growth potential and risk control you are aiming for.
- For investors who care most about valuation discipline and quality fundamentals, start with a curated set of companies trading on appealing metrics through the 15 high quality undervalued stocks.
- If capital preservation and steadier profiles matter more to you than excitement, filter for businesses with stronger financial resilience using the 5 resilient stocks with low risk scores.
- When balance sheet strength is non negotiable, build a watchlist anchored in solid financial footing by screening for a list of solid balance sheet and fundamentals (10 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com